



PW Consulting: Biodegradable Micro Screws Market to Reach USD 544.41M by 2032 (CAGR 8.45%)

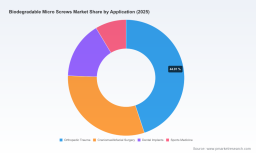
Biodegradable Micro Screws Market — Strategic Preview for 2026 Decision-Making
As Pw Consulting’s senior strategic advisor and lead industry analyst, I present a focused, executive-level preview of our new market study on biodegradable micro screws — a rapidly evolving subsegment of bioabsorbable orthopedic fixation devices. This briefing synthesizes macro dynamics, competitive posture, supply-chain pressures and practical strategic options that matter for executive teams preparing 2026 plans. We deliberately show the analytic depth you can expect from the full study while reserving the granular segment matrices and revenue-by-split tables for the report itself.
Biodegradable Micro Screws Market
Why this market matters in 2026
Biodegradable micro screws are transitioning from niche clinical adjuncts to mainstream options in selected fixation procedures. Between 2020 and 2025 the market recorded steady expansion, and our independent forecast positions the market to continue accelerating: the global market is projected to grow from a base of USD 308.55 Million (2025) to an estimated USD 544.41 Million by 2032, representing a compound annual growth rate (CAGR) of 8.45% over the forecast window. That combination of double-digit tailwinds in certain subsegments and sustained clinical interest makes 2026 a pivotal year for strategic repositioning — for incumbents, challengers and supply-chain stakeholders alike.
Biodegradable Micro Screws Market
Key macro forces shaping strategic choices
-
Regulatory momentum: Recent regulatory outcomes — notably multiple Breakthrough Device Designations and De Novo pathways being used for magnesium-based implants, plus CE approvals for major product families — have materially shortened commercialization timelines for novel materials. This reduces time-to-revenue for companies that can quickly assemble a robust clinical dossier.
Biodegradable Micro Screws Market -
Reimbursement inflection points: Select jurisdictions are beginning to recognize differentiated payment pathways for resorbable technologies that demonstrably reduce downstream procedures (e.g., hardware removal). Early reimbursement wins, especially transitional or pass-through payments in the US, materially shift the investment calculus.
-
Upstream feedstock volatility: Medical-grade biopolymer and magnesium alloy pricing is behaving more like a strategic variable than a fixed input. For example, PLA pricing and the broader medical biodegradable magnesium market dynamics are driving margin sensitivity for manufacturers, which in turn elevates the importance of procurement strategies and contract manufacture options.
-
Clinical economics and surgeon adoption: Clinical decision-making is converging on total cost-of-care arguments. The ability to demonstrate fewer secondary procedures, comparable mechanical performance for temporary fixation and favorable healing profiles is becoming the primary adoption vector.
Competitive landscape — who is setting the pace
-
Bioretec Ltd — Positioned as a materials-and-regulatory frontrunner. With a magnesium-based product portfolio (RemeOs™) and self-reinforced polymer lines, Bioretec’s recent regulatory milestones (including FDA Breakthrough Device Designation for a drill pin device, CE Mark expansion and US CMS transitional payment for a trauma screw SKU) highlight a strategy that blends product breadth with explicit reimbursement plays. These moves accelerate clinical adoption while creating visible barriers to entry through regulatory precedent.
-
Inion Oy — Focused on polymer-based bioabsorbables with predictable resorption profiles and instrument compatibility. Inion’s approach exemplifies a playbook built on surgical ergonomics (instrument compatibility and familiar workflows) and long-term clinical predictability — a pragmatic differentiation against newer alloy technologies.
-
Arthrex, Inc. — Leveraging broad orthopedics reach to mainstream bio-composite and enhanced polymer screws. Arthrex’s scale and distribution footprint allow it to push bioabsorbables into established surgical channels, tying material innovation to bundled procedure solutions and surgeon training programs.
-
Syntellix AG — A focused magnesium-alloy specialist with CE-marked MAGNEZIX® screws. Syntellix demonstrates the commercial viability of magnesium alloys in trauma and reconstruction use-cases and provides a real-world template for alloy-focused competitors on regulatory strategy and clinical claims.
Together, these companies illustrate three winning archetypes: (1) material-technology leaders securing regulatory and reimbursement moats; (2) incumbent orthopedics OEMs using scale and channel breadth to accelerate adoption; and (3) surgical-niche specialists converting clinical evidence into steady revenue streams. Each archetype implies different competitive responses for new entrants and supply-side partners.
What our full study delivers (practical, transaction-ready content)
-
Robust market model — time-series revenue projections from 2020 through 2032, with scenario-based outputs (base, conservative, accelerated) and a transparent set of assumptions supporting each scenario.
-
Go-to-market playbooks — tailored for platform owners, contract manufacturers and regional distributors, covering pricing strategies, surgeon engagement tactics, instrumentation bundling and channel partnerships.
-
Regulatory and reimbursement roadmaps — stepwise guides for FDA De Novo/Breakthrough vs CE strategies, plus country-level reimbursement tactics and persuasive evidence templates for payers.
-
Supply-chain and margin optimization levers — procurement hedges, specifications for medical-grade biopolymers and alloys, contract manufacturing evaluation criteria, and CAPEX sizing for in-house manufacturing expansion.
-
Competitive dossiers and clinical benchmarking — clinical endpoints, adoption rate proxies, and an expert-validated scoring framework that ranks competitors on technology, commercial reach, regulatory posture and clinical evidence.
-
M&A and partnership shortlist — tactical targets for bolt-on acquisitions and partnership types (co-development, licensing, distribution) that deliver near-term revenue lift and strategic positioning.
-
Risk matrix and mitigation playbook — technology, regulatory, reimbursement and supply-chain risk scenarios with specific mitigation actions and monitoring KPIs for 12 and 24-month decision cycles.
Strategic implications and recommended 2026 actions
-
Prioritize regulatory-first investments: For companies developing novel materials, securing an accelerated regulatory pathway or a regionally significant CE-clearance should be a top-3 near-term objective. Regulatory wins create not only market access but also leverage with payers and hospital procurement.
-
Design clinical programs for payer narratives: Craft trials that capture downstream cost offsets (e.g., lower reoperation rates) and quality-of-life outcomes. Smaller, tightly scoped randomized or registry-based studies can be sufficient to unlock differentiated reimbursement if designed with payers in mind.
-
Hedge raw-material exposure: Given observable PLA price dispersion across geographies and the rising market for medical magnesium alloys, secure multi-year supply agreements, qualify alternative feedstock suppliers and evaluate vertical integration only where scale economics are compelling.
-
Calibrate channel strategy to clinical niches: Targeting high-value niches (e.g., pediatric fracture fixation where hardware removal avoidance is compelling, or select sports-medicine indications) can accelerate surgeon advocacy and create references for broader adoption.
-
Evaluate partnership over build for scale-ups: Fast followers and mid-sized innovators should prioritize co-development or licensing agreements with established OEMs that have OR access, distribution, and surgeon training capabilities. This reduces capital intensity and compresses go-to-market timelines.
-
Price to total cost of care: Move away from implant unit-price competition; instead, articulate pricing models tied to demonstrable reductions in secondary procedures and overall episode cost. This creates room for premium pricing while aligning incentives with payers and providers.
-
Prepare M&A playbooks now: Buyers with a clear inorganic playbook (bolt-on materials tech, regional distribution networks, or complementary instrumentation) will find high-value targets as the market consolidates around the demonstrated technology leaders.
Signals to watch in 2026 — early warning dashboard
-
New regulatory precedents (additional Breakthrough or De Novo clearances for alloy or polymer technologies).
-
Reimbursement pilot outcomes in key markets demonstrating measurable reductions in downstream procedures.
-
Major supplier consolidation in medical-grade biopolymers or magnesium-alloy feedstocks that could compress supply or alter pricing dynamics.
-
Clinical registry learnings showing real-world performance divergence between alloy and polymer approaches.
Concluding synthesis — how to use this intelligence in 2026 planning
For leadership teams, 2026 is the year to convert promise into defensible commercial advantage. The macro trajectory is clear — the market is expanding robustly with an 8.45% CAGR across the forecast window, and the total addressable revenue pool is expected to materially increase through 2032. Winning will require an integrated approach: a regulatory-first mindset, evidence-generation that speaks to payers, disciplined raw-material strategies, and channel choices that exploit clinical niches for rapid surgeon uptake.
Our full report contains the granular inputs that enable transaction-level decisions — the region and application revenue splits, SKU-level forecasts, supplier cost curves, and a prioritized M&A target list. If your 2026 planning cycle includes product launches, portfolio rationalization, or M&A exploration in bioabsorbable fixation, this study is designed to be the operational playbook you can act on immediately.
For access to the full dataset, competitive scorecards and executable playbooks, please visit the report page or contact Pw Consulting’s Biodegradable Micro Screws practice. The granular segment tables and company-level revenue assignments referenced in this preview are available exclusively within the full publication.
For detailed analysis of this topic, please visit the official page: Biodegradable Micro Screws Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


