



PW Consulting: Desktop Industrial Robot Market to Reach $1.99B by 2032, 13.52% CAGR

Desktop Industrial Robot Market: Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present the executive lens on our latest Desktop Industrial Robot Market study — a strategic playbook designed to inform decisive corporate moves in 2026. The desktop robot segment is no longer an experimental adjunct to factory automation; it is a distinct, fast-growing market with meaningful implications for product roadmaps, supply chains, channel strategies, and M&A agendas. Our research, benchmarked to 2025 as the base year, tracks a clear momentum: a market size of USD 820.0 Million in 2025, accelerating at a compound annual growth rate of 13.52% across the 2026–2032 forecast horizon, to just under USD 2.0 Billion by 2032. These macro dynamics create a narrow window in 2026 for leaders to convert strategic intent into durable advantage.
Desktop Industrial Robot Market
Why this research matters for 2026 decision-makers
-
High-growth timing: With a mid-double-digit CAGR, the desktop robot market is moving from early adoption toward mainstreaming in several small-footprint industrial use cases. Decisions made in 2026 on product investment, channel expansion, and software ecosystems will determine market share trajectory through the rest of the decade.
Desktop Industrial Robot Market -
Actionable, risk-aware planning: The study combines forward-looking market sizing with scenario analysis and payback frameworks to help boards and operating teams prioritize investments that are resilient to near-term macro and supply shocks.
Desktop Industrial Robot Market -
Commercial leverage: The desktop form factor magnifies the importance of go-to-market execution. 2026 is a critical year to define pricing models (capex vs. robotics-as-a-service), partner economics, and training/service offerings that convert interest into repeatable revenue.
Market trajectory and what it signals
The desktop industrial robot market has more than doubled in the five years leading up to 2025, and with a projected path that continues at roughly a 13.5% CAGR, it will approach a near two‑billion-dollar market by the start of the next decade. This trajectory signals three important shifts for executives:
-
From point solution to platform: Buyers increasingly expect interoperable hardware, purpose-built end‑effector ecosystems, and companion software for cell-level orchestration.
-
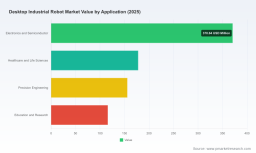
Acceleration of verticalization: High-mix, low-volume industries — notably electronics assembly, life sciences, and precision engineering — are converting bench-level automation experiments into standardized cells.
-
Channel and service premium: As deployments scale beyond pilot installations, total cost of ownership (TCO) considerations — uptime guarantees, rapid local support, and training — become differentiators.
Drivers and headwinds shaping 2026 strategies
-
Industry 4.0 and smart factories: The macro push toward flexible, small‑lot manufacturing continues to be a principal adoption driver. Desktop robots enable rapid reconfiguration of benchtop cells and align with digital factory initiatives.
-
Labor economics: Rising labor costs and skill shortages in precision assembly are widening the economic case for automating repetitive benchtop tasks — especially where manual dexterity and consistent cycle times are critical.
-
Standards and safety: International standards such as ISO 10218 and ISO/TS 15066 continue to define the regulatory envelope for collaborative desktop deployments. Compliance-first design shortens sales cycles in regulated sectors like medical devices and semiconductors.
-
Materials and supply chains: Structural materials (steel and precision aluminum alloys) underpinning robot frames remain exposed to global metals market dynamics. Procurement strategies and supplier diversification should be addressed in 2026 capex planning.
Competitive landscape: who is set up to win — and how
The competitive field is a mix of established automation OEMs, specialized precision roboticists, and nimble new entrants pursuing collaborative and desktop niches. Our report drills into strategic positioning across product, distribution, and after‑sales models for the core players currently shaping the landscape.
-
Janome (Japan): A veteran in Cartesian desktop systems, Janome’s JR series targets precision dispensing, screwing, and tight-footprint assembly. Their strength is reliability and a focus on industrial-grade performance for benchtop tasks.
-
Dobot (Shenzhen, China): Aggressive on cost-performance and rapid product iteration, Dobot’s desktop portfolio — including 4‑axis units — is tailored for lightweight automation and benchtop production, supported by broad exhibition presence and OEM partnerships.
-
DENSO Robotics (DENSO WAVE) (Japan): With deep roots in small assembly robots and SCARA architectures, DENSO combines industrial pedigree with global channel reach. Their compact models are engineered for high-throughput micro-assembly.
-
Mecademic (Montreal, Canada): Positioned on the premium end of the market, Mecademic’s ultra-compact, high-precision 6‑DoF arms are winning in applications where repeatability and footprint are decisive selection criteria.
-
TOYO Robotics and TM Robotics (Japan/UK): These vendors play a supporting and distribution role in key industrial corridors, enabling integrated solutions that pair desktop robots with electric actuators and peripherals.
-
NITTOSEIKO, Elephant Robotics, and USABotics: These firms illustrate divergent strategic plays — from precision-focused desktop machines to collaborative, education-to-industrial conversion kits and localised manufacturing for regional markets.
Recent industry movements — from product launches that push speed and payload thresholds to trade shows emphasizing practical integration — underscore a competitive race that is as much about software, integration, and support as it is about actuator or arm kinematics. Our study assesses these firms across product maturity, channel strength, service model, and scaling risk.
Strategic options for 2026 — recommended playbook
Based on our market model and scenario stress tests, PW Consulting recommends a focused set of actions for different stakeholders in 2026. Each recommendation is actionable within an 18–36 month horizon.
-
OEMs (robot manufacturers): Prioritize modular platforms and open APIs to accelerate ecosystem adoption. Invest selectively in control software and intuitive programming interfaces to lower integration friction for non-expert buyers.
-
System integrators: Build verticalized solution packages (hardware + tooling + validation protocols) tailored to high-value micro-assembly use cases. Offer bundled service contracts to capture recurring revenue.
-
Component suppliers: Hedge material exposure via dual-sourcing and strategic stockpiles for critical alloys. Position actuators and sensors as upgradeable modules to increase share of wallet.
-
Investors and corporate development teams: Target tuck-in acquisitions that add service capabilities or specialized end-effectors rather than broad hardware plays; look for companies with strong IP in precision motion and repeatability.
-
Commercial teams: Pilot flexible pricing (subscription, pay-per-hour, managed automation) in segments where TCO is the deciding factor. Use outcome-based proofs to expand into larger accounts.
-
Policy and compliance leads: Map product roadmaps against ISO safety standards and sector-specific validation requirements early to avoid costly redesigns during commercialization.
What PW Consulting’s report delivers — practical, operational tools
To move from strategy to execution, our Desktop Industrial Robot Market study includes a suite of implementable assets:
-
A transparent market model with historical baselines and forward scenarios that quantify upside and downside cases under alternative adoption curves.
-
Investment case templates and ROI calculators tuned for desktop deployments (bench-level cycle time, labor substitution, and uptime assumptions).
-
Go‑to‑market playbooks for OEMs and integrators, including channel economics, training curricula, and pilot-to-scale conversion checklists.
-
Vendor assessment frameworks and supplier scorecards to evaluate partners on manufacturability, service SLAs, and localization capability.
-
Regulatory mapping and implementation guidance aligned to current ISO safety standards and industry-specific compliance pathways.
-
Scenario-based M&A screening templates that prioritize capability gaps and integration risks over headline valuations.
How to use the intelligence in 2026 — practical next steps
-
Run a rapid internal assessment: map current product roadmaps, channel reach, and service capabilities against our scenarios to identify immediate “no-regret” moves.
-
Initiate 6–9 month pilots with clear success metrics (cycle time reduction, yield improvement, TCO payback) and predefined scale thresholds.
-
Lock in supplier risk mitigation: secure materials and critical components through contractual options or alternative sourcing to protect 2026 deployments.
-
Design commercial pilots that test flexible pricing and managed-service models to uncover the most scalable revenue streams by end-user segment.
Closing — why act now
The marketplace for desktop industrial robots is young but thickening fast. The projected near-term growth trajectory creates both opportunity and urgency: leaders who define platform boundaries, operationalize support, and monetize service stacks in 2026 will capture disproportionate returns as the market scales. PW Consulting’s study translates the market’s macro momentum into hands-on tools and decision frameworks that executives can deploy immediately — while withholding the granular segmentation data used to calibrate those models to encourage direct engagement with the full report.
For the complete datasets, granular regional and application breakdowns, and the proprietary competitive scoring that underpins the recommendations above, please refer to the full Desktop Industrial Robot Market report on our website.
For detailed analysis of this topic, please visit the official page: Desktop Industrial Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


