



PW Consulting: Fully Rugged Tablets Market to Reach USD 2,103.8 Million by 2032 (7.35% CAGR)

Fully Rugged Tablets Market: Strategic Preview for 2026 Decision-Makers
As organizations plan capital investment and field IT strategies for 2026, the fully rugged tablets market presents a mix of steady growth, concentrated competition, and elevated operational risk that demands a disciplined, evidence-based response. Our new market study at PW Consulting synthesizes five years of historical performance and a forward-looking forecast through 2032 to equip procurement leaders, CIOs, and strategy teams with the insights they need to make defensible decisions. This preview outlines the strategic value of the study and highlights the practical guidance contained in the full report — while reserving the granular segment tables and proprietary scenario outputs for subscribers.
Fully Rugged Tablets Market
Why this market matters to enterprise strategy in 2026
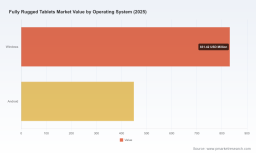
Fully rugged tablets are no longer a niche procurement line item; they are a mission-critical enabler across defense, public safety, field service, utilities, transportation, and heavy industry. From secure government deployments to logistics orchestration and frontline inspections, these devices connect operational workflows to cloud services, IoT sensors, and analytics engines. Our market model shows that the industry expanded from under USD 1 billion in 2020 to approximately USD 1.28 billion in 2025 and is forecast to continue its growth trajectory — reaching roughly USD 1.42 billion in 2026 and surpassing USD 2.1 billion by 2032 under a mid-single-digit compound annual growth rate (CAGR of 7.35%). That scale and durability make vendor selection, supply-chain resilience, and lifecycle economics strategic priorities for 2026 procurement cycles.
Fully Rugged Tablets Market
High-level market structure and competitive dynamics
-
Concentration and competitive posture: The market exhibits a clear oligopolistic tilt. The top three suppliers control a majority share, and the top five capture a significantly larger portion — an architecture that favors scale, certification depth, and integrated after-sales capabilities. For buyers, this translates into a choice between established OEMs with broad warranty and certification footprints and smaller specialists that offer customization and niche integrations.
Fully Rugged Tablets Market -
Product and certification as differentiators: Device certification (e.g., MIL-STD updates, IP rating, FIPS security accreditation) and platform breadth are primary procurement filters. Recent product launches and certification milestones by leading suppliers demonstrate that R&D and compliance investments are central to competitive positioning.
-
Supply-side constraints: Component lead times and raw material cost pressures materially affect procurement timing. Extended CPU lead times and screen-material price increases are real considerations for 2026 deployments, forcing procurement teams to weigh trade-offs between specification upgrades and availability.
Key market forces shaping 2026 decisions
-
Technology and certification: The update to MIL-STD-810H in 2024 tightened thermal and vibration requirements, raising the bar for devices used in defense and extreme-field operations. At the same time, security certifications such as FIPS are becoming mandatory for certain government and regulated industry contracts — vendors that can demonstrate both ruggedization and accredited security will command preferential procurement treatment.
-
Component and materials risk: Lead times for high-performance processors have extended to multiple months in several cases, and the cost of specialized cover glass has risen materially. These dynamics increase the risk of schedule slippage for rollouts and can push total cost of ownership (TCO) higher unless mitigated via strategic sourcing or design choices that reduce dependency on scarce inputs.
-
Geopolitical and regulatory friction: Export controls on advanced semiconductors and evolving trade policy introduce regional variations in product availability and certification pathways. Organizations operating multi-jurisdictional fleets should expect longer procurement cycles and possible necessity for dual-sourcing strategies in 2026.
-
Connectivity and endurance expectations: The adoption of 5G-capable fully rugged tablets and hot-swappable battery architectures is accelerating, driven by field telemetry and continuous uptime requirements. These features increasingly define the device specification for mission-critical deployments.
Competitive snapshot: what to watch from leading suppliers
-
Getac (Taiwan) — Continues to sharpen its product line with larger-display and higher-performance launches, targeting defense and industrial buyers requiring MIL-STD and high ingress protection. Their recent product introductions emphasize processing power and ruggedized displays suitable for data-intensive field tasks.
-
Panasonic (Japan) — The Toughbook lineage remains synonymous with public safety and logistics use-cases; successive platform updates have focused on connectivity (including 5G) and battery runtime, which are decisive for extended field operations.
-
Dell (USA) and HP (USA) — Both bring enterprise IT integration strengths and security certifications that ease deployment into enterprise and government estates. Recent certifications and product refreshes underline a push toward embedding compliance and manageability into rugged endpoints.
-
Zebra (Xplore Technologies), DT Research, and MobileDemand — These specialists continue to win on vertical-tailored solutions (energy, oil & gas, first response, warehousing), delivering purpose-built accessories, scanning integrations, and service models that appeal to niche buyers.
For buyers, supplier evaluation must balance product ruggedness and certification coverage with after-market service, field repairability, and roadmap clarity. Our report provides a vendor scorecard that goes beyond glossy specs — assessing lead-time exposure, certification currency, third-party security audits, and installed base support — helping procurement teams create defensible RFx evaluation criteria for 2026.
Actionable strategic implications for 2026 planning
-
Procurement timing and inventory strategy: Given extended processor lead times and material pressures, build procurement calendars that prioritize critical fleet replacements and stagger non-urgent refreshes. Consider limited buffer stock for high-usage models and negotiate forward delivery slots with preferred OEMs to hedge supply risk.
-
Specification trade-off framework: Use a decision matrix that quantifies the operational value of high-spec components (e.g., highest-tier processors, premium cover glass, 5G modems) against lead-time risk and TCO impact. Not every frontline role requires the absolute highest rugged rating; optimizing spec by persona reduces unnecessary cost and procurement delay.
-
Security and compliance gating: Make certification (e.g., recent MIL-STD updates, FIPS where applicable) a pass/fail procurement gate for relevant contracts. Embedded security features and vendor-managed key lifecycles should be assessed for government and regulated industry deployments.
-
Service architecture and repairability: Prioritize vendors offering rapid field-repair options, modular parts, and transparent repair pricing. A service-centric procurement contract can lower lifecycle cost and improve uptime compared with lowest-first-cost buys.
-
Supplier diversification and nearshoring: Consider dual-sourcing and regional supplier mixes to mitigate geopolitical export risk and tariff exposure — especially for organizations with operations in jurisdictions affected by semiconductor export controls.
-
Data-driven TCO modeling: Model total lifecycle cost across scenarios that incorporate higher component costs, extended lead times, and accelerated replacement cycles due to harsher operating conditions. Our report includes a TCO template you can adapt to your fleet and operating profiles.
What’s inside the full PW Consulting report (practical deliverables)
-
Comprehensive market model spanning 2020–2032 with transparent methodology for sizing and forecasting demand drivers and sensitivities.
-
Scenario planning suites that stress-test supply shocks, regulatory shifts, and rapid technology adoption — delivering decision-ready contingencies for procurement and finance teams.
-
Vendor benchmarking and scorecards that integrate product certification, procurement lead-time exposure, security posture, and field-service capabilities.
-
Buyer personas and role-based spec sheets that translate operational requirements into defensible device specifications and sourcing checklists.
-
Procurement playbooks, RFx templates, contract clauses, and negotiation scripts focused on warranty, spare-part provisions, and SLAs for field repair.
-
Supply-chain risk register and mitigation playbook covering component lead times, raw material cost volatility, and geopolitical export controls.
-
TCO calculators and lifecycle refresh calendars you can repurpose for capital budgeting and vendor selection in 2026.
How to use this study for board-level decisions
Board and executive teams should treat the fully rugged tablet portfolio as a strategic asset class. Investments in rugged endpoints affect continuity of operations, compliance risk, and the economics of field labor. The study provides the empirical basis to:
-
Approve capital allocation for fleet modernization with scenario-based ROI that incorporates procurement timing and supply risk;
-
Set security and compliance thresholds for purchasing mandates;
-
Define vendor partnership strategies that balance scale, specialization, and resilience;
-
Authorize pilot programs for next-generation connectivity and battery architectures that lower per-unit operational risk;
Final note — where this preview stops and the full intelligence begins
This introduction highlights the strategic contours and practical implications for 2026 decision-making. To preserve the commercial integrity of our proprietary models and granular segment analytics, detailed regional and application-level splits, price-by-specification tables, and the full vendor financial benchmarking are included exclusively in the full report and the accompanying data annex. For teams preparing RFPs, board briefs, or five-year capital plans, accessing the complete dataset and supplier scorecards will materially shorten decision cycles and reduce procurement risk.
PW Consulting’s Fully Rugged Tablets Market study is designed to convert market intelligence into executable procurement and deployment strategies. Contact our research team to schedule a briefing and receive the full report, annexed models, and a tailored implementation workshop for 2026 readiness.
For detailed analysis of this topic, please visit the official page: Fully Rugged Tablets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


