



PW Consulting: Silicone Resin Market — USD 5.52B in 2025 to USD 8.42B by 2032 at 6.22% CAGR

Silicone Resin Market 2026: Strategic Preview for Corporate Decision-Makers
Introduction — Why 2026 is a Strategic Inflection Point
The global silicone resin market is transitioning from recovery to strategic expansion. After a steady rise from approximately USD 4.09 billion in 2020 to USD 5.52 billion in 2025, the sector is projected to continue its growth arc through the 2026–2032 forecast period at a compound annual growth rate (CAGR) of 6.22%, reaching roughly USD 8.42 billion by 2032. For executives planning capital allocation, product roadmaps, or M&A strategies in 2026, this report delivers the kind of forward-looking, operationally oriented intelligence that converts market visibility into actionable choices.
Silicone Resin Market
Market Snapshot: Performance and Structure
-
Historic momentum (2020–2025): Demand recovered across coatings, electronics, and specialty industrial applications, lifting global revenue by more than 35% over five years.
Silicone Resin Market -
Near-term trajectory (2026–2032): At a 6.22% CAGR, the market profile favors premiumization—higher-margin, technically differentiated resin grades—and selective geographic expansion tied to electronics and clean‑energy value chains.
Silicone Resin Market -
Competitive concentration: The market exhibits moderate concentration, with the top three firms accounting for a meaningful share of revenue and the top five representing a clear leadership tier. This dynamic creates differentiated pathways for scale players and niche specialists alike.
Drivers and Dynamics Shaping 2026 Decisions
Several structural forces will dominate corporate strategy in 2026. Understanding their interplay is essential for risk-managed growth.
-
End-market pull for performance: Demand for heat-stable, weather-resistant, and electronic-grade silicone resins continues to expand, driven by higher operating temperatures in electrified powertrains, miniaturized consumer electronics, and more stringent exterior durability expectations in coatings.
-
Raw-material and input-cost volatility: Metallic silicon price volatility has meaningfully impacted cost-of-goods-sold dynamics. Recent upward movement in feedstock pricing underscores the need for procurement hedging, differentiated supplier terms, and margin-protection strategies.
-
Regulatory and compliance overlays: Regional chemical regulations have already altered formulation choices and supply chains. Compliance-driven reformulation and certification are now part of routine product development budgets.
-
Logistics, classification and trade barriers: Shipping code amendments and tariff regimes are materially affecting landed costs and lead times. Companies must embed regulatory monitoring into commercial planning to avoid margin erosion and service disruptions.
-
Sustainability and certification filters: Sustainability screening—whether linked to green building standards or procurement ESG policies—is reshaping buyer preferences. Scrutiny on fluorinated chemistries and persistent substances is creating both product-level risks and market opportunities for compliant alternatives.
Regulatory & Operational Noise to Watch
-
Regulatory restrictions on specific cyclic siloxanes are already influencing formulations in regulated markets, prompting reformulation and new product launches designed to meet tightened thresholds.
-
Transport classification updates and enhanced labeling requirements are increasing downstream compliance costs and shaping route-to-market decisions for suppliers and consumers alike.
-
Trade measures, including tariff regimes, continue to incentivize regional sourcing and local footprint strategies for players targeting growth in tariff-impacted markets.
Segmentation Lens — Where the Value Is (and What We Withhold)
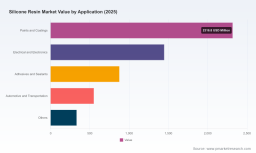
The report organizes demand by region, resin chemistry, and end-application to expose where margin pools and structural growth pockets exist. We deliberately avoid listing granular share or dollar splits in this preview; instead, the full analysis provides a downloadable model with line-item breakdowns by geography, type, and application. For executives, the critical takeaway is this: commercial and R&D priorities should be informed by both aggregate market growth and micro-segmentation dynamics that affect price realization and technical differentiation.
Supply-Side Landscape and Strategic Implications
Market leadership is held by a mix of global chemical majors and specialized silicone producers. The sector’s structure presents distinct strategic playbooks:
-
Scale leaders leverage integrated value chains and regulatory compliance capabilities to offer broad portfolios and secure large-volume contracts.
-
Specialists and regional players compete on application engineering, custom-formulation services, and speed-to-spec.
Notable corporate maneuvers over the last 18 months illustrate divergent yet complementary strategies: selective capacity expansion to serve coatings demand, targeted product launches for high-heat electronics segments, and certification updates to unlock regulated markets. These moves signal where incumbents expect the highest returns and where new entrants may face the toughest competition.
Competitive Mapping — Core Players and Strategic Postures
-
Dow (Midland, Michigan) — A global industrial champion with a SILRES portfolio oriented to protective coatings, electrical insulation, and molded parts. Recent certification work enhances access to regulated markets.
-
Wacker Chemie AG (Munich) — A technology-driven supplier focusing on high-temperature coatings, release agents, and electronics encapsulation; capacity expansions underscore confidence in coatings demand.
-
Shin-Etsu Chemical (Tokyo) — The world’s largest silicone producer; product breadth includes toner and paint resins and recently launched heat-resistant grades for automotive electronics.
-
Momentive Performance Materials (Waterford, New York) — Specialist in high-performance resins for industrial and automotive applications, emphasizing technical services and tailored solutions.
-
Elkem ASA (Oslo) — Offers resins used in electrical varnishes and high-performance coatings; represents a balanced play between industrial chemistry and application know-how.
-
KCC Corporation (Siheung, South Korea) — Regional champion with strong position in coatings, inks, and electronics protection; competes on application engineering and regional service.
Market concentration metrics indicate a meaningful advantage for the upper tier, but also leave room for agile specialists and regional champions to capture niche premium segments.
What This Means for 2026 Strategy — Actionable Recommendations
Companies facing 2026 choices should orient plans across five practical dimensions:
-
Portfolio & R&D: Prioritize heat-resistant and electronics-grade formulations that align with electrification and miniaturization trends. Invest in low‑risk reformulations to pre-empt regulatory headwinds.
-
Supply chain & procurement: Implement multi-source strategies for key feedstocks, negotiate performance-linked contracts, and explore regional production or tolling options to mitigate tariff and transport risk.
-
Commercial & pricing: Differentiate on total cost of ownership—service levels, regulatory support, and certification—rather than on price alone. Use modular pricing tied to specification tiers for premium grades.
-
CapEx & footprint decisions: Align capacity investments with validated long-cycle contracts and customer commitments; where demand uncertainty persists, consider flexible capacity options such as co‑manufacturing or asset-light partnerships.
-
M&A & partnerships: Target bolt-on acquisitions that add formulation capabilities, regional market share, or certification assets. Joint development agreements with OEMs can accelerate adoption in regulated end-markets.
Risk Matrix and Scenario Planning
Executives should prepare for three actionable scenarios:
-
Base case: Gradual premiumization and steady demand growth (reflective of the central 6.22% CAGR) with manageable cost headwinds.
-
Upside: Rapid adoption of high-margin specialty resins in electronics and industrial coatings, driven by accelerated electrification and stricter durability specs.
-
Downside: Supply-chain shocks or tighter chemical restrictions that force unplanned reformulation and elevate compliance costs—requiring contingency sourcing and faster regulatory engagement.
What PW Consulting’s Full Report Delivers
This market brief is a strategic teaser. The full PW Consulting Silicone Resin Market study contains the operational detail that decision-makers need to convert insight into execution, including:
-
Granular, downloadable market models (region-by-region, chemistry-by-chemistry, application-by-application) and scenario variants.
-
Supplier scorecards with capability assessments, capacity maps, and strategic posture analysis for the leading firms and emerging challengers.
-
Cost and margin sensitivity tools tied to feedstock pricing and transport amendments, enabling margin-preservation simulations.
-
Regulatory compliance playbooks addressing region-specific restrictions and certification pathways.
-
Commercial playbooks for pricing, co-development, and channel strategy tailored to resin grade and end-market dynamics.
-
M&A and partnership screening frameworks to identify high-value targets and integration pathways.
How to Use This Intelligence in 90 Days
-
Week 1–4: Validate procurement exposures and run feedstock sensitivity scenarios using the model provided in the report.
-
Week 5–8: Align R&D and commercial teams on prioritized product tiers and initiate fast-track reformulation where regulatory risk is high.
-
Week 9–12: Engage potential manufacturing partners for tolling or regional supply, and scope targeted M&A or JV opportunities informed by our supplier scorecards.
Closing — Why PW Consulting’s Analysis Matters
Decisions made in 2026 will determine who captures the premium growth in silicone resins through the next decade. This preview highlights the structural growth, regulatory complexity, and competitive dynamics that executives must factor into capital, product, and commercial plans. PW Consulting’s full study couples these strategic insights with transaction-ready models and operational playbooks—tools designed to move leadership from intent to impact without losing optionality in a market defined by both technical nuance and regulatory change.
For the complete dataset, segmented forecasts, and executable recommendations, access the full report and interactive models on our publication page.
For detailed analysis of this topic, please visit the official page: Silicone Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


