



PW Consulting Forecast: Automated Ophthalmic Perimeters Market to Reach USD 545.34 Million by 2032

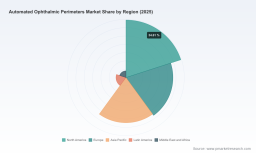
PW Consulting Strategic Preview: Automated Ophthalmic Perimeters Market — What 2026 Decision‑Makers Need to Know
PW Consulting’s latest market intelligence on Automated Ophthalmic Perimeters delivers the forward-looking, decision‑grade perspective that device manufacturers, hospital groups, diagnostic chains, private equity investors and public health planners will use to shape 2026 priorities. Anchored on a 2025 base year and a historical view (2020–2025), our forecast runs through 2032. The market shows steady expansion from the mid‑2020s and is projected to grow at a compound annual growth rate (CAGR) of 5.31% through the forecast horizon, reflecting both hardware refresh cycles and pockets of disruptive product innovation. Market concentration is meaningful: the top three vendors account for roughly 58% of market value, and the top five capture about 72%, signalling a market where incumbency and brand trust still matter, but where differentiated technology can move share.
Automated Ophthalmic Perimeters Market
Top‑level trajectory and why it matters in 2026
-
Steady, investable growth: The global market has expanded consistently in the early 2020s and continues to offer a low‑to‑mid single‑digit growth runway. For capital equipment manufacturers, this profile favours strategic investments that prioritize margin preservation, selective feature innovation, and after‑sales services rather than large volume gambles.
Automated Ophthalmic Perimeters Market -
Technology as the principal growth lever: Adoption of integrated imaging, AI‑driven progression analytics, retinal‑tracking objective perimetry, and VR/portable testing formats is accelerating. These innovations improve throughput, diagnostic confidence and patient experience — three levers that justify premium pricing and recurring software service models.
Automated Ophthalmic Perimeters Market -
Reimbursement and hospital capital behaviour: Existing CPT codes continue to underwrite automated perimetry activity in major markets, and prevailing payer economics support hospital investment in perimeter systems when bundled with workflow gains or clear diagnostic advantages. PW Consulting’s modelling incorporates real‑world fee structures and typical hospital CapEx cycles to estimate adoption timing across buyer types.
Dynamics shaping procurement and R&D choices
-
Clinical demand drivers: Demographic ageing and rising awareness of glaucoma and retinal disease screening sustain baseline demand. Beyond prevalence, diagnostic pathway changes — earlier imaging, combined structural‑functional assessment and telemonitoring — determine which device features become “must‑have” versus “nice‑to‑have.”
-
Regulatory and commercial inflection points: Objective perimetry platforms that combine retinal tracking with automated analysis have reached major regulatory milestones, removing a prior barrier to broad adoption. For product teams, a regulatory‑first development strategy is increasingly table stakes in high‑value markets.
-
Workflow and throughput economics: Faster testing protocols and binocular or virtual approaches reduce technician time and increase daily test capacity — directly improving ROI for hospitals and large clinic groups. Vendors that can demonstrate validated time‑savings and seamless EMR integration will gain procurement leverage.
-
Service and software monetization: As hardware commoditization intensifies, recurring revenue from analytics, progression monitoring subscriptions, and remote support becomes a critical margin driver. Contract structures aligning price to utilization or outcomes are emerging as competitive differentiators.
Competitive landscape — incumbents, challengers and strategy cues
The market remains anchored by several established medtech firms that combine brand recognition with entrenched installed bases. At the same time, focused innovators are introducing feature sets that materially change clinical workflows. Key strategic takeaways from vendor positioning:
-
Carl Zeiss Meditec AG — Zeiss retains a leadership role through an established platform that is broadly accepted as a clinical standard for glaucoma management. For buyers, Zeiss’s ecosystem approach (device + analytics + service) is a low‑risk choice; for competitors, displacing such a platform requires demonstrable, peer‑validated clinical advantage or significant TCO benefits.
-
Haag‑Streit AG — With systems that support both static and kinetic perimetry and a reputation for robust clinical analytics, Haag‑Streit competes on clinical depth. Their focus suits specialty ophthalmic centres that require broad diagnostic capability.
-
Topcon Corporation — Topcon’s emphasis on speed and workflow (notably faster testing protocols) makes it attractive to high‑volume clinics and integrated eye care chains. Vendors targeting hospitals should expect procurement panels to prioritise validated throughput improvements.
-
Konan Medical — Regulatory wins for objective perimetry (CE Mark under MDR and earlier FDA 510(k) clearance) mark a potential turning point. Objective measurement with retinal tracking materially reduces patient‑dependence of tests; this technology is a strategic priority for fleets pursuing telemonitoring and decentralised diagnostics.
-
Centervue (iCare) and Optopol — These vendors illustrate two viable strategies: integration of active retinal imaging to combine structural and functional assessments, and competitive pricing with modern software, respectively. Both approaches underpin viable plays in mid‑market practices and emerging geographies.
-
Smaller innovators (VR/portable players) — Virtual and portable perimeter solutions address point‑of‑care and home monitoring use cases. They are particularly relevant to telehealth strategies and cross‑sell opportunities within primary care networks.
What the full PW Consulting report delivers (practical contents)
-
Proven market sizing and multi‑scenario forecasts (2026–2032) aligned to typical procurement cycles and product replacement curves.
-
Vendor scorecards with strategic positioning, go‑to‑market tactics and product roadmaps (qualitative benchmarking to inform partnership or competitive moves).
-
Actionable buyer playbooks for hospitals, clinic chains and diagnostic centers: total cost of ownership frameworks, procurement negotiation levers, and deployment sequencing to maximise utilization.
-
Regulatory and reimbursement mapping for major markets, including practical implications of CPT code coverage and typical fee levels that influence payback periods.
-
Technology adoption timelines and impact assessments for AI analytics, retinal tracking/objective perimetry and VR/portable platforms, enabling prioritised R&D roadmaps.
-
M&A and partnership targets with screening filters tailored for strategic acquirers and financial buyers, plus integration checklists to de‑risk post‑deal value capture.
Immediate strategic recommendations for 2026
-
For manufacturers: prioritize modular architectures that allow field upgrades (software + optional retinal tracking modules). This preserves installed‑base economics while enabling premium add‑ons tied to subscription services.
-
For hospital systems and large clinic groups: align procurement decisions with throughput and interoperability criteria (validated time savings, EMR/DI integration), not just headline device specs. Use pilot deployments to quantify practice‑level ROI before wide rollout.
-
For investors: target companies that combine an established installed base with a credible roadmap to recurring software revenue, or focused innovators with regulatory approvals for objective perimetry and defensible IP.
-
For service providers and software partners: pursue partnerships that embed progression analytics and telemonitoring workflows into existing perimeter platforms — clinical workflows are the path to premium pricing.
How to use this preview in your 2026 planning
Consider this document a strategic map: the market’s steady CAGR and concentrated vendor structure mean that 2026 is a year to sharpen positioning rather than make broad, speculative investments. Use the following practical sequence in your planning cycle:
-
Q1: Run cross‑functional workshops to translate clinical improvements (faster tests, objective metrics, integrated imaging) into procurement requirements and R&D feature backlogs.
-
Q2: Execute focused pilots with vendors demonstrating measurable throughput or diagnostic gains. Capture baseline KPIs and measure delta payback under local reimbursement scenarios (note: typical physician fee schedules influence device payback; industry references place common payment levels in a range that materially affects hospital ROI calculations).
-
Q3–Q4: Convert successful pilots into phased rollouts, or, for manufacturers, pivot commercial models to subscription bundles supported by validated clinical outcomes and remote monitoring services.
Methodology and confidence
PW Consulting’s market model combines historical shipment and revenue analysis (2020–2025), primary interviews with clinicians and procurement leads, vendor financials and product launch schedules, and payer/regulatory mapping. Scenario sensitivity analyses test technology adoption rates and hospital replacement cycles to produce a central forecast and alternate upside/downside cases. The resulting output prioritises strategic insight and executionable recommendations over exhaustive public‑domain datapoints — consistent with the “trusted advisor” approach our clients rely on.
Next steps and where to get the full intelligence
This preview outlines the strategic choices 2026 decision‑makers must make to capture value as the automated perimetry market evolves. To access the full dataset, vendor scorecards, procurement playbooks and the proprietary modelling that supports our forecast, please download the complete Automated Ophthalmic Perimeters Market report from PW Consulting’s report portal or contact your PW Consulting representative. The full report contains the granular annexes and confidential vendor benchmarking that we intentionally withhold from public summaries but that are essential for transaction diligence, product roadmapping and procurement negotiations.
PW Consulting — translating market dynamics into strategic advantage for ophthalmic device markets.
For detailed analysis of this topic, please visit the official page: Automated Ophthalmic Perimeters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


