



PW Consulting: Global LNG Market Forecast to Reach USD 179.0 Billion by 2032

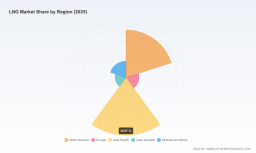
PW Consulting: 2026 LNG Market Brief — Strategic Imperatives for Corporates Navigating a Transitioning Global Supply Chain
PW Consulting today publishes an executive brief of its full LNG Market 2026–2032 report, designed to guide boards, CEOs, CFOs and commercial heads as they make near-term capital allocation and contracting decisions. The global LNG market, measured in USD Billion and using 2025 as the base year, has expanded materially since 2020 and — under our central forecast — resumes steady growth through 2032 at a compound annual growth rate of 4.09%. The market size rose from an index-level baseline in 2020 to USD 135.0 Billion in 2025 and is projected to reach approximately USD 145.3 Billion in 2026, rising toward an estimated USD 179.0 Billion by 2032 under PW Consulting’s base case.
LNG Market
Why this brief matters for 2026 decisions
-
Timing: 2026 is a pivot year. Several project milestones and regulatory resets have altered capacity, offtake dynamics and pricing regimes. Decisions taken this year on long-term contracts, financing structures and portfolio positioning will lock companies into risk exposures that play out across the next investment cycle.
LNG Market -
Market structure: The market displays moderate concentration — the top three players account for roughly half of identifiable market presence while the top five approach three-fifths — creating both system-level stability and asymmetries that can be commercially exploited.
LNG Market -
Price backdrop and feedstock: Henry Hub spot prices averaged roughly USD 3.50/MMBtu in 2026, improving project economics for new liquefaction while constraining near-term upside for merchant sellers; corporates must reconcile capex timing against this cost backdrop.
Key dynamics reshaping supply, demand and policy
-
New project commissioning: 2026 has already seen prominent milestones that recalibrate supply expectations. Strategic entrants reaching first production and multi-decade offtake deals signed in the past 12 months materially change counterparty risk profiles and vessel and regas capacity planning.
-
Regulatory openings and policy swing: Policy shifts since 2025 — including the removal of certain export-permit pauses and domestic subsidy rollbacks — are creating new commercial pathways while also introducing political and legal uncertainty around decarbonization incentives. Firms must stress-test contractual models against both expanded export allowances and potential shifts in domestic support for clean technologies.
-
Capital discipline and financing: Lenders are increasingly integrating transition risks into lending covenants, even as large energy firms maintain the balance-sheet capacity to advance large-scale projects. Expect a premium for low-carbon, low-leakage supply chains and for counterparties with traceable commitments.
-
Volatility pockets: Even as the aggregate market grows at ~4.1% CAGR across our forecast window, the trajectory includes episodic contractions and rebounds; corporates should avoid linear assumptions when modeling utilization and cashflow scenarios.
Competitive landscape — what the leading firms signal for partners and rivals
The universe of major producers and trading houses continues to define market norms. PW Consulting’s qualitative analysis of project strategies and recent company activity identifies three practical competitive archetypes and their implications for corporates seeking exposure or partnership:
-
Integrated incumbents focused on portfolio and trading advantage — companies with global trading platforms and upstream-to-delivery footprints are using cargo flexibility and structured trading to optimize margins and de-risk merchant exposure. Their strengths lie in portfolio optimization and offtake flexibility; their vulnerability is capital intensity and exposure to policy shifts that affect demand for fossil fuels.
-
Greenfield project developers and regional champions — developers bringing new liquefaction trains or regionally focused capacity are locking in long-term offtake and EPC arrangements to secure financing. When developers achieve first gas or first cargo milestones, counterparty confidence shifts quickly; these events commoditize capacity and reduce scarcity premia.
-
Large national and supermajor actors — those with integrated upstream assets and sovereign backing leverage scale to secure long-dated contracts and preferred access to feedstock. Their playbooks emphasize strategic partnerships and geopolitical hedging, increasing pressure on independent offtakers to secure diversified counterparties.
Notable recent developments that substantiate these archetypes include first production at major projects and large-volume long-term supply agreements signed in early 2026, as well as publicized record production and export figures released by leading exporters in late 2025. These events materially affect vessel scheduling, regas utilization and trading liquidity.
Practical contents of the full PW Consulting report (what you will find inside)
Our full report is constructed to be decision-ready. It is organized around applied modules that executives use directly in 2026 planning cycles:
-
Scenario-led forecasts — multiple supply/demand scenarios (policy shock, capital strike, accelerated decarbonization) with sensitivity matrices for price, utilization and cashflow.
-
Investment and commercial playbooks — decision trees for greenfield versus brownfield investment, contracting templates (tolling, FOB, DES, delegated shipping), and negotiation levers for offtake duration and flexibility.
-
Risk heatmaps and counterparty assessments — practical due-diligence checklists, counterparty credit templates and stress-test outputs calibrated to the policy and pricing shifts observed since 2025.
-
Capex and project execution diagnostics — tools to align EPC milestones with financing tranches, and contingency modelling for supply chain disruptions and commodity price swings.
-
Trading and portfolio optimization modules — guidance on cargo arbitrage, blended pricing strategies and how to use trading desks for volatility capture without increasing structural exposure.
-
Decarbonization pathways — operational and contractual steps to reduce lifecycle emissions, including measurement frameworks that align with lender and buyer expectations.
How corporates should use this brief now
-
Revisit contracting timelines: Given newly commissioned capacity and the policy environment, delay or acceleration of final investment decisions materially change payback expectations. Use the scenario templates to quantify the value of a 6–18 month shift in contract start dates.
-
Stress-test offtake portfolios: Layer flexibility clauses and seek volume buckets that enable participation in project upside while capping downside in low-price states.
-
Refine counterparty selection: Prefer counterparties with demonstrable delivery track records and transparent emissions measurement; the market’s concentration means counterparty selection now carries portfolio-level consequences.
-
Align financing with policy risk: Structure financing tranches to reflect regulatory milestones and maintain covenant buffers for policy-driven revenue shifts (for example, subsidy rollbacks or legal challenges to state climate laws).
What we are withholding here — where to go for full transparency
Consistent with PW Consulting’s “brief-first” release strategy, this public summary presents our strategic conclusions, market-level sizing and the analytical frameworks that matter for 2026 decisions. To preserve the value of primary analyses and to ensure clients can act on granular signals, detailed sub-segment breakdowns (regional, type and application splits), counterparty-level exposure tables, detailed project-by-project capacity ramps and proprietary scenario spreadsheets are only available in the full report and client portal. These gated assets include the precise segmentation data that underpin the forecasts outlined above.
Final perspective
The LNG market in 2026 sits at an inflection: macro growth continues at a moderate CAGR of roughly 4.09% over our forecast window, but the distribution of opportunity and risk has shifted. Project milestones and large offtake agreements completed in late 2025 and early 2026 alter both the commercial landscape and the tactical moves available to corporates. Price signals are muted by moderate feedstock costs in 2026, while policy and trade developments introduce non-linear tail risks. Smart leadership will treat 2026 as a year to secure strategic optionality — negotiating contracts, capital plans and partnerships that preserve upside while minimizing embedded policy and market risk.
Accessing the full report
For boards and investment committees preparing decisions this year, PW Consulting’s full LNG Market 2026–2032 report is a practical toolkit: it combines executable contracting language, scenario models and a companion database of project-level milestones. To request the complete report or to arrange a briefing with PW Consulting’s industry partners and lead analysts, visit our report page or contact your PW Consulting representative. The gated report contains the detailed regional and application-level data, counterparty matrices and downloadable modelling assets that underpin the insights summarized here.
— PW Consulting, Senior Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: LNG Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


