



PW Consulting Predicts 4.85% CAGR for Coal Tar Pitch Market Through 2032

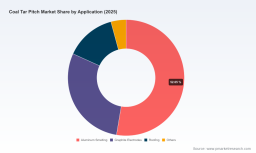
Coal Tar Pitch Market 2026 Strategic Outlook — PW Consulting Preview
Executive snapshot
PW Consulting’s latest market study on the Coal Tar Pitch (CTP) market delivers a forward-looking, actionable intelligence package designed for decision-makers preparing capital allocation, procurement strategy, and regulatory compliance planning in 2026. The market we modelled grew from approximately USD 1,765.2 Million in 2020 to USD 2,185.5 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 4.85% through our 2026–2032 horizon, reaching an estimated USD 3,044.1 Million by 2032. This trajectory reflects a mix of demand resilience in core industrial applications and supply-side constraints that will shape competitive dynamics over the coming investment cycle.
Coal Tar Pitch Market
Why this preview matters for 2026 corporate strategy
-
Capital allocation and plant planning: Our forecast and scenario analysis enable CFOs and plant managers to align capex timing with expected demand waves while accounting for lead times in distillation and processing capacity.
Coal Tar Pitch Market -
Procurement and supply security: With feedstock volatility and structural shifts in steelmaking technologies constraining coal-tar availability, procurement teams must reassess contract structures, build optionality, and prioritize long-term offtake or joint-venture models.
Coal Tar Pitch Market -
Regulatory and product compliance: Tightened PAH-focused regulation across multiple jurisdictions is driving incremental compliance costs and grade substitution opportunities; legal and EHS leaders need a pragmatic compliance roadmap to avoid production disruption.
Key market drivers and dynamics
-
End-market fundamentals: Demand from aluminum smelting, electrode manufacture and other industrial applications provides a stable volume base, while incremental demand from specialty graphite and battery precursor markets appears as a new growth vector. These demand anchors underpin the steady CAGR we project to 2032.
-
Feedstock and supply-side constraints: Volatility in coal tar feedstock availability—compounded by shifts toward electric-arc-furnace (EAF) steelmaking and periodic refinery/asset outages—creates episodic tightness that amplifies price elasticity and creates first-mover advantages for secured suppliers.
-
Regulatory tightening: Authorities in multiple regions continue to reduce allowable polycyclic aromatic hydrocarbon (PAH) thresholds and raise wastewater and emission standards. Examples include longstanding municipal bans in specific U.S. states, proposed state-level PAH limit revisions, and increasingly prescriptive EU REACH restrictions. These regulatory trends force manufacturers to invest in low-PAH grades, emissions controls, and new testing/certification pathways.
-
Consolidation and concentration: Market concentration remains material—our analysis shows a high share of supply captured by the top players—leading to differentiated bargaining power, regional hubs of optimized production, and selective greenfield/ brownfield investment driven by feedstock access and permitability.
Competition — what leading players are doing
Industry participants are pursuing differentiated strategies across capacity, integration, and product mix. The landscape combines legacy integrated producers, regional specialists, and vertically integrated chemical groups that can flex between pitch and downstream carbon markets.
-
Koppers Holdings Inc. (Pittsburgh, PA, USA) continues to leverage integrated coal tar distillation capabilities to supply binder grades for carbon anodes and graphite electrodes. Its integrated footprint, customer relationships with aluminum and EAF steel makers, and technology experience in pitch chemistry provide a competitive moat for supply contracts that value reliability and technical support.
-
Rain Carbon Inc. (Stamford, CT, USA) is expanding capacity selectively to capture growth in graphite and aluminum-bound demand. A notable development is its announcement in early 2025 of a new distillation and pitch-processing facility in Andhra Pradesh, India—an initial phase aimed at capturing regional graphite/battery and aluminum markets. Strategic greenfield moves like this are indicative of portfolio rebalancing toward higher-growth corridors.
-
Himadri Speciality Chemical Ltd. (Kolkata, India) operates at scale with a highly integrated model and has recently demonstrated commercial flexibility through new export corridors. In late 2025 Himadri executed a milestone export of liquid coal tar pitch via a major port terminal, signalling its intent to compete in maritime export markets and to serve regional supply deficits.
-
Deza, a.s. (Czech Republic) and comparable European producers emphasise product quality and regulatory compliance, offering binder and impregnating grades tuned for carbon and specialty applications. Their positioning focuses on low-PAH offerings and technical support for high-value downstream applications.
-
Shree Shyam Chemicals (Bhilai, India) and regional manufacturers continue to supply industrial-grade pitch, often competing on logistics flexibility and service to domestic aluminum, graphite and chemical sectors.
Recent market activity that matters for 2026 decisions
-
Capacity expansion announcements by major distillers—particularly in strategic corridors—are signposts that competition for feedstock and port access will intensify. New facilities with initial targeted phases focused on graphite, battery and aluminum markets will alter regional supply flows and provide alternatives to incumbent suppliers.
-
Commercial agreements and MoUs with large aluminum producers signal heightened interest in securing liquid pitch supply chains. Non-binding arrangements often precede firm long-term contracts that can shift supply baselines within a 12–24 month window.
-
Export corridor development by established producers has increased trading flexibility; however, it also introduces new logistics and quality-assurance considerations for buyers and distributors.
-
Regulatory actions—state bans, proposed PAH limit revisions and tighter REACH enforcement—are creating gradated demand for compliant, low-PAH grades and for third-party certification services.
Report contents — what the full PW Consulting study delivers
-
Detailed market-sizing and five- and seven-year forecasts (base year 2025; forecast period 2026–2032), including demand-by-application scenarios, price trend modelling, and sensitivity analysis under multiple regulatory and feedstock scenarios.
-
Practical, execution-focused playbooks for procurement teams (contract design, hedging options, strategic inventory sizing) and for operations leaders (grade-switching pathways, retrofitting options, emissions-control capex assessment).
-
Comprehensive competitor coverage: strategic profiles, capacity maps, recent developments, and capability matrices that benchmark technology, product range, and regulatory readiness.
-
Regulatory impact assessment: jurisdictional risk matrices, compliance cost estimates, and migration pathways to lower-PAH products—paired with a compliance investment decision tool.
-
Investment and M&A framework: buy-side diligence checklists, valuation levers specific to pitch assets, and a short-list methodology for target screening.
Strategic recommendations for 2026
-
Secure diversified supply now: For manufacturing and processing businesses, prioritize multi-source, medium-term supply contracts with volume flexibility. Where possible, pursue c. 18–36 month take-or-pay structures that include quality clauses for low-PAH deliverables.
-
Accelerate compliance-grade product development: R&D and product management teams should fast-track low-PAH variants and invest in third-party certification to mitigate market access risks in REACH-aligned jurisdictions and North American states tightening limits.
-
Reassess capex timelines against feedstock scenarios: Given forecasted growth and episodic feedstock constraints, staggered brownfield upgrades or modular processing units can offer better return profiles than large single-phase greenfield projects.
-
Pursue strategic partnerships: Joint ventures with port operators, logistics firms or feedstock suppliers can materially de-risk export-oriented projects and improve margin stability in spot-tightening cycles.
-
Embed regulatory surveillance into procurement and product design: Legal and regulatory teams should be part of supplier selection and product specification decisions to avoid last-minute rework or forced grade transitions.
-
If considering M&A: prioritize assets with secure feedstock linkages, permit-ready low-PAH production capability, and access to key downstream contracts; adjust valuation multiples to reflect compliance capex needs and regional permit timelines.
Methodology and credibility
Our study uses a blended methodology combining bottom-up production and consumption modelling, company-reported capacity and throughput figures, trade-flow analysis, and primary interviews across the value chain. The study’s base year is 2025 and the forecast window extends to 2032; sensitivity scenarios model alternative regulatory and feedstock availability pathways. Market concentration metrics in our analysis illustrate a materially concentrated supplier set, which is an important lens for negotiating contracts and assessing competitive risk.
Next steps — how to use the full PW Consulting study
This briefing has been prepared as a strategic preview to inform 2026 decision-making. The full report contains the granular financial models, regional flow maps, and actionable appendices required to execute the recommended strategies—content that we intentionally reserve for subscribers and report purchasers to protect commercial value and ensure integrity of detailed segmentation. PW Consulting clients and report purchasers will receive model files, supplier scorecards, and a workshop-ready executive playbook tailored to their corporate role (procurement, operations, corporate development, or regulatory affairs).
Call to action
To access the full Coal Tar Pitch Market report, the detailed segmentation datasets, and our interactive forecasting model, visit PW Consulting’s Coal Tar Pitch report page or contact our industry desk to schedule a private briefing. For organizations planning investments or supply-chain adjustments in 2026, an early engagement will materially improve timing, negotiation position, and regulatory-readiness.
For detailed analysis of this topic, please visit the official page: Coal Tar Pitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


