



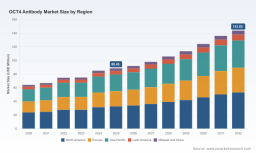
PW Consulting Oct-4 Insight: Global Antibody Market to Rise from USD 88.45 Million in 2025 to USD 143.85 Million by 2032 at a 7.19% CAGR

Oct-4 Antibody Market 2026 Strategic Brief: How PW Consulting’s Oct-4 Antibody Market Report Translates Data into Decisions
PW Consulting today releases the Oct-4 Antibody Market — Oct-4 Antibody Market Research Report (base year 2025). Our analysis synthesizes longitudinal sales data (2020–2025), forward-looking forecasts through 2032, and primary-level competitive intelligence to deliver an actionable strategic playbook for life-science suppliers, institutional purchasers, and investors making critical decisions in 2026. This executive brief highlights the report’s strategic value while preserving the proprietary, segment-level data that we reserve for readers of the full report.
Oct-4 Antibody Market
Market snapshot: scale, trajectory, and concentration (what every board should know)
The Oct-4 antibody market reached approximately USD 88.45 Million in 2025 and exhibits sustained momentum driven by demand in stem cell research, oncology translational studies, and reagent-led discovery workflows. Our forecast projects a compound annual growth rate (CAGR) of 7.19% across the 2026–2032 period, with the market approaching the mid-to-high hundreds of millions of USD by 2032 under the base-case scenario. Concentration metrics indicate a market where leading firms exercise meaningful share — our CR3 and CR5 assessments (48.5% and 62.15%, respectively) point to a moderately consolidated competitive structure that still leaves room for specialized entrants and differentiated product plays.
Oct-4 Antibody Market
Why the 2026 decision window matters
-
Timing of platform investments: With steady growth expected, 2026 is a pivotal year for capital allocation decisions — whether to expand antibody R&D, accelerate recombinant antibody programs, or invest in conjugation and validation services that raise average selling prices and margins.
Oct-4 Antibody Market -
Customer procurement cycles: Academic and translational labs are replacing legacy reagents and accelerating adoption of validated recombinant antibodies. Suppliers who can demonstrate reproducible performance and batch-level data will disproportionately win 2026 purchasing cycles.
-
M&A and partnership windows: Moderate concentration implies acquisition opportunities to consolidate validation capabilities, geographic reach, or portfolio breadth. Strategic acquirers should prioritize targets with defensible validation data, niche application depth (e.g., ChIP-seq grade reagents), or strong channel relationships.
What the report delivers — practical, transaction-ready intelligence
PW Consulting assembled a practitioner-focused toolkit inside this report so that senior management teams can convert market insight into executable plans. Key inclusions:
-
High-resolution revenue model (historical and forecast through 2032) with sensitivity scenarios for adoption, pricing, and raw-material cost volatility.
-
Actionable go-to-market playbooks for monoclonal vs. polyclonal strategy, recombinant engineering, and conjugation services (PE/fluorophore, HRP, biotin) that map to buyer evaluation criteria.
-
Validation and regulatory checklist that operationalizes RUO labeling constraints and outlines how to design claim language and supporting data packages for research users while avoiding diagnostic/clinical use implications.
-
Supply-chain and manufacturing risk matrix that prioritizes contingency options for critical raw materials, host systems, and contract manufacturing relationships.
-
Procurement playbook for large institutional buyers to optimize total cost of ownership via vendor segmentation, qualification workflows, and batch acceptance criteria.
-
Company scorecards and competitive positioning maps, combining capability assessment (e.g., recombinant platforms, ChIP-grade validation) with commercial reach.
Competitive landscape — how incumbent capabilities map to buyer needs
The Oct-4 antibody ecosystem includes global life-science platforms, specialized reagent houses, and emerging regional players. Our qualitative and quantitative assessments emphasize technological differentiation (e.g., recombinant monoclonals, ChIP-seq grade polyclonals), validation depth, citation footprint, and channel strength. Below is a high-level synthesis of competitive positioning for the core players covered in our study.
-
Bio‑Techne / Novus Biologicals (Minneapolis, MN, USA) — Strength: extensive catalog breadth and deep citation presence in stem cell literature. Strategic advantage comes from portfolio depth across formats (monoclonal, polyclonal, conjugated) and strong academic channel relationships. Commercial moves to watch: continued emphasis on reproducibility data and bundle offerings with complementary stem cell reagents.
-
Thermo Fisher Scientific / Invitrogen (Waltham, MA, USA) — Strength: scale, global distribution, and multiple product formats including recombinant clones. Thermo Fisher’s go-to-market benefits suppliers with demanding global procurement standards. Risk/Opportunity: incumbency provides pricing power but invites challengers to exploit niche validation gaps.
-
Cell Signaling Technology (Danvers, MA, USA) — Strength: reputation for high-quality validation and focus on embryonic stem cell and pluripotency markers. Their validation-first positioning allows premium pricing; challenge is scaling breadth without diluting perceived quality.
-
Abcam (Cambridge, UK) — Strength: recombinant monoclonal clones and strong translational research uptake. Abcam’s platform supports rapid clone replacement and catalog rationalization—key in an environment where discontinued SKUs are frequently replaced with alternatives.
-
Proteintech, GeneTex, BioLegend, R&D Systems, Santa Cruz, STEMCELL Technologies, Diagenode, Enzo Life Sciences, Sigma‑Aldrich (Merck), CUSABIO — These firms form a competitive middle where differentiation is delivered through select strengths: validated species cross-reactivity, ChIP/ChIP‑seq grade antibodies, flow cytometry-conjugated reagents, or cost competitive catalog SKUs. Tactical playbooks for these players focus on deepening application-specific claims, publishing targeted validation studies, and strengthening reseller/channel ties.
Recent product and catalog developments — signals for 2026 tactical moves
-
Several vendors updated Oct‑4 listings and validation materials in 2025–2026, including ChIP‑grade annotations and IHC-P validations, which signal an industry shift toward application-specific assurance. Suppliers that publish batch- or lot‑specific validation data gain credibility with translational customers.
-
Product rationalizations and SKU replacements remain common; teams must actively manage catalog migrations to prevent revenue erosion when popular clones are discontinued or reissued under new catalog numbers.
-
All commercial Oct‑4 antibodies are marketed as Research Use Only (RUO) and carry explicit disclaimers; vendors and buyers must align on compliant labeling and messaging to avoid inadvertent clinical claims.
Strategic imperatives for 2026
Based on our forecast and competitive review, PW Consulting recommends five immediate priorities for stakeholders:
-
Prioritize validation transparency: Invest in batch-level validation datasets (WB, ICC/IF, IHC, ChIP where relevant) and publish reproducibility studies to win translational labs and CROs.
-
Differentiate by application depth rather than catalog breadth alone: ChIP‑seq grade or flow-conjugated Oct‑4 reagents command premium positioning and reduce direct price competition.
-
Defend and extend channel partnerships: Institutional contracts and distributor networks remain decisive — secure preferred‑supplier status through performance guarantees and streamlined procurement processes.
-
Design acquisition screens around validation assets and data: Targets with defensible, reproducible data packages and specialized application focus are higher-value and integrate more cleanly into larger platform portfolios.
-
Build SKU‑migration playbooks: Anticipate regulatory-driven or supply-driven SKU changes and proactively communicate replacements with customers to preserve loyalty and minimize revenue loss.
What the full report unlocks (and why you’ll want it)
The public brief above highlights our core findings and recommended actions. The full Oct‑4 Antibody Market report contains the underlying datasets, segment-level forecasts, and company-level scorecards necessary to operationalize the recommendations — including:
-
Granular revenue waterfalls and scenario models by antibody format and application (available only in the full report).
-
Validation matrices mapping antibody clones to peer‑reviewed citations and application performance metrics.
-
Vendor playbooks and negotiation templates for institutional buyers and suppliers preparing 2026 contracts.
-
Detailed M&A screening criteria and integration checklists for potential acquirers.
Closing — pragmatic foresight for a competitive 2026
For leadership teams evaluating allocation of R&D capital, commercial expansion, or M&A activity in 2026, the Oct‑4 antibody market presents both predictable growth and asymmetric opportunity. Steady CAGR and a moderately concentrated supplier base favor disciplined investments in validation, application specialization, and channel strengthening. PW Consulting’s Oct‑4 Antibody Market report converts these market dynamics into transaction-ready guidance and proprietary data—precisely the intelligence leaders need to make defensible decisions in 2026. For access to the full datasets, segmentation breakdowns, and company scorecards, consult the complete report.
For detailed analysis of this topic, please visit the official page: Oct-4 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


