



PW Consulting: Missile Decoy Launcher System Market Poised for 5.51% CAGR Through 2032

Missile Decoy Launcher Systems Market: Strategic Imperatives for 2026 — A PW Consulting Preview
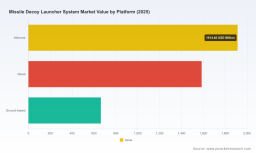
As geopolitical friction, naval modernization programs and evolving missile threats reshape defence procurement priorities, the missile decoy launcher systems market has become a strategic battleground. PW Consulting’s forthcoming Missile Decoy Launcher System Market report (base year 2025, forecast 2026–2032) shows an industry returning to robust, predictable growth — an addressable market of approximately USD 4,163.0 Million in 2025, forecast to grow to roughly USD 6,060.0 Million by 2032 at a compound annual growth rate (CAGR) of 5.51% during the 2026–2032 period. For defense program managers, systems integrators, OEMs and investors planning decisions in 2026, the implications are concrete: time-to-market, modularity, supply-chain security and interoperability will determine winners.
Missile Decoy Launcher System Market
Executive summary — why this market matters in 2026
-
Demand drivers are anchored in naval modernization and allied procurement programs, with soft‑kill countermeasures rising in priority as part of layered ship self‑defence architectures.
Missile Decoy Launcher System Market -
Technology is shifting from legacy expendable dispensers toward trainable, modular launchers and active expendable decoys capable of adaptive responses against coordinated and advanced seekers.
Missile Decoy Launcher System Market -
Market structure shows moderate concentration — the top three suppliers control nearly half the market while the top five approach two‑thirds — creating a competitive environment in which niche technology specialists can capture disproportionate value through integration and services.
Market trajectory and strategic implications
Historical momentum between 2020 and 2025 demonstrates steady expansion driven by fleet upgrade cycles and renewed procurement budgets across NATO and allied navies. The projected rise to roughly USD 6,060.0 Million by 2032 reflects a multi-year replacement and capability enhancement cycle rather than a short-lived spike. For corporate strategists and procurement authorities, this forecastable growth window (CAGR ~5.5%) enables planned investments in capability development, industrial base expansion, and long‑lead material sourcing — provided those investments are calibrated to program timelines and export/regulatory constraints.
Crucially, this is not a volume-only market. Value migration is occurring toward systems that offer trainability, multi-spectral payload compatibility, integration with ship combat systems and through-life support. Companies that can offer demonstrable system-of-systems interoperability, reduced integration risk, and predictable logistics will capture premium share of contracting activity.
Technology and procurement dynamics to watch
-
Trainable, modular launchers: Procurement specifications increasingly favor trainable bases and multi‑payload architecture to counter diverse RF, IR and multi-modal seekers. Systems that can be reprogrammed and reconfigured in the field reduce obsolescence risk and shorten upgrade cycles.
-
Active expendables and offboard decoys: Active decoys that can mimic signatures and manoeuvre to attract advanced seekers are moving from niche to mainstream in high-threat environments. Integration with launcher and shipboard fire-control networks is a critical differentiator.
-
Supply‑chain and materials: High-strength alloys, precision electronics and specialty propellants underpin reliability and performance. Sourcing strategies and supplier diversification are emerging as non‑negotiable risk mitigators.
-
Regulatory and interoperability frameworks: Export controls, bilateral agreements and interoperability standards will shape market access; contractors who can pre-certify solutions for major alliance standards will enjoy competitive advantage.
Competitive landscape — who’s shaping the market and how
The market features established prime contractors and specialized niche suppliers. Several competitive archetypes are apparent:
-
Integrated primes with platform-level influence: Companies such as BAE Systems, Lockheed Martin and L3Harris remain pivotal due to their roles in platform programs and integration responsibilities. Their involvement in established active decoy programmes (e.g., Nulka) provides both technological depth and program leverage.
-
System specialists with naval focus: Firms like Terma, Safran Electronics & Defense, Rheinmetall and Elbit Systems bring purpose-built decoy launcher solutions (trainable launchers, multi-axis systems and multi-ammunition softkill systems). Their products are often chosen for specific vessel classes and modernization blocks.
-
Payload and expendable specialists: Chemring, IrvinGQ and Rafael concentrate on decoy payloads (corner reflectors, chaff/flare, active expendables) and have strong IP in signature management and spectral tradecraft.
-
National/regional providers and integrators: Entities such as Emgepron and emergent entrants (e.g., TEKOM’s new trainable launcher) underline the rising importance of sovereign supply chains and localized industrial participation clauses in procurement.
Recent contract awards and product announcements illustrate these patterns. Collaborative wins for naval decoy control and launching systems reflect consolidation of integration roles across technology partners. Similarly, selection of trainable bases for major ship classes points to a procurement preference for adaptable launchers that can be upgraded over platform life cycles. These transactions and unveilings reinforce the market’s trajectory toward modular, interoperable, and exportable solutions.
Market structure and competitive strategy
With the top three companies accounting for almost half the market and the top five comprising over 60%, the environment is moderately consolidated. That structure creates strategic openings: large primes can consolidate through platform integration and long-term contracts, while mid‑sized specialists can win by owning critical IP (e.g., trainable bases, active decoy electronics) and by becoming indispensable subsystem suppliers to primes. New entrants should evaluate partnerships, certified supplier pathways, or targeted M&A to bypass long lead times to qualification.
Actionable recommendations for 2026 decision‑makers
-
Prioritize modularity and interoperability: When defining RFPs or product roadmaps, require modular interfaces and open architecture to future-proof investments and simplify mid-life upgrades.
-
Invest in integration competence: Winning full-line contracts increasingly depends on demonstrating low-integration-risk solutions. Build or partner for integration proof points with common combat management systems.
-
Secure critical supply chains: Identify long‑lead components (precision electronics, specialty alloys, rocket motors) and create dual-source strategies or local production where regulatory or political risk is material.
-
Design for through‑life value: Offer bundled sustainment, obsolescence management and upgrade packages — customers are willing to pay for reduced total ownership risk.
-
Pursue alliance-aligned certifications: Prioritize interoperability testing against alliance standards and arrange pre‑certification pathing to accelerate procurement approvals in key buyer markets.
-
Scan for high-value niches: Assess opportunities in active expendable development, signature management algorithms and trainable launcher avionics as potential M&A or JV targets.
What PW Consulting’s full report delivers (practical, actionable content)
Our full Missile Decoy Launcher System Market report translates the strategic context above into operational tools for 2026 decision-making. It includes:
-
A validated market model with historic and forecasted demand (2020–2032), sensitivities and scenario analyses that inform procurement timing and investment sizing.
-
Vendor/technology profiles and a supplier capability matrix assessing production capacity, certification readiness, exportability and integration risk.
-
Procurement playbooks and commercial models for prime contractors and subsystem suppliers, including bid/no‑bid frameworks and pricing levers for through-life support offers.
-
Risk matrices for supply chains, regulatory exposures and technology obsolescence, with mitigation checklists tailored to the decoy launcher ecosystem.
-
Go‑to‑market strategies for new entrants and growth plans for incumbents, covering partnership roadmaps, IP strategies and M&A screening criteria.
-
A bank of primary-interview insights and program-level trackers for major naval modernisation programs and competitive contract awards to inform near-term capture plans.
Using the intelligence in 90 days
For senior leaders aiming to convert insight into action within the next quarter, we recommend a three-step plan: (1) run a rapid capability gap assessment against the modularity and integration criteria laid out in our report; (2) validate your supply‑chain exposure against the report’s risk matrices and prioritize mitigations for high‑impact components; (3) initiate targeted partnership discussions (technology or manufacturing) with suppliers identified as strategic matches in the supplier capability matrix. These steps reduce go-to-market risk and position organisations to capture award timelines that will crystallize through 2026.
Conclusion — positioning for durable advantage
The missile decoy launcher systems market presents steady growth and shifting value pools that favor systems-level integrators and specialized technology owners. The near-term imperative for 2026 is clear: move beyond product-centric selling to deliver integrated, upgradeable solutions with resilient supply chains and proven interoperability. PW Consulting’s full report provides the modelling, supplier intelligence and execution playbooks required to turn these imperatives into contracts, partnerships and program wins.
For procurement officers, program directors and corporate strategists seeking a deeper view — including vendor scorecards, procurement trackers and scenario-driven forecasts — PW Consulting’s full report offers the proprietary analysis and operational templates you will need to make calibrated decisions in 2026. Access details are available on PW Consulting’s publications page.
For detailed analysis of this topic, please visit the official page: Missile Decoy Launcher System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


