



PW Consulting Predicts Low‑Powered Electric Motorcycle & Scooter Market to Expand at a 12.15% CAGR

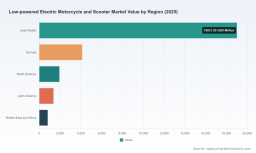
Low Powered Electric Motorcycle And Scooter Market: Strategic Imperatives for 2026
PW Consulting today publishes a forward-looking industry brief accompanying our full Low Powered Electric Motorcycle And Scooter Market report (base year 2025). The market reached a definitive scale in 2025 — and, under our base forecast, is expected to expand at a compound annual growth rate of approximately 12.15% through 2032. This trajectory reshapes competitive dynamics, supplier economics and regulatory risk profiles. The analysis that follows is curated to help boards, corporate strategy teams, private equity investors and mobility operators make informed, immediate decisions in 2026. For full segmented datasets, interactive models and annexes, please refer to the complete report on the PW Consulting site.
Low Powered Electric Motorcycle And Scooter Market
Why 2026 is a Pivotal Inflection Point
-
Cost and component dynamics are shifting the unit economics. A material reduction in battery-pack and critical mineral prices over 2024–2025 has improved margin potential for manufacturers and opened space for new business models (battery ownership, swapping and subscription-based services).
Low Powered Electric Motorcycle And Scooter Market -
Regulatory attention is intensifying. Governments and standards bodies have tightened safety and classification rules for electric two‑wheelers, while internationally recognised frameworks (including vehicle safety regulations and UL safety outlines for vehicle systems) are influencing product design and time-to‑market requirements.
Low Powered Electric Motorcycle And Scooter Market -
Market structure remains neither hyper‑consolidated nor atomistic: a small set of large producers coexists with many regional and specialist players, creating both pressure for scale and opportunities for targeted acquisitions or rapid market entry via partnerships.
-
Urban mobility and logistics economics continue to evolve. The segment that serves personal commuting is still a primary volume driver, but commercial last‑mile use cases are changing product specifications and aftersales needs.
What PW Consulting’s Report Delivers — Practical, Decision‑Ready Tools
-
Forecast Model: A company-calibrated market model (2026–2032) with scenario capabilities (base, upside and downside) that allow executives to stress-test capital allocation and pricing strategies.
-
Cost & Supply Chain Toolkit: Bottom-up supply‑chain cost models for battery pack composition, motor and power electronics that quantify sensitivity to commodity swings and supplier concentration.
-
Competitive Benchmarking: Strategic profiles and capability matrices for the leading OEMs and new entrants, focused on product architecture, go‑to‑market muscle, software/IP and manufacturing flex.
-
Regulatory & Safety Matrix: A consolidated compliance checklist mapped to key markets and product classes, including recommended testing sequence and timeline to certification.
-
Go‑to‑Market Playbooks: Channel, fleet and subscription playbooks with KPIs for deployment pilots, dealer enablement and urban operator partnerships.
-
M&A & Partnership Framework: Rapid screening criteria, valuation levers and integration blueprints for targets that deliver scale, technology or distribution advantages.
-
Operational Templates: Pilot scorecards, warranty economics calculators, battery lifecycle management procedures and a risk heatmap for supply and regulatory shocks.
Key Strategic Implications for Executives in 2026
-
Re‑think battery strategy: With continued downward pressure on pack prices and raw lithium cost volatility, firms must decide between owning battery assets, enabling swap ecosystems, or outsourcing to capture margin without capital strain.
-
Prioritise software and services as a differentiation axis: Connectivity, fleet management and subscription features are shifting value from pure hardware to bundled recurring revenue — a critical factor in valuation and margin expansion.
-
Design for compliance and resilience: Incorporate safety certification pathways and thermal management standards into early stage product development to avoid costly rework and market delays.
-
Localise manufacturing selectively: Prioritise localized assembly or cell sourcing in markets where regulation, import duty structures and logistics materially affect price competitiveness.
-
Tailor product roadmaps to dual demand streams: Maintain a clear product split between high‑volume personal commuting designs and more robust platforms for commercial last‑mile use, with differentiated service propositions.
-
Prepare for consolidation opportunities: Given the market’s mid‑level concentration, strategic M&A and alliances can rapidly improve scale and provide access to distribution or technology that would be expensive to build organically.
Competitive Landscape — How Incumbents and Challengers are Positioning
The competitive map is being redrawn along three axes: scale/cost, software-enabled differentiation and ecosystem plays (battery swapping, aftersales and fleet management). Leading manufacturers and new entrants exemplify these vectors.
-
Large-scale incumbents focus on cost and distribution: Several established OEMs leverage manufacturing scale to defend volume-oriented segments and export markets.
-
Smart, connected challengers push software and services: Vendors with integrated IoT, telematics and battery-swapping approaches are transforming retention economics and recurring revenue potential.
-
Regional specialists and legacy brands pursue premium or heritage positioning: Iconic marques and premium innovators are converting brand equity into electrified portfolios targeted at urban buyers willing to pay for design and performance.
Notable corporate positions reviewed in the report include high-volume manufacturers, IoT‑centric platform players, battery‑swap ecosystem builders, India’s high-growth producers and traditional motorcycle OEMs moving into electric segments. Recent market signals that we have analysed include a mainstream manufacturer’s launch of a new scooter platform in late 2025, and a strategic summit by a notable producer showcasing a full‑size model with a third‑party motor and removable lithium-ion battery. These moves demonstrate both product diversification and continued investment in battery systems and modular platforms.
Operational Playbook — Tactical Actions for 2026
-
Supply chain triage: Run a 60‑day battery and motor supplier stress test, mapping alternate sources and qualification lead times.
-
Rapid pilots: Deploy 3–5 pilot vehicles with integrated telematics and warranty telemetry to generate real-world reliability datasets and unit economics before scaling.
-
Regulatory fast‑lane: Engage early with certification bodies and adopt the UL and national vehicle safety frameworks as project milestones to avoid launch pauses.
-
Dealer & fleet alignment: Reconfigure channel incentives to prioritise battery health, service subscriptions and residual value guarantees that reduce consumer total cost of ownership.
Investor & M&A Lens — What Buyers Should Prioritise
-
Value drivers are shifting: IP in software/telemetry and recurring revenue models command premium multiples relative to pure hardware; battery-ownership and swap revenues are key differentiators.
-
Due diligence focus: Assess supply‑contract resiliency, product certification status, and aftersales economics (warranty claims, battery health metrics) — these factors materially affect post‑deal integration risk.
-
Integration roadmap: Successful consolidation requires rapid harmonisation of SKUs, cross‑platform telematics and unified warranty policies to unlock cost synergies.
How to Use This Report Over 90 Days
-
Day 0–30: Strategic reset — senior leadership review, scenario stress‑tests of forecast model, and supplier concentration mapping.
-
Day 30–60: Tactical execution — launch pilot programmes, commence regulatory certification paths, and begin partner negotiations for battery and software partnerships.
-
Day 60–90: Decision cadence — finalise capex allocations, commit to manufacturing footprints or partnership structures, and shortlist M&A targets if inorganic growth is required.
Concluding Recommendation
For companies operating in, or entering, the low-powered electric motorcycle and scooter market, 2026 is the year to convert optionality into repeatable advantage. The combination of improving battery economics, evolving regulatory expectations and the growing importance of software and service revenues creates a clear playbook: secure resilient supply chains, architect products for certifiability, and build recurring‑revenue service layers that protect margin and increase customer lifetime value.
This briefing is a strategic preview intended to demonstrate our analytical depth and practical orientation. The full PW Consulting report contains the complete market model, segmented demand analyses, company share tables and downloadable templates that underpin the recommendations above. Access the full intelligence pack and the interactive scenario model on PW Consulting’s report page to translate these insights into your 2026 decisions.
For detailed analysis of this topic, please visit the official page: Low Powered Electric Motorcycle And Scooter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


