



PW Consulting: Marine Electric Motor Market to More Than Double to USD 16.42 Billion by 2032 on a 12.25% CAGR

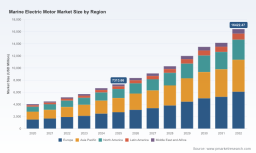
Marine Electric Motor Market — 2026 Strategic Brief: Why this report will shape your electrification decisions
PW Consulting’s latest Marine Electric Motor Market report (base year 2025) synthesizes quantitative projection models, supplier intelligence, technology roadmaps and procurement-grade decision tools to guide boardroom and commercial teams through the critical 2026 planning window. The market is transitioning from niche retrofit projects to mainstream vessel architectures: global demand has more than doubled since 2020 and is projected to expand at a compound annual growth rate of approximately 12.25% into the forecast horizon. On a headline basis, the market grew from around USD 4.1 billion in 2020 to roughly USD 7.3 billion in 2025 and is forecast to exceed USD 8.3 billion in 2026, accelerating toward an estimated USD 16.4 billion by 2032. These dynamics create discrete tactical and strategic inflection points for shipowners, OEMs, suppliers and investors in 2026.
Marine Electric Motor Market
Why this matters to executives in 2026
- Investment timing: With robust near-term growth, capital allocation decisions made in 2026 will determine access to constrained production capacity and the ability to secure preferential OEM engagement.
- Procurement strategy: Rapid product evolution and supply-side concentration on critical raw materials mean single-source procurement or late contracting can significantly raise TCO and delivery risk.
- Product roadmap alignment: From small recreational outboards to high-power inboard systems, technology choices made now (type of motor, magnet technology, integration strategy) will lock in lifecycle efficiency and retrofit flexibility for a decade.
- Regulatory compliance and commercial opportunity: New IMO measures and tightened energy-efficiency planning raise both compliance risk and market demand; early movers capture first-mover commercial advantages in retrofit and newbuild segments.
What the PW Consulting report delivers — practical, decision-ready content
- Proprietary demand model with scenario variants (base, accelerated decarbonization, supply-constrained) and downloadable forecast datasets calibrated to 2020–2025 historicals and extended to 2032.
- Fully auditable financial templates: capex/opex lines, TCO calculators, and payback analyses tailored to propulsion and auxiliary installations across vessel archetypes.
- Supplier scorecards and negotiation playbooks: capability matrices, technology readiness, warranty and service footprints, and recommended commercial terms segmented by buyer profile.
- Supply-chain heatmaps and risk registers: material exposure (magnets, copper), manufacturing bottlenecks, and logistics vectors—plus mitigation options such as strategic inventory, long-term offtake, and co-investment models.
- Technology deep dives: permanent-magnet architectures, synchronous/asynchronous options, novel topologies (including recent trapezoidal stator radial-flux designs), and integration pathways for hybrid-electric systems.
- Case studies and implementation roadmaps: sample retrofit and newbuild programs with stepwise milestones, certification checklists, and expected operational outcomes.
- M&A and partnership screening tools: valuation heuristics for target assessment, strategic fit matrices and playbooks for technology licensing or joint development agreements.
Market dynamics shaping 2026 opportunity
- Regulatory push: The IMO’s 2025–2027 policy package — including a global fuel standard and strengthened SEEMP requirements — creates a deterministic demand tailwind for low- and zero-emission propulsion. These rules enter force in 2027 and are already prompting fleets to accelerate electrification pilots and design-for-electrification in newbuild contracts.
- Raw material and energy supply constraints: The industry faces concentration risk for rare earth elements used in high-power permanent-magnet motors, with primary production concentrated in a small number of jurisdictions. Parallel pressure on copper supply driven by broader electrification increases material cost volatility and project scheduling risk in 2026.
- Technology maturation and product proliferation: Smaller, higher-power-density motor topologies and integrated pod and inboard systems are moving from prototype demonstrations to catalog entries, shortening the commercialisation curve for advanced propulsion units.
- Capital markets and financing: Growing availability of green financing and incentive structures for decarbonization makes financed electrification projects more accessible — but lenders increasingly require robust lifecycle models and demonstrated supplier security before funding.
Competitive landscape — who matters and what to watch
The market is characterized by a mix of large industrial incumbents and agile specialist challengers. Leading global suppliers and a cohort of fast-moving innovators are each carving distinct strategic plays; together they shape OEM sourcing, pricing dynamics and integration choices.
Marine Electric Motor Market
- ABB (Zurich, Switzerland) — Strengths: integrated electric propulsion systems and strong installed base in commercial and specialized vessels. Strategic implication: ABB is a default partner for operators seeking turnkey electrification in larger vessel segments; competitors should anticipate bundled solutions and lifecycle service contracts.
- Siemens (Munich, Germany) — Strengths: high-efficiency motors and integrated drives for heavy maritime and offshore applications. Strategic implication: Siemens will continue to anchor large-scale projects where electrification is paired with complex power management and automation.
- Ingeteam / Indar (Zamudio, Spain) — Strengths: broad power range and proven reliability on merchant and specialized ships. Strategic implication: strong contender for retrofits and mid-to-high power newbuilds where established marine credibility is required.
- TECO-Westinghouse (Round Rock, USA) — Strengths: rugged marine-grade motors and long heritage in shipboard systems. Strategic implication: appeals to fleets prioritizing durability and long service lifecycles, particularly in demanding operating profiles.
- Torqeedo, ePropulsion, Evoy, Elco Motor Yachts — Strengths: nimble innovation in outboards, pod drives and leisure/commercial segments with high-efficiency small- to medium-power units. Strategic implication: these firms are accelerating product cycles for small craft and will influence standards, charging/installation norms and aftersales partnerships.
- WEG, Nidec — Strengths: scale manufacturing capability and adaptable motor platforms. Strategic implication: positioned to provide cost-competitive alternatives and to support OEMs requiring volume production and global service footprints.
Recent product and trade-show activity through 2025–2026 demonstrates two parallel flows: incumbents scaling proven architectures for large vessels, and smaller players accelerating power-density improvements and integration for leisure and short-haul commercial craft. Expect continued alliance activity between system integrators and magnet or inverter specialists as manufacturers seek performance-density gains while managing supply-chain exposure.
Marine Electric Motor Market
Supply-chain and technology risk mitigation
- Diversify magnet sourcing and consider magnetless architectures where lifecycle economics and reliability support substitution. Contractual hedges, consortia purchasing, and strategic equity stakes in upstream suppliers are viable options for materially exposed buyers.
- Lock early delivery slots with high-quality manufacturers for 2026–2027 production windows; consider staggered procurement to manage cashflow and avoid single-point delivery risk.
- Invest in holistic TCO models that incorporate commodity volatility, maintenance intervals and potential regulatory penalties to ensure procurement decisions are resilient across scenarios.
Six strategic recommendations for 2026 decision-makers
- Run fast pilots with clear metrics: short-run retrofit pilots (6–18 months) with pre-agreed data sharing enable suppliers and shipowners to derisk full-scale rollouts.
- Adopt a layered supplier strategy: combine a primary systems partner for integration with two qualified secondary suppliers for critical components and aftersales to manage continuity risk.
- Embed material-hedging clauses into supplier contracts: indexed pricing bands, capped pass-throughs and minimum acceptance quantities reduce exposure to rare earth and copper swings.
- Use PW Consulting’s scenario tools to stress-test fleet electrification pathways against regulatory timelines and fuel-cost scenarios before committing to fleet-wide conversion plans.
- Pursue strategic partnerships with inverter and battery suppliers early to capture integration benefits and improve certification timelines.
- Prioritise modularity in design specifications to enable technology refreshes without full-system replacement, protecting investments against rapid product evolution.
How PW Consulting supports execution
Our Marine Electric Motor Market report bundles the quantitative forecast workbook with actionable deliverables — vendor scorecards, procurement RFx templates, capex/opex calculators and a step-by-step implementation playbook. The deliverables are designed for rapid hand-off to procurement, technical and finance teams so that 2026 programs move from approval to contract award with control over timing, cost and compliance exposure.
For decision-makers planning capital allocation, supplier negotiations or M&A activity this year, the report provides the calibrated market view and negotiation playbooks required to convert the current growth trajectory into durable competitive advantage. To access the full dataset, segmented intelligence and the downloadable toolset, please visit PW Consulting’s Marine Electrification insights page to obtain the complete report and advisory options.
For detailed analysis of this topic, please visit the official page: Marine Electric Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


