



PW Consulting Forecast: Polarizer for OLED Market to Expand at a 10.32% CAGR Through 2032

Polarizer for OLED Market — Strategic Briefing (PW Consulting)
Executive summary
As companies set budgets and strategic priorities for 2026, the polarizer segment for OLED displays sits at a pivotal inflection point. PW Consulting’s forthcoming Polarizer for OLED Market report synthesizes robust quantitative modelling with on-the-ground commercial intelligence to inform executive decisions on product development, capacity allocation, sourcing, and M&A. At the macro level, the OLED polarizer market is recovering and re-accelerating: the global market reached roughly USD 2.19 billion in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of about 10.32% across our 2026–2032 forecast horizon — reaching a materially larger market size by 2032. This growth coexists with accelerating substitution risks from polarizer-less technologies, concentrated supplier structures, and raw-material cost volatility — factors that together make 2026 a make-or-break year for many OEMs and suppliers.
Polarizer for OLED Market
Why this matters for 2026 planning
-
Timing of investment: With a strong near-term growth trajectory, suppliers face trade-offs between capacity expansion and preserving capital for R&D into alternate optical stacks. The opportunity to capture incremental volume in 2026 is real, but so is the risk of overbuilding for a market being reshaped by pol-less innovations.
Polarizer for OLED Market -
Risk management: Raw-material exposure (notably PVA and iodine) creates a dual challenge — cost-pass-through limits with end customers, and supply concentration risks. Companies that lock flexible sourcing arrangements or integrate upstream are positioned to protect margins in 2026.
Polarizer for OLED Market -
Customer alignment: Panel-makers and system OEMs continue to pilot polarizer-free architectures for specific product segments. Suppliers must prioritize cross-functional partnerships with display integrators in 2026 to retain design-ins and avoid being disintermediated.
Market snapshot (high level)
Our model, calibrated to 2020–2025 historical performance and updated through early 2026 intelligence, quantifies a market that has grown steadily from the 2020 base and stands at approximately USD 2.19 billion in 2025. Under the central forecast scenario the market expands at a 10.32% CAGR during 2026–2032, reflecting continued OLED adoption across consumer electronics, large-format displays, and specialized automotive/industrial applications. The market remains moderately concentrated: the top three suppliers account for roughly 68% of market share and the top five approach the mid‑80s percent range — a structure that creates both resilience and vulnerability depending on how quickly substitution trends proceed.
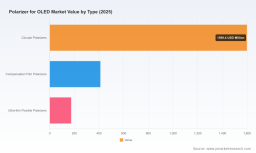
Note: This briefing intentionally omits detailed segmentation figures by region, product type, and application. The full report contains the granular splits, growth rates by segment, and model sensitivities that underpin the scenarios summarized here.
Competitive landscape — strategic implications
Supplier competition is bifurcating into (1) scale-focused incumbents maintaining cost and supply leadership, and (2) specialist innovators pursuing ultra-thin, flexible and high-contrast solutions. Key companies we track exhibit distinct positioning:
-
Nitto Denko Corporation (Japan) — A global leader in ultra-thin polarizers with strong IP and long-standing design relationships in smartphones and premium displays. Nitto’s scale and product breadth make it a de facto partner for panel-makers migrating toward flexible and foldable form factors.
-
Sumitomo Chemical (Japan) — Focused on high-performance PVA-based films for premium applications. Its strengths are in optical performance and material science, positioning it to defend premium price points but leaving it exposed to raw-material inflation unless hedged.
-
LG Chem / Shanjin Optoelectronics (Korea/China) — Retains OLED-specific manufacturing capabilities, particularly for larger-size and flexible panels. Close ties with panel ecosystems give LG Chem strategic leverage for volume commitments and co-development.
-
Samsung SDI (Ace Digitech) (Korea) — Notable for polarizers tailored to foldable and premium OLEDs and for potential strategic moves tied to Samsung’s broader display roadmap. Business positioning is subject to ongoing strategic review, but the company’s integration into a major panel ecosystem is a competitive differentiator.
-
BenQ Materials (Taiwan) — Specialist in bendable circular polarizers, gaining share in the foldable segment. Smaller scale than the largest incumbents but high relevance in fast-growing subsegments.
-
Other regional manufacturers (Japan, China, Taiwan, Korea) — A cadre of medium and smaller players are expanding capacity and capability, often targeting cost-sensitive segments or regional OEMs. Their growing presence contributes to supply competition and to the industry’s ability to respond to regional trade shifts.
Strategic takeaway: market concentration gives incumbents pricing power in the near term but does not insulate them from technology-driven commoditization. Partnerships with panel-makers, selective capex, and focused R&D into flexible/ultra-thin materials will be decisive in 2026.
Technology disruption and demand substitution
Three concurrent trends are reshaping demand:
-
Polarizer-less innovations: Independent market analyses forecast meaningful adoption of polarizer-free OLED modules in certain device classes over the coming decade. Pilots and awards (e.g., recent recognitions for polarizer-free display innovations) indicate commercial momentum that could materially reduce some polarizer volumes, particularly where thickness and cost are paramount.
-
Alternative optical stacks: Approaches such as OLED Transmittance Control Film (OTF) are gaining traction in specific TV applications as a way to optimize cost and thinness. These alternatives do not instantly negate the polarizer market but change the mix of required optical films and the value chain.
-
Segment-specific trajectories: Replacement risk is uneven — some applications (e.g., high-contrast smartphone panels, certain automotive displays) will maintain polarizer demand longer due to optical performance requirements, while others may move faster toward pol-less designs.
Supply chain and input risk
Manufacturing of polarizer films is materially dependent on polyvinyl alcohol (PVA) and iodine for dyeing and performance. Key observations for 2026 planning:
-
Input concentration: The iodine supply chain is concentrated geographically; this creates price volatility and raises secure-supply concerns. Market-level estimates suggest the iodine sector itself will be a multibillion-dollar market in 2026, with major national suppliers accounting for a large share of output.
-
Margin pressure: Historical gross margins for polarizer operations at several Chinese and Taiwanese producers cluster in the mid‑teens to low‑twenties percent. That margin band constrains the ability of suppliers to fully absorb raw-material spikes without contractual or commercial consequences.
-
Trade & tariff dynamics: Policy shifts — such as potential changes to previously tariff-free treatments of polarizers and sub-films — plus ongoing US-China trade tensions create sourcing and competitiveness implications. Companies should stress-test 2026 supplier strategies against alternative tariff scenarios.
Actionable recommendations for 2026
-
Prioritize dual-track investment: allocate a portion of R&D and capex budgets to defend core polarizer technology (ultra-thin, flexible, circular polarizers) while funding targeted pilots for pol-less optical solutions with key panel customers.
-
Hedge raw-material exposure: secure multi-year supply agreements for PVA and iodine, consider strategic inventory buffering, and evaluate upstream investments or alliances to stabilize cost and availability.
-
Forge closer OEM partnerships: negotiate long-term design-in commitments, co-development agreements, and risk-sharing contracts with panel-makers to protect revenue streams as optical architectures evolve.
-
Reassess geographic footprint: model tariff scenarios and re-align production footprints and sourcing to mitigate trade risk while preserving access to growth markets.
-
Targeted M&A and JV playbook: prioritize acquisitions or minority investments that fill capability gaps (e.g., pol-less optics, flexible substrates, or iodine/PVA upstream exposure) and that can be integrated rapidly to capture 2026 market opportunities.
-
Adopt scenario-driven planning: use our three-tier scenarios (conservative, central, rapid substitution) to set contingency budgets and trigger points for capacity adjustments across 2026.
What the PW Consulting report contains (practical deliverables)
-
Market sizing and forecasts (2020–2032) with driver decomposition and sensitivity modelling for pol-less adoption rates and component substitution.
-
Supplier scorecards and cost-to-serve benchmarking for the top global firms, including capability maps and strategic positioning assessments.
-
Supply-chain heatmaps identifying raw-material risk, single points of failure, and mitigation levers for 2026 procurement cycles.
-
Commercial playbooks for OEMs and suppliers: pricing strategies, contract templates for long-term sourcing, and co-development agreement templates.
-
M&A screen: prioritized targets, valuation heuristics, and integration risk checklists to accelerate 2026 deal-making.
-
Regulatory and geopolitical impact analysis with tariff sensitivity scenarios and alternative sourcing strategies.
-
Executive dashboards and negotiation-ready slide decks to support board-level decision-making in 2026.
Closing perspective
2026 represents both an opportunity window and a stress test for players across the polarizer value chain. The macro trajectory is favorable — double-digit CAGR through our forecast period — yet the pace and shape of technology substitution, input volatility, and trade dynamics will determine winners and losers. PW Consulting’s Polarizer for OLED Market report provides the quantitative backbone and commercial playbooks necessary to make high-conviction decisions in 2026 without waiting for perfect foresight.
To access the complete analysis, including the withheld segment-level intelligence and supplier-specific scorecards, please consult the full Polarizer for OLED Market report on our website or contact our industry team for an enterprise briefing.
For detailed analysis of this topic, please visit the official page: Polarizer for OLED Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


