



PW Consulting Forecasts Lead‑Based Rare Earth Alloy Market to Grow at 5.0% CAGR Through 2026–2032

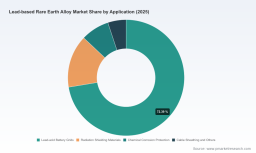
Lead-Based Rare Earth Alloy Market: Strategic Imperatives for 2026 — Preview of PW Consulting’s Market Intelligence
Executive snapshot
As PW Consulting’s lead industry strategist, I present a forward-looking synthesis of our latest Lead Based Rare Earth Alloy Market report — the one-stop strategic playbook designed to inform executive decisions in 2026. The global market has demonstrated steady expansion from our historical baseline (2020–2025) and, with a projected compound annual growth rate (CAGR) of 5.0% over the 2026–2032 forecast window, is expected to move from a 2025 base of USD 306.0 Million to a materially larger market by 2032. This preview outlines the principal dynamics that will shape near-term corporate choices, while reserving our full segment-level intelligence — pricing scenarios, regional and application splits, and detailed financial models — for the full report.
Lead Based Rare Earth Alloy Market
Why this market matters now
Lead-based rare earth alloys remain a niche but strategically important material class. They sit at the intersection of traditional heavy-industry demand (notably battery grids and radiation shielding) and emerging supply-chain sensitivities driven by rare earth feedstock availability and geopolitical shifts. For manufacturers, battery OEMs, materials traders, and private investors, the coming 24 months will be decisive: supply-side constraints, regulatory pressures, and input price volatility will determine who captures margin and who is forced into defensive positions.
Lead Based Rare Earth Alloy Market
Market trajectory and what the headline numbers mean
-
Historical momentum: The market expanded meaningfully across 2020–2025, reflecting both steady end-use demand and incremental substitution of specialty alloys in traditional applications.
Lead Based Rare Earth Alloy Market -
Base year and forecast baseline: With 2025 as our reporting base (USD 306.0 Million), our scenarios model a 5.0% CAGR across 2026–2032 under a central-case macro environment — an outcome consistent with continued industrial demand and moderate expansion of downstream capacity.
-
Strategic implication: The scale and pace of growth are sufficient to justify selective capacity additions and targeted M&A, but not to support indiscriminate expansion — firms must prioritize efficiency, input security, and product differentiation.
Dynamics shaping 2026 decisions
Several high-impact dynamics converge as companies plan capital allocation, sourcing strategies, and product roadmaps for 2026:
-
Upstream feedstock volatility — rare earth concentrate pricing has become a defining input risk. Recent industry-level benchmarks show a sharp quarter-over-quarter increase in negotiated concentrate prices in Q2 2026, reflecting tighter supply and active repositioning by major rare earth producers. That trajectory compresses gross margins for alloy makers that cannot rapidly pass costs through.
-
Policy and reshoring incentives — government financing and loan programs (notably initiatives in 2025 supporting rare earth metallization and separation) are beginning to alter the global supply chain map. These policies reduce concentration risk over the medium term but create transitional winners and losers in 2026 as new capacity and domestic processing lines come online.
-
Regulatory and sustainability pressure — lead toxicity remains a material regulatory constraint. Environmental, health, and transport regulations shape both production cost and market access. Firms that invest in cleaner processing, occupational safety, and traceable supply chains will find premium market access and lower regulatory risk.
Competitive landscape — who matters and why
The market exhibits moderate concentration (CR3 approximately 42.2%; CR5 approximately 58.4%), indicating notable incumbent scale advantages but also room for niche specialists. Our competitive assessment highlights several archetypes:
-
Integrated major producers: Large, vertically integrated firms with upstream lead and rare earth inputs command cost and security advantages. These players typically supply battery-grid markets and industrial alloys through integrated logistics and captive feedstocks.
-
Resource-backed smelters and refiners: Companies with adjacent non-ferrous metals portfolios (zinc, germanium, copper) use cross-commodity synergies to optimize yield and diversify raw material risk, often offering specialized alloy grades for industrial customers.
-
Specialist alloy fabricators: Niche manufacturers focus on higher-value forms — master alloys, wires, foils, and custom purity grades — serving customers with strict metallurgical specs. These players can command margin premiums for product breadth and technical service.
Representative firms we profile in the full report include established integrated producers and specialist fabricators, each with differentiated strengths in feedstock integration, product portfolio, and route-to-market. Our corporate scorecards evaluate capex plans, technological capabilities, balance-sheet resilience, and likely 12–24 month strategies — from capacity ramp-up to selective divestment.
Supply chain and pricing — tactical levers for 2026
Executives must treat feedstock procurement and pricing as front-line strategic issues. Our research shows that the most effective immediate actions include:
-
Negotiate multi-year offtake agreements with price collars to smooth input cost volatility;
-
Pursue vertical tie-ups or minority stakes in upstream concentrate production where feasible to secure allocation;
-
Invest in downstream product differentiation (specialty alloys and forms) to reduce pure commodity exposure and enhance margin capture;
-
Implement incremental efficiency and decarbonization projects that also mitigate regulatory risk related to lead handling.
Sector opportunities and strategic playbook
Based on scenario modeling, we identify four pragmatic strategic plays companies should evaluate in 2026:
-
Secure-to-grow: For firms with balance-sheet capacity, targeted capacity additions near stable power and logistics hubs can capture demand upside while controlling quality and emissions.
-
Niche leadership: Technical specialization (e.g., high-purity master alloys, tailored strip/foil forms) enables margin expansion without heavy capex-led exposure.
-
De-risk and hedge: Financial and physical hedging of rare earth feedstocks, plus contractual customer protections, reduce earnings volatility during input-price shocks.
-
Collaborative resilience: Strategic alliances — joint ventures for separation, recycling partnerships, and shared processing platforms — address both feedstock scarcity and regulatory compliance costs.
What PW Consulting’s full report delivers (practical, actionable assets)
Our research is built for decision-makers. The full report provides:
-
Granular market sizing and a transparent bottom-up model covering 2020–2032 (base year 2025) with scenario toggles to stress-test demand and price assumptions;
-
Segmentation matrices by region, type, and application with defensible assumptions and sensitivity analysis (note: segment tables and exact percentage splits are available in the full report);
-
Company scorecards and an M&A shortlist with an assessment of strategic fit, value creation potential, and integration risks;
-
Supply-chain maps highlighting choke points in concentrate supply, processing capacity, and logistics, plus tactical playbooks for procurement and offtake negotiations;
-
Regulatory and ESG risk register with mitigation options and costed compliance pathways;
-
Go-to-market frameworks for product differentiation, channel strategy, and customer contracting (including a 100-day rapid-response plan for price-shock events).
Risk matrix — what keeps CFOs awake
Key downside risks we model include prolonged rare earth concentrate tightness, accelerated regulatory restrictiveness on lead use, and abrupt demand erosion in legacy applications. Upside risks are faster-than-expected domestic processing capacity additions (reducing supply concentration) and technical breakthroughs that increase rare-earth utilization efficiency in alloys. Each risk is quantified in the full report and mapped to concrete mitigation steps.
Implications for boardroom decisions in 2026
For executives preparing 2026 capital and commercial plans, the strategic takeaway is straightforward: act with precision, not breadth. Prioritize actions that improve feedstock certainty, product margin, and regulatory resilience. Consider the following near-term moves:
-
Revisit capital allocation: prioritize projects with short payback that improve product mix or lower unit costs;
-
Intensify commercial contracting: renegotiate key customer and supplier agreements to include indexation and protection clauses;
-
Pursue targeted partnerships: joint ventures for separation or recycling can materially lower feedstock exposure;
-
Accelerate compliance investments: early adopters of best-practice environmental controls gain market access and avoid costly retrofits.
Final note — why PW Consulting’s intelligence is different
This report blends detailed financial modeling with on-the-ground intelligence from plant-level capacity audits, procurement channel interviews, and patent analysis. We combine quantitative forecasts (5.0% CAGR baseline, full model anchored to 2025 base-year sizing) with qualitative scenario narratives that operational teams can convert into a 90–180 day action plan. Importantly, while this preview highlights the strategic contours, the full report contains the segment-level breakouts, company profiles, and downloadable models you will need to operationalize these insights.
Call to action
Executives considering investments, partnerships, or restructuring in the lead-based rare earth alloy space should request the full PW Consulting report to access: the downloadable financial model, proprietary supply-chain maps, and our prioritized M&A shortlist. Our team is available for tailored briefings and scenario workshops to translate the research into executable 2026 strategies.
For detailed analysis of this topic, please visit the official page: Lead Based Rare Earth Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


