



PW Consulting: Semiconductor Focus Ring Market Set to Expand at 8.22% CAGR Through 2032, Driving Revenues to USD 4,259.12 Million

Semiconductor Focus Ring Market: A Strategic Preview for 2026 Decision-Makers
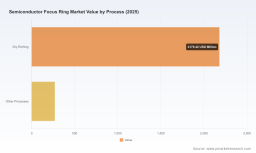
As PW Consulting’s lead industry analyst, I present a concise strategic preview of our new Semiconductor Focus Ring Market research — a practical briefing designed to orient executive decision-making in 2026. The focus ring segment of the semiconductor consumables market is no longer a niche line-item for fab planners: it is a strategic lever affecting yield, tool uptime, supply resiliency and, increasingly, geopolitical risk exposure. Our study uses 2025 as the base year and models the market across 2026–2032. At the macro level, the market is on a sustained growth trajectory (CAGR 8.22% through the forecast), moving from the mid‑2020s base into materially larger absolute scale by the early 2030s. Market concentration remains meaningful (CR3 ≈ 54.2%; CR5 ≈ 68.45%), underlining the importance of supplier selection and qualification strategies.
Semiconductor Focus Ring Market
Why this market matters to corporate strategy in 2026
-
Process scaling and device complexity are elevating the strategic importance of focus rings. As etch chemistries and multilayer stacks multiply, small incremental changes in edge-ring performance translate into measurable wafer-level yield gains or losses. Procurement decisions that were once transactional now carry product roadmap and cost-of-goods implications.
Semiconductor Focus Ring Market -
Supply-chain fragility and raw-material pressures (notably for high‑purity SiC and specialty ceramics) make single‑sourced or just‑in‑time supply models riskier. Longer lead times for specialty ceramics — and the potential for export controls or mineral restrictions — require procurement and operations to build alternative qualification pipelines and buffer strategies.
Semiconductor Focus Ring Market -
Concentration among a relatively small set of technical suppliers means commercial leverage is asymmetric. Strategic sourcing, co-development agreements and multi-year qualification roadmaps are effective levers to secure supply while embedding product differentiation.
Key market signals executives must act on in 2026
-
Adopt qualification windows that align with tool OEM cadence and device development cycles. Our research shows that qualification lead-times remain a critical gating factor; compressing those windows through early technical collaboration yields outsized returns in time-to-production.
-
Build a material‑risk heat map. Focus ring performance is sensitive to material choice (e.g., silicon, CVD/solid SiC, quartz and engineered ceramics). Given rising cost and availability volatility for high‑purity SiC and specialty ceramics, manufacturers should maintain at least one validated alternate material path for each critical etch process.
-
Prioritize suppliers that offer integrated lifecycle services — design-for-etch support, on-tool tuning, failure analytics and predictable spares pipelines. Vendors that combine materials science with field service and analytical feedback reduce time-to-yield and total cost of ownership.
-
Embed export-control and trade policy scenarios into sourcing decisions. Recent measures across allied jurisdictions have demonstrated how regulation can disrupt parts supply. Scenario planning and regional dual-sourcing help avoid single-point failures in the supplier base.
Market dynamics and operational impacts
Our study synthesizes primary interviews, supplier capability audits and process‑level testing data to map the dominant forces shaping the market. Key dynamics include material migration (toward more durable SiC in high-stress etch regimes), the rising tactical importance of nitride-free designs in select nodes, and a bifurcation between high-performance/low-volume specialty rings and commoditized mass‑production variants. These drivers interact with macro inputs — raw material pricing, geopolitical tensions and tighter export controls — to increase the value of proactive supplier management.
Operationally, fabs will face three concrete impacts:
-
Qualification calendars will lengthen unless mitigated by joint-development agreements and standardized test protocols agreed with suppliers.
-
Inventory strategies will need rebalancing — a move away from pure just‑in‑time toward controlled onshore buffer stocks for critical geometries and materials.
-
R&D teams must incorporate consumable packaging and ring‑tool interactions earlier in device and process design to avoid late-stage yield cliffs.
Competitive landscape: who matters and why
The competitive map combines established global materials specialists, CVD SiC pioneers and regional high-volume producers. Suppliers differ not only by material capability (CVD SiC, solid SiC, single‑crystal silicon, engineered ceramics, quartz) but also by scale, vertical integration and service model. The market’s top tier controls a majority share, but regional and niche players are gaining relevance through product innovation and local partnerships.
-
CoorsTek (United States) — Strengths: high‑purity ceramics, deep materials science and engineered solutions for extreme etch environments. Best suited for fabs requiring bespoke, high‑reliability ceramic rings and integrated service models. URL: https://www.coorstek.com
-
Morgan Technical Ceramics (United Kingdom) — Strengths: CVD SiC and high‑purity alumina offerings, long history in high‑temperature and plasma‑resistant components. Strong R&D partnership potential for European and global OEMs. URL: https://www.morgantechnicalceramics.com
-
Tokai Carbon Co., Ltd. (Japan) — Strengths: pioneer status in solid SiC focus rings via proprietary CVD processes; recognized for durability in high-performance etch applications. High technical credibility for advanced nodes. URL: https://www.tokaicarbon.co.jp
-
BC&C (South Korea) — Strengths: mass production capability for polycrystalline silicon rings and recent commercial traction with nitride‑free poly‑Si designs; demonstrates how process innovation can unlock cost and yield advantages at scale. Recent development: order and qualification success with a North American chipmaker (product entering mass supply in early 2025), reinforcing the commercial viability of non-SiC alternatives in targeted use-cases.
-
China-based suppliers (e.g., Semicorex, Semicera, DSTC) — Strengths: rapid scale-up, competitive pricing and an expanding portfolio of CVD SiC and coated graphite solutions. These firms are increasingly relevant for regional fab projects and for buyers seeking alternative sources.
-
Other notable players (Ferrotec, Kyocera, Worldex, Kallex, Daewon, Greene Tweed, etc.) — Each brings differentiated capabilities across ceramic chemistry, silicon processing, quartz fabrications and aftermarket services; selection should be driven by process fit and long‑term supply resilience.
Report deliverables: what executives will find inside
The full research package is purpose‑built for commercial, operations and R&D leaders. It delivers:
-
Proprietary market-sizing and a validated CAGR forecast (8.22% through the 2026–2032 horizon) with scenario analyses that stress-test export control, raw‑material shock and regional capacity build-outs.
-
Supplier capability heat maps and a buyer’s playbook that ranks vendors by technical fit, qualification complexity, and supply‑risk exposure.
-
Actionable procurement frameworks: qualification timelines, test protocols, contractual clauses for supply assurance, and suggested inventory posture by process risk tier.
-
Hands‑on engineering guidance for ring‑tool interaction optimization, on-wafer performance diagnostics, and recommendations for co‑development agreements to accelerate qualification.
-
Supply‑chain risk matrices including material sourcing vulnerability analyses (notably for high‑purity SiC and specialty ceramics) and mitigation levers such as dual-sourcing, onshoring, and inventory hedging.
-
Executive decision templates: CapEx vs. OpEx tradeoffs for in‑house machining vs. outsourced supply, and a procurement scorecard aligned to TTM, yield impact and regulatory exposure.
Practical recommendations for 2026 planning cycles
-
Initiate prioritized supplier qualifications now for every critical etch family. Even when a current supplier is performing, the cost of switching later is high; parallel qualification preserves optionality.
-
Negotiate technical collaboration clauses into key supplier contracts to accelerate shared root‑cause analysis and on‑tool tuning, reducing TTM for node transitions.
-
Establish a materials contingency plan: identify at least one validated alternate material and one alternate geographic source for critical ring types within 12–18 months.
-
Make supply‑resilience a board-level KPI for fabs with advanced node exposure. Track supplier concentration, lead‑time volatility and regulatory risk as part of quarterly risk reviews.
Conclusion and next steps
The focus ring market is maturing from a technical commodity into a strategic component class that links materials science, supply-chain resilience and device economics. For 2026 planning cycles, the essential moves are clear: diversify validated sources, embed supplier partnerships early in process development, and optimize inventory and contractual structures to absorb material and regulatory shocks. Our full report contains the granular segment tables, supplier scorecards and quantitative scenario outputs that will enable executable roadmaps; this preview is intended to surface the critical strategic choices you need to make now to avoid costly delays later.
To access the complete dataset, segment-level breakdowns, supplier profiles and procurement templates, please visit the PW Consulting report page for the Semiconductor Focus Ring Market. The full study is tailored for procurement leads, process R&D managers and corporate strategy teams preparing their 2026–2028 action plans.
For detailed analysis of this topic, please visit the official page: Semiconductor Focus Ring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


