



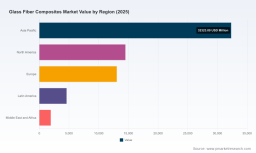
Here are three concise headline options (each uses one data point from the report): 1) PW Consulting: Glass Fiber Composites Market Tops USD 66,450 Million in 2025 2) PW Consulting Forecasts 5.24% CAGR for Glass Fiber Composites Market Through 2032 3) PW Consulting: Asia Pacific Holds USD 32.32 Billion Share of Global Glass Fiber Composites Market

Glass Fiber Composites Market — Strategic Outlook for 2026: Executive Preview
PW Consulting’s latest Glass Fiber Composites Market report (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) equips executives with the forward-looking intelligence required to set priorities in 2026. The global market reached approximately USD 66,450 Million in 2025 and, on our base-case trajectory (CAGR 5.24% over the forecast window), is modeled to approach roughly USD 95,008 Million by 2032. This preview outlines the strategic implications of that trajectory, highlights structural supply‑side shifts and regulatory headwinds, and sketches the decision frameworks we advise firms to adopt as they enter 2026. For full segment-level tables, regional and application breakdowns, and downloadable datasets, please consult the full report on our website.
Glass Fiber Composites Market
Why this matters for 2026 decision-making
- Market momentum: steady mid‑single-digit CAGR implies that 2026 will be a pivotal year to convert runway into scale — not simply to defend volume, but to capture premium value pools that form around specialization and integration.
- Margin pressure vectors: upstream feedstock cost volatility and trade measures are compressing downstream margins in selected supply chains, changing the calculus for pricing, hedging and contract structures.
- Consolidation and concentration: market concentration metrics indicate a market where a relatively small group of global players hold meaningful share — creating both barriers and opportunities for challengers through targeted differentiation.
- Regulatory and sustainability inflection: procurement teams and OEMs increasingly require EPDs and regulatory compliance as purchase qualifiers, so product portfolio and certification strategies will drive commercial access in key accounts.
What the full report delivers (practical, executable content)
- Proprietary market sizing and validated demand models (2020–2032) with scenario toggles that let you stress-test revenue, margin and utilization outcomes against alternate macro and sectoral assumptions.
- Segment playbooks: go‑to‑market blueprints for resin‑type strategies, application prioritization, and regional supply footprint design — with clear path-to-value for premium vs. volume plays (note: segmented numerical tables are available only in the full report).
- Supply chain heat maps: plant networks, lead‑time overlays and import/tariff exposure matrices that highlight single‑point risks in critical corridors and suggest mitigation levers (dual sourcing, forward stocking, contract manufacturing).
- Price and input sensitivity analyses: scenario-linked margin impacts from raw material and freight moves, plus practical hedging and procurement tactics calibrated for 2026 procurement cycles.
- Competitive intelligence dossiers: detailed profiles and capability assessments of the industry’s largest manufacturers, including capacity moves, product portfolios, technical differentiators and likely strategic intents.
- M&A and partnership frameworks: target screening filters, valuation heuristics for specialty vs. commodity assets, and integration playbooks tailored to composite material businesses.
- Regulatory tracker and sustainability roadmap: implications of tariffs, anti‑dumping measures, and certification requirements (e.g., EPD timelines) — and the minimum compliance steps firms must take to avoid commercial exclusion.
Key market themes shaping 2026
- Demand diversification: demand remains anchored by long-cycle industrial applications, but accelerating electrification, renewed wind‑energy capex in selected markets, and infrastructure modernization are shifting the mix toward higher‑value and higher‑specification glass fiber products.
- Upstream reinvestment and capacity rebalancing: the supply base is adding capacity in both commodity E‑glass and specialty fibers. These expansions will relieve some near‑term tightness but will also intensify competition in mid‑cycle volumes unless accompanied by product differentiation.
- Cost and trade volatility: raw material cost upticks and persistent trade measures in important markets are creating regional price differentials and forcing re‑routing and inventory strategies — buyers and suppliers must treat logistics and tariff exposure as strategic rather than tactical issues.
- Premiumization and technical differentiation: specialty glass types and engineered reinforcements (high‑strength fibers, electronic‑grade variants, tailored prepregs) are becoming gatekeepers to premium margins, especially in electronics, aerospace and high‑performance industrial segments.
- Consolidation pressure: concentration metrics show that leading groups control a meaningful share of market flows; this dynamic favors integrated players and strengthens the hand of scale players in long‑term OEM negotiations.
Competitive landscape — strategic observations
- Scale incumbents (examples): large global producers maintain advantaged cost positions and customer access thanks to broad product portfolios and regional plant networks. Their strategic play is to defend volume contracts while selectively moving up the value chain via specialty grades and service offerings.
- Capacity leaders: manufacturers investing in electronic‑grade and high‑performance lines signal an industry bifurcation — commodity E‑glass remains volume-focused, while electronic and specialty fibers are strategic differentiators for margin expansion.
- Specialty and performance players: a subset of firms pursues S‑glass and higher‑specification reinforcements for aerospace, defense and electronics; these firms are prime targets for OEM partnerships and premium pricing, but scale can be a constraint without strategic alliances.
- Pultruders and downstream integrators: companies that convert raw reinforcements into structural profiles and systems are capturing incremental value by offering engineered end‑use solutions; this vertical move is a viable route to insulation from raw material price swings.
- Recent corporate actions: capacity expansions among major producers and investments into electronic‑grade and microfiberglass lines indicate where firms expect growth and margin expansion — signaling competitive intent and future supply availability in those niches.
- Concentration data: the three‑ and five‑firm concentration ratios indicate a market where leading players significantly influence pricing dynamics; nimble challengers can carve profitable niches by focusing on specialty grades, service and technical collaboration with OEMs.
Operational and commercial moves we recommend for 2026
- Prioritize product differentiation: allocate R&D and small‑scale production capacity to develop certified specialty fibers and value‑added reinforcements that meet OEM performance and sustainability specs. This is the most direct route to improving price realization.
- Reshape supply contracts: move from spot purchases toward hybrid contracting (index‑linked with caps/floors and volume collars) and prepay/option structures to stabilize cost of goods sold amid raw material swings.
- Regionalize inventory strategy: create short‑cycle buffers in tariff‑sensitive corridors and align regional assortments to local regulatory and procurement requirements to reduce friction and lead‑time penalties.
- Form industrial partnerships: pursue co‑development agreements with OEMs in high‑growth applications (e.g., electrified transport components, wind‑energy blades, electronic packaging) to lock in long‑term offtake and co‑fund certification cycles.
- Accelerate sustainability certification: secure environmental product declarations and lifecycle data early — procurement teams increasingly use these as exclusionary filters, not just differentiators.
- Identify M&A targets pragmatically: prioritize bolt‑on specialty producers, regional converters with customer ties, or technology platforms that accelerate certification and application engineering.
- Invest in digital OEE: targeted automation and process analytics in glass‑fiber production yield immediate improvements in quality and cost per tonne — pursue rapid pilots across plants early in 2026.
Scenarios and decision triggers (practical lenses for 2026 planning)
- Base case (CAGR ~5.2%): steady demand growth allows staged capacity additions focused on specialty grades. Trigger: sustained utilization above historical norms and stable input cost trendline — accelerate specialty capex.
- Upside case (faster decarbonization & electrification): strong demand pull for higher‑spec fibers. Trigger: multi‑quarter order momentum from OEMs and declared national capex programs — shift quickly from volume to premium playbooks and prioritize long‑term supply agreements.
- Downside case (trade shocks / raw‑material spike): near‑term margin pressure and regional dislocation. Trigger: tariff escalations or sustained feedstock price spikes — implement contingency protocols (price pass‑through, stockpiling, temporary volume rationalization) and expedite contract re‑negotiations.
How PW Consulting supports executive teams
- Rapid diagnostics: 8–12 week supply‑chain stress tests, including tariff exposure and inventory optimization roadmaps.
- Deal advisory: target screening and valuation for specialty glass fiber assets, plus integration playbooks to preserve technical capability and OEM relationships.
- Commercial transformation: pricing, contract design and OEM engagement strategies that shift value capture toward higher‑margin product lines.
- Operational improvement: plant‑level OEE programs and digital pilots tailored to composite reinforcements manufacturing.
Our full Glass Fiber Composites Market report contains the complete datasets, granular segment forecasts, company dashboards and downloadable model files that underpin the insights summarized above. This executive preview intentionally omits detailed segment tables and per‑region/application numeric breakdowns to encourage review of the full analytical package and interactive models on our portal. Visit PW Consulting’s report page to access the complete study, request a briefing, or commission a bespoke scenario run aligned to your 2026 strategic planning calendar.
Glass Fiber Composites Market
For detailed analysis of this topic, please visit the official page: Glass Fiber Composites Market
Glass Fiber Composites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


