



PW Consulting: Low & Medium Capacity Gas Generator Market Tops USD 3,100.0 Million in 2025, Poised for 6.82% CAGR Through 2026–2032

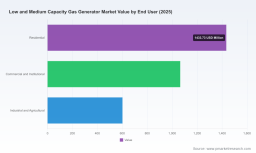
Low and Medium Capacity Gas Generator Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s new market study on Low and Medium Capacity Gas Generators (base year 2025; historical period 2020–2025; forecast 2026–2032) provides a rigorous, practitioner-focused foundation for corporate strategy in 2026. The report synthesizes proprietary modelling and primary interviews to quantify market trajectories, stress-test near-term scenarios and translate opportunities into executable actions. Headline findings: the market expanded materially through the early 2020s (moving from a low‑single‑billion USD base in 2020 to approximately USD 3.10 billion in 2025) and our forecast shows sustained growth through 2032 with a compound annual growth rate (CAGR) of 6.82% across the 2026–2032 horizon, taking the market toward roughly USD 4.9 billion by 2032. These macro figures set the stage for high‑stakes decisions in procurement, R&D prioritization, M&A, and regulatory engagement in 2026.
Low And Medium Capacity Gas Generator Market
Why this report matters in 2026
-
Timing investments under volatility: 2026 will be a pivot year for allocating capital across backup and prime power portfolios. With persistent energy price swings and evolving incentive regimes, firms need precise, market‑calibrated timing to avoid stranded capacity or overpaying for fuel consumption and emissions compliance.
Low And Medium Capacity Gas Generator Market -
Aligning product roadmaps to buyer economics: Buyers increasingly evaluate TCO across lifecycle emissions, fuel flexibility and digital services. The report translates market growth and efficiency trends into concrete product features that win in low and medium capacity segments.
Low And Medium Capacity Gas Generator Market -
M&A and partnership signals: The market shows room for consolidation and strategic alliances. Our analysis identifies the types of targets that create defensible scale quickly—service networks, controls/software providers, and regional manufacturing footprints—informing a 90‑day M&A hit list for 2026.
-
Regulatory and incentive optimization: The interplay between federal funding, tax credit reform and emissions reporting will materially affect project economics. The study models alternative policy scenarios so commercial, financial and regulatory teams can prioritize near‑term actions.
What the report contains — practical, decision‑ready deliverables
-
Bottom‑up market sizing and multi‑scenario forecasts (2026–2032) with sensitivity testing against fuel price and policy shocks.
-
Actionable competitor benchmarking and vendor scorecards that assess product depth, service footprint, channel strategy and technology roadmaps.
-
Go‑to‑market playbooks tailored for OEMs, distributors and large end‑users, including margin maps, contractual structures, and service‑monetization levers.
-
CapEx vs. OpEx decision templates and lifecycle cost models to evaluate new builds, retrofits and hybrids under multiple fuel and carbon pricing regimes.
-
Regulatory impact analyses and a policy tracker that quantifies how recent and pending measures alter project IRRs and incentive capture strategies.
-
Supply‑chain heatmaps, supplier risk assessments, and parts‑availability forecasts designed to support procurement timing and inventory policies.
-
M&A and alliance playbooks including valuation multiplicands used in our model, integration checklists, and example term sheets.
-
Primary interview summaries and several real‑world case studies showing how operators reduced downtime, improved fuel cost management, and monetized ancillary services.
Note: this press briefing intentionally omits detailed segmentation tables and proprietary split‑level data (by region, capacity band and end‑user). Those granular datasets and model files are available in the full report on our site and are provided to clients under license.
Competitive landscape — who to watch and strategic implications
The low and medium capacity gas generator market sits in a moderately concentrated competitive structure (CR3 ~34.2%; CR5 ~47.6%), meaning the top players exert meaningful influence yet mid‑market and regional specialists can still capture growth through focused plays. Our report profiles incumbent OEMs, their strategic orientations and the plausible moves they may make in 2026:
-
Caterpillar Inc. (Irving, Texas; https://www.cat.com) — Strong installed base and dealer network for both backup and continuous applications. Recent product activity (e.g., the October 2025 introduction of the G3512 and expansions in the G3500‑H series) signals renewed focus on continuous and high‑uptime segments. Expect Caterpillar to lean into integrated service contracts and fuel‑efficiency upgrades.
-
Cummins Inc. (Columbus, Indiana; https://www.cummins.com) — A leader in integrated power systems and bi‑fuel capability. Their emphasis on systems optimization positions them well for commercial and industrial buyers seeking turnkey solutions and emissions flexibility.
-
Generac Power Systems (Waukesha, Wisconsin; https://www.generac.com) — Deep penetration in residential and light commercial channels with scalable solutions. Generac’s channel strength and brand recognition make it the vendor of choice where dealer reach and rapid deployment matter.
-
Kohler Co. (Kohler, Wisconsin; https://www.kohler.com) — Known for innovation and reliability in standby and commercial applications; continues to win where operational continuity is prioritized.
-
MTU Onsite Energy (Rolls‑Royce Power Systems) (Friedrichshafen, Germany; https://www.mtu-solutions.com) — Differentiates via sustainability features and engineered medium‑capacity systems for mission‑critical use cases. Their offering is attractive for buyers prioritizing emissions pathways and long‑life performance.
-
Atlas Copco AB (Stockholm, Sweden; https://www.atlascopco.com) — Offers both portable and stationary solutions, with a strong presence in construction and temporary power where mobility and rapid deployment are differentiators.
-
Mitsubishi Heavy Industries Ltd. (Tokyo, Japan; https://www.mhi.com) — Offers a broad technology stack including turbine‑based systems for medium capacity applications; suited to utility‑grade and heavy‑industry buyers.
Strategic implication: incumbents will continue to compete on service, fuel flexibility and digital offerings. Niche specialists that can demonstrate cost‑of‑ownership improvements, smaller footprints, or emissions‑reduction pathways will be acquisition targets or partnership candidates.
Market dynamics, policy and fuel‑price noise — what keeps CFOs awake
Three convergent dynamics should shape 2026 strategy:
-
Fuel price volatility: Henry Hub natural gas prices have shown notable variability. Projections for 2026 settled at a mid‑range level, but monthly swings in early 2026 saw spikes well above the annual average. This creates asymmetric downside risk for fuel‑intensive operating models and changes payback calculations for new deployments.
-
Incentives and regulation: Recent policy actions—federal funding for high‑efficiency generator technologies, the broad impacts of tax‑credit reform implemented in mid‑2025, and potential changes to greenhouse gas reporting—are recalibrating project economics and compliance obligations. These shifts create opening windows for capex acceleration, but also raise documentation and audit requirements that must be built into procurement and financing structures.
-
Service and parts availability: As systems become more software‑enabled, aftermarket service and remote diagnostics are emerging as the primary value capture channel. Firms that invest in service networks and spare‑parts resilience will reduce churn and protect margins.
Practical recommendations for 2026
-
Run at least three funded scenarios for each major project: base case, high‑fuel‑price, and accelerated‑incentives. Model the full lifecycle (including likely reporting and tax compliance costs).
-
Prioritize fuel‑flexible platforms and efficiency upgrades for projects with operating horizons beyond five years. In many cases, the incremental cost for dual‑fuel capability is accretive to portfolio resilience.
-
Use short, targeted M&A to acquire service networks or control‑software specialists rather than pursuing largescale horizontal consolidation in 2026—this drives faster ROI and reduces integration risk.
-
Establish an internal “policy war‑room” to capture incentives (federal/state tax credits, grants) and to respond to evolving reporting requirements. Early engagement materially improves effective returns and audit readiness.
-
Lock in conditional supply agreements for critical spares and key components to mitigate parts shortages and price spikes—consider consignment models for high‑value spares.
-
Monetize services and digital diagnostics through subscription models that reduce end‑user TCO and create recurring revenue streams.
How PW Consulting supports your 2026 agenda
We translate the study’s insights into execution: bespoke scenario models, due‑diligence support for transactions, go‑to‑market accelerators and procurement playbooks. Clients can license our forecast models, request tailored sensitivity runs, or engage our advisory teams for rapid deployment planning and M&A execution. For teams preparing 2026 budgets and strategic plans, we offer expedited workshops that convert the report’s scenarios into prioritized initiatives and 90‑180 day action plans.
This release is a précis designed to orient decision‑makers. Detailed segmentation by region, capacity band and end‑use, the full set of model files and vendor scorecards are available in the complete PW Consulting report on the Low and Medium Capacity Gas Generator Market. Contact us or visit our report page to access the full intelligence and the underlying datasets that will guide robust, defensible decisions in 2026.
For detailed analysis of this topic, please visit the official page: Low And Medium Capacity Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


