



PW Consulting: Infrared Light Therapy Device Market to Reach USD 616.32 Million by 2032, Growing at a 7.15% CAGR (2026–2032)

Infrared Light Therapy Device Market — Strategic Outlook for 2026
PW Consulting’s new market brief on Infrared Light Therapy Devices equips executives with the evidence and tactical playbook needed to make high-conviction decisions in 2026. Built on a 2025 base year and a seven-year forecast window (2026–2032), the study projects continued expansion at a compounded annual growth rate (CAGR) of 7.15%. After a strong recovery through 2020–2025 (market value reached approximately USD 380 Million in 2025), the market is expected to expand materially through the forecast period, passing the USD 400 Million threshold in 2026 and approaching the mid‑hundreds of millions by 2032. This brief summarizes the report’s strategic value while deliberately reserving granular splits and financials to the full report—intentionally designed to prompt direct engagement with PW Consulting for the complete dataset, models, and vendor scorecards.
Infrared Light Therapy Device Market
Why this analysis matters for 2026 corporate strategy
- Timing of market entry: The sub‑segment growth dynamics and macro trajectory show that 2026 is a decisive year for product launches and regulatory initiatives. Firms that move from prototype to clinical validation now can capture disproportionate share as clinics and health systems scale adoption.
- Regulatory differentiation: FDA 510(k) requirements for Class II devices and the growing emphasis on clear therapeutic indications create barriers that favor players with clinical programs and regulatory experience.
- Reimbursement levers: Existing billing codes and therapy session allowances create a commercialization path for clinic-focused offerings; savvy payor strategies materially improve unit economics.
- Supply‑chain risk and cost structure: High‑power near‑infrared LEDs (especially ~850nm units) are a material portion of device BOM — our sector analysis shows these components can drive 20–30% of BOM — making supplier strategy and cost management a priority.
- Fragmented competitive landscape: Market concentration remains modest, indicating fertile ground for consolidation, partnerships, and white‑label opportunities for medical OEMs and clinical players.
What’s in the PW Consulting report (practical, decision-ready content)
- Executive summary with investment thesis and go/no‑go decision checkpoints for 2026.
- Market sizing and forecast model (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario and sensitivity analysis.
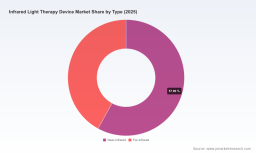
- Segment methodology and assumptions (type, application, and regional frameworks) with downloadable model worksheets—note: detailed segment tables and revenue splits are available only in the full report.
- Commercialization playbooks for direct‑to‑consumer, clinic, and hospital channels including pricing models and reimbursement capture strategies.
- Vendor benchmarking and go‑to‑partner scorecards based on product capability, clinical evidence, regulatory status, distribution strength, and manufacturing readiness.
- Regulatory and reimbursement mapping: 510(k) pathways, applicable CPT codes, and payer engagement templates.
- Supply‑chain risk matrix and supplier negotiation playbook focused on high‑power LED sourcing, BOM optimization, and inventory strategies.
- M&A target shortlist, value‑creation levers, and integration risk checklists for roll‑up strategies in a fragmented market.
- Appendices: clinical evidence compendium, IP landscape snapshot, and raw data export for custom modeling.
Competitive landscape — who’s shaping the market
The market is currently driven by a mix of consumer wellness brands, clinical device manufacturers, and specialty medical laser companies. No single player dominates; the three‑ and five‑firm concentration ratios indicate a market that remains open to entrants with clinical credibility or differentiated go‑to‑market approaches.
Infrared Light Therapy Device Market
- Infraredi (USA) — Focused on portable panels for pain relief and recovery with devices covering the 660–850nm range. Competitive strengths: portability and targeted pain solutions for athlete recovery.
- Mito Red Light (USA) — Consumer and clinical panels with recent product upgrades. Strategic note: launched the MitoPRO+ series (Oct 2025), enhancing near‑infrared output to improve depth of penetration—an important move for clinic‑grade positioning.
- Joovv (USA) — Modular full‑body systems with near‑infrared capability. Strategic note: received FDA Class II clearance for a portable device in June 2025, adding an important regulatory credential for OTC pain indications.
- PlatinumLED Therapy Lights (USA) — High‑power BIOMAX panels combining red and near‑infrared LEDs; credible in both wellness and therapeutic use cases.
- Novaa Lab (USA) — Wearable devices like iTorus aimed at joint and targeted relief; represents the miniaturized/wearable axis of product strategy.
- Celluma (USA) — Clinic‑focused, FDA‑cleared LED devices with an evidence base for acne, aging, and pain; published data (March 2025) showing significant efficacy in arthritis pain reduction is a marketable clinical asset.
- NovoTHOR (UK) — Whole‑body bed systems for clinical recovery; notable for strategic distribution deals with hospital chains (e.g., November 2024), illustrating a hospital‑partnership route to scale.
- THOR Photomedicine (UK) — Portable and clinical near‑infrared lasers targeting wound healing and neurological indications; strengths include clinical depth and laser expertise.
- Multi Radiance Medical (USA) — Combines super‑pulsed laser with infrared LEDs for non‑invasive pain therapy; notable for device hybridization strategies.
- Erchonia (USA) — FDA‑cleared low‑level laser therapy devices with infrared wavelengths; strong clinical positioning in musculoskeletal therapy.
Key market dynamics and tactical implications
- Regulation is a gating factor: Non‑invasive infrared therapy devices are typically Class II and often require 510(k) clearance for pain indications. Firms that design clinical studies aligned to FDA expectations shorten time‑to‑market and reduce recall risk.
- Reimbursement unlocks clinical demand: Existing CPT codes and Medicare/physical‑therapy allowances create a repeatable revenue stream for clinic‑deployed systems; capture requires documented outcomes and clear billing pathways.
- Clinical evidence is becoming table stakes: High‑quality trials and peer‑reviewed results accelerate adoption among clinicians and payors. Recent positive outcomes (e.g., arthritis pain reductions) materially de‑risk hospital conversations.
- Component economics matter: Medical‑grade, high‑power LEDs (notably those near 850nm) are a key cost driver. Locking preferred pricing and secondary suppliers is essential to protect margins and avoid passthrough price shocks.
- Fragmentation = opportunity: With relatively low top‑tier concentration, incumbents and new entrants can grow via differentiation (wearables, whole‑body beds, hybrid laser/LED solutions) or consolidation.
Practical 2026 playbook — five recommended actions for executives
- Finalize your regulatory roadmap now: Decide between OTC, clinic, or hospital‑grade positioning and initiate the 510(k) and documentary programs aligned to that pathway.
- Invest in targeted clinical programs: Prioritize one high‑value indication (e.g., musculoskeletal pain or wound healing) to build a repeatable clinical case and payer argument.
- Secure LED supply and BOM resilience: Negotiate long‑term contracts with LED suppliers, validate secondary sources, and model BOM sensitivity in pricing scenarios.
- Design hybrid go‑to‑market channels: Combine DTC for consumer wellness with clinician partnerships for reimbursement capture; pilot hospital deployments with KOLs to accelerate adoption.
- Prepare for consolidation: Use the relatively low CR3/CR5 concentration to proactively screen acquisition targets—wearables, clinical bed makers, or companies with FDA clearances—to accelerate capability build‑out.
Why purchase the full PW Consulting report
This brief demonstrates the kind of actionable insight embedded in PW Consulting’s full report: robust scenarios, downloadable financial models, granular segmentation (by region, type, and application), vendor financial and product scorecards, go‑to‑market templates, and an M&A shortlist. To preserve the strategic value of our proprietary analysis, we have withheld the detailed numerical splits, regional revenue tables, and vendor revenue breakdowns from this summary. The full report includes those items plus Excel‑ready models you can drop into your planning cycle.
Infrared Light Therapy Device Market
For product teams, regulatory leads, corporate development groups, and investors planning activity in 2026, the full PW Consulting Infrared Light Therapy Device Market report is designed to reduce execution risk, sharpen strategic choices, and shorten time to market. Contact PW Consulting to obtain the complete dataset, vendor dossiers, and our 90‑day implementation roadmap.
For detailed analysis of this topic, please visit the official page: Infrared Light Therapy Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


