



PW Consulting Forecasts 3.8% CAGR for TDI 80/20 Market (2026–2032) in New Market Insights Report

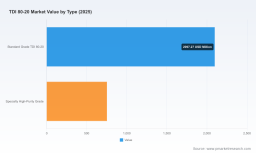
TDI 80/20 Market — TDI 80/20: Strategic Imperatives for 2026 Decision‑Makers (TDI 80/20 Market — TDI 80/20 Market Report, TDI 80/20 Market — TDI 80/20 Market Research)
Executive summary
PW Consulting’s TDI 80/20 Market — TDI 80/20 Market Report (base year 2025; historical window 2020–2025; forecast period 2026–2032) delivers a focused, decision‑grade playbook for corporate strategy, capital allocation, and procurement optimization in the global TDI 80/20 value chain. The market is valued at approximately USD 2,850 million in 2025 and, under our central scenario, grows at a compound annual growth rate (CAGR) of 3.8% to reach roughly USD 3,700 million by 2032. The near‑term profile includes a modest post‑2025 rebalancing before recovery into the late 2020s driven by capacity additions, energy and feedstock volatility, and regulatory pressure.
TDI 80/20 Market
Why this report matters for 2026 planning
-
Actionable timing: Our cross‑check of recent capacity moves, modernization programs and trade policy shifts identifies specific windows in 2026 when sourcing, hedging and investment decisions will capture outsized value — particularly for foam converters, CASE formulators and upstream feedstock integrators.
TDI 80/20 Market -
Risk triage: We quantify seven operational and market risks (feedstock cost shocks, localized trade barriers, safety/regulatory compliance, concentrated supply, energy transition exposure, technology obsolescence, and logistics bottlenecks) and prioritize mitigation measures that fit typical corporate risk appetites.
TDI 80/20 Market -
Competitive signals: The report synthesizes primary and secondary research on incumbent producers, revealing how recent capacity and efficiency actions reshape regional sourcing dynamics and margin pools in 2026–2028.
Market trajectory — what the headline numbers hide
The headline CAGR of 3.8% to 2032 masks a two‑phase trajectory that should directly influence 2026 decisions. After a near‑term inventory and price adjustment, driven by feedstock volatility and selective capacity startups, the market re‑accelerates as demand for flexible polyurethane foam and other polyurethane segments regain momentum. Importantly, the market concentration is material: the top three producers account for a majority share of capacity, and the top five approach four‑fifths of supply — a structural factor that amplifies the impact of individual producer investments and outages on global availability and pricing.
Primary demand and cost drivers (what matters in 2026)
-
Feedstock price dynamics: Toluene price pressure is a direct, measurable input to TDI 80/20 manufacturing economics. Recent northeast Asia price moves—sharp appreciation in the referenced period—translate into single‑digit to double‑digit percentage shifts in cash‑cost curves for exposed producers. Procurement teams must build scenario hedges and supplier scorecards that account for at least three realistic toluene paths over 12–24 months.
-
Energy and decarbonization initiatives: Plant modernizations that capture reaction energy for steam generation materially change unit economics and CO2 intensity. Facilities that lower energy and emissions profiles will enjoy regulatory and off‑taker advantages in markets where downstream purchasers are imposing carbon criteria.
-
Regulatory and occupational safety: TDI remains tightly regulated globally as a respiratory sensitizer. Occupational exposure limits from agencies such as OSHA and guideline values like those from ACGIH create compliance cost floors. Companies must treat occupational safety and REACH‑style chemical management as strategic investments — not just compliance items — because they affect licensing, insurance, and customer acceptance.
-
Trade policy and protectionism: Antidumping and other trade measures can create sudden regional dislocations in supply and pricing. Ongoing duties in major markets are already influencing sourcing decisions and will remain a lever for domestic policy makers through 2026.
Competitive landscape — what recent moves tell us
The competitive map is being redrawn by two simultaneous dynamics: (1) large, integrated capacity additions from resource‑rich incumbents and (2) targeted efficiency investments in legacy plants. Our firm view, based on primary interviews and plant‑level disclosures, is that these moves produce asymmetric advantages for both global exporters and regionally focused suppliers.
-
Large Chinese integrated producers: Recent capacity startups significantly expand global outbound availability from certain Chinese producers. These investments are purpose‑built to serve both domestic foam chains and export markets. For buyers and investors, this means short to medium‑term pricing pressure in exposed corridors but an eventual leveling as trade barriers and freight dynamics reassert themselves.
-
European energy/efficiency upgrades: Select European players have completed modernization projects that reduce energy intensity and emissions per tonne. These projects change competitive positioning by lowering variable cost and improving access to customers with sustainability procurement mandates.
-
Regional producers and market protection: Local producers in major consumption markets retain strategic advantages through proximity, regulatory familiarity and, in several cases, targeted trade defense policies that sustain higher local realizations.
Spotlight: tactical developments to watch in 2026
-
Capacity startups that came online in late 2025 will be the proximate trigger for a short‑term supply cadence reset; monitoring ramp rates is essential for procurement timing.
-
Plant modernizations that recycle reaction heat into steam and other utilities materially reduce energy exposure and CO2 output; these projects are the differentiator for long‑term cost leadership.
-
Trade remedies enacted through 2026 will continue to reallocate supplier‑buyer relationships and may force relocation or reshoring discussions among exposed downstream players.
Implications for 2026 corporate decision‑making
-
Procurement: Move from transactional spot buying to layered coverage: short‑term tactical pools, medium‑term indexed contracts tied to energy/feedstock benchmarks, and strategic supply agreements with performance and service metrics. Include clauses for force majeure, trade duty pass‑throughs, and sustainability attributes.
-
Operations & CAPEX: Prioritize retrofit opportunities that deliver rapid energy and emission paybacks. Greenfield or brownfield investments should be timed to capture windows when incumbent ramp‑ups temporarily depress input prices and labor availability.
-
M&A and JV strategy: Target bolt‑on positions in logistics hubs and feedstock integration rather than only seeking new polymer capacity. Minority stakes with offtake rights in modernized facilities yield outsized optionality while limiting capital exposure.
-
Regulatory & safety governance: Strengthen chemical safety programs and product stewardship capabilities. Compliance excellence is now a commercial differentiator in tender processes where purchasers insist on supplier safety records and low‑emission footprints.
What the PW Consulting TDI 80/20 Market report contains (practical deliverables)
-
Quantitative market model (2020–2032) with base case, upside and downside scenarios, sensitivity runs for feedstock and energy, and a policy shock module designed for CFO stress testing.
-
Supplier scorecards and mapped value chains for strategic sourcing, including plant‑level capability, retrofit potential and logistics latency analysis.
-
Commercial playbooks for buyers, manufacturers and investors — containing contract language templates, risk allocation recommendations and a prioritized list of mitigations for the top seven risks identified.
-
Competitive profiles of the major producers with operational summaries and strategic intent indicators based on announced capacity, modernization projects, and public filings.
-
Regulatory and occupational safety annexes that summarize relevant limits, compliance costs and engagement templates for global regulators and trade authorities.
How PW Consulting’s insight is different
We combine plant‑level engineering economics with procurement scenario planning and regulatory foresight. Rather than merely publishing descriptive segmentation, our report offers executable guidance: when to hedge, when to invest, and which supplier strategies will preserve margin through feedstock and policy cycles. To preserve commercial sensitivity and to encourage a calibration with real operational parameters, detailed region/application split tables and producer‑specific financials are available exclusively in the full report download and interactive dashboard.
Next steps for executives and investors
-
Review the scenario appendix and run the policy‑shock module against your current procurement book to identify exposure timing in 2026.
-
Engage with a short advisory to model a retrofit vs. new‑build decision under the energy and emissions sensitivities set out in the report.
-
Use supplier scorecards to re‑negotiate 12–24 month contracts with clauses for trade remedy pass‑through and sustainability credits.
Accessing the full intelligence
This release frames the strategic implications from PW Consulting’s TDI 80/20 Market — TDI 80/20 Market Report. The full report contains the complete segmentation tables, plant‑level data, producer‑specific metrics and the downloadable market model that drive the recommendations summarized here. For licensing, enterprise access and bespoke advisory services to operationalize these findings in 2026, please visit the TDI 80/20 Market report page or contact our industry desk for a briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: TDI 80/20 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


