



PW Consulting Report: Bone Cement for Spine Market Tops USD 895 Million in 2025

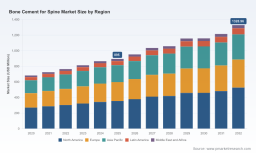
Bone Cement for Spine Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
PW Consulting’s latest market study on bone cement for spine (base year 2025) delivers a compact, decision-ready roadmap for executives planning 2026 actions. At a global level the market sits at roughly USD 895 million in 2025 and — under our base-case assumptions — is forecast to grow to more than USD 1.3 billion by 2032, representing a mid-single-digit compound annual growth rate (CAGR). That trajectory is notable for supply-chain sensitivity, technology-led product differentiation (viscosity profiles, antibiotic-loaded formulations, delivery systems), and a reimbursement environment that favors standardized augmentation procedures. This release highlights the strategic takeaways from the full report while intentionally withholding certain granular segment-level figures to preserve the report’s role as a commercial intelligence product.
Bone Cement for Spine Market
Market dynamics shaping 2026 decisions
-
Clinical demand and procedure mix — The clinical drivers behind vertebral augmentation remain robust: an aging population, sustained incidence of osteoporotic and pathological vertebral compression fractures, and a continued preference among interventional spine specialists for minimally invasive stabilization techniques. Device adoption is being influenced as much by operator workflow and injection control as by material properties.
Bone Cement for Spine Market -
Product innovation — Two technical threads dominate supplier investment: controllable viscosity (including ultra-high-viscosity formulations optimized for anterior column support) and adjunct functionality (e.g., antibiotic-loaded PMMA for combined infection risk mitigation). Radio-opacity and working/injection windows are increasingly marketed as clinical differentiators.
Bone Cement for Spine Market -
Regulatory & reimbursement context — PMMA bone cements used in vertebral augmentation remain regulated under established Class II pathways in major jurisdictions, with special controls and sterilization expectations shaping dossier requirements. In the US, common percutaneous vertebral augmentation procedures are covered under established CPT codes that include cavity creation and cement injection with imaging guidance — a practical advantage for adoption but one that still requires payer-level diligence for new product introductions.
-
Quality, sterilization and materials risk — Manufacturers face rigorous sterilization validation expectations (e.g., documented methods, sterility assurance levels, pyrogenicity testing). On the materials front, standard PMMA formulations continue to exceed ISO mechanical baselines, but raw material sourcing and monomer handling present latency risks that must be managed in supplier contracts and manufacturing operations.
What the full PW Consulting report delivers (practical contents)
-
Proprietary market model with transparent assumptions — multi-scenario forecasts covering 2026–2032 and sensitivity testing for key inputs (procedure volumes, pricing erosion, market entry timing).
-
Regulatory playbook — classification mapping, recommended 510(k)/equivalent strategies, essential documentation checklists (including sterility and pyrogenicity pathways) and timings to market in major regions.
-
Reimbursement and coding guide — payer levers, procedural code implications, and hospital-level bundle impacts for percutaneous vertebral augmentation.
-
Clinical evidence compendium — outcome metrics, comparator data for high- vs low-viscosity formulations, and guidance on randomized vs registry-driven evidence programs to support product claims.
-
Commercial playbooks — go-to-market options by tier (incumbent OEM, challenger, start-up), distributor selection criteria, tender playbooks and pricing negotiation frameworks.
-
Supplier & manufacturing checklist — material qualification criteria, sterilization vendor shortlist templates, and inventory resilience strategies for monomer and radiopaque additives.
-
M&A and partnership scanner — prioritized target profiles, valuation sensitivities, and integration risks for bolt-on acquisitions versus co-development alliances.
Competitive landscape — practical implications for 2026
The market is characterized by a mix of large medtech incumbents and specialized suppliers. Global orthopedics and spine players maintain scale advantages through integrated portfolios and distribution networks, while smaller specialists compete on niche innovations and faster regulatory cycles. Key competitive themes we emphasize:
-
Stryker — leverages a spine-focused product suite with high-viscosity and clinically positioned cements; strength lies in integrated sales channels and long-standing trust with interventional spine clinicians.
-
Medtronic — combines legacy vertebral augmentation platforms with established PMMA offerings; regulatory experience and global reach support rapid rollouts of incremental product improvements.
-
Zimmer Biomet — increasingly targeting differentiated clinical niches (e.g., antibiotic-loaded cements) and leveraging orthopedic scale to cross-sell into spine.
-
DePuy Synthes (J&J) — consistent PMMA portfolio compatibility with spine workflows; pricing and procurement relationships with hospitals are core strengths.
-
Heraeus & Tecres — European-origin suppliers that compete on formulation specificity (high-viscosity, radiopacity) and regulatory craft for EU and broader markets.
-
Merit, IZI Medical, Xelite Biomed and others — smaller, nimble players focusing on differentiated delivery systems, RF-modulated cement systems, or recently cleared products to penetrate the US market.
Recent regulatory and product developments underline near-term shifts in competitive positioning: several entrants obtained US clearances in late 2024–2025 and new antibiotic PMMA launches in 2025 signal pockets of rapid product refresh. These moves increase clinical choice and can compress pricing unless matched by demonstrable outcome advantages.
Strategic recommendations for 2026
-
Prioritize clinical differentiation backed by evidence — invest in prospective registries or limited randomized studies that show procedure-time savings, leak reduction, or infection mitigation; these datapoints materially improve contracting outcomes with hospital systems.
-
Pursue regulatory efficiency with sterilization-first design — embed validated sterilization pathways early (including SAL documentation and pyrogen testing) to avoid late-stage delays and to reduce time-to-market risk.
-
Design resilient supply chains — secure secondary suppliers for critical monomers and radiopaque additives and include inventory buffering in commercial contracts to mitigate spikes in demand for vertebral augmentation seasons.
-
Segment go-to-market by hospital archetype — academic centers value clinical data and novel delivery systems; community hospitals prioritize cost, packaging and ease-of-use; tailor pricing and service bundles accordingly.
-
Explore adjacent value propositions — antibiotic-loaded PMMA, combined scaffold/adhesive approaches, or bundled augmentation systems (implant + cement) can unlock premium positioning if supported by clinical benefit.
-
Prepare for consolidation plays — use 2026 to identify bolt-on targets that provide formulation IP, regulatory dossiers, or regional distribution as part of defensible share gain strategies.
90–120 day tactical plan for executive teams
-
Complete a portfolio stress test: map each SKU against regulatory readiness, sterilization validation, and reimbursement exposure.
-
Kick off a focused registry protocol with 6–12 month interim endpoints to build hospital adoption cases.
-
Negotiate conditional supply agreements with secondary monomer suppliers and establish safety stock triggers.
-
Run pricing simulations by hospital archetype and prepare targeted contracting pilots for high-volume systems.
-
Scan for acquisition or partnership targets that close capability or geographic gaps and pre-draft integration playbooks.
Why this PW Consulting report is essential for 2026 planning
Leadership decisions in 2026 will be made at the intersection of clinical value, regulatory readiness and supply resilience. PW Consulting’s report combines a transparent, model-driven forecast with concrete operational tools — regulatory checklists, reimbursement playbooks, supplier templates, and M&A screening frameworks — to accelerate executive decision cycles and reduce execution risk. We surface not only where growth is likely to occur, but which commercial and technical levers move the needle on share and margin.
Next steps and how to access the intelligence
This briefing intentionally highlights the strategic framing, practical levers and competitive moves that will matter in 2026 without reproducing the report’s detailed segment-level tables and targetable numeric splits. For board-ready slides, market model access, or a tailored advisory workshop that maps these insights to your portfolio and risk appetite, contact PW Consulting for the full market study and executive-briefing package.
For detailed analysis of this topic, please visit the official page: Bone Cement for Spine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


