



PW Consulting Forecasts 4.61% CAGR for Residue Hydrodesulfurization Catalyst Market Through 2032

Residue Hydrodesulfurization Catalyst Market: Strategic Imperatives for 2026 Decision-Makers
Executive summary
PW Consulting’s latest Residue Hydrodesulfurization (R-HDS) Catalyst Market report (base year: 2025; historical review: 2020–2025; forecast: 2026–2032) delivers a focused, decision-grade view for executives planning capital allocation, procurement, and technology strategies in the refining and catalyst-supply ecosystem. Our analysis shows a resilient market trajectory — a mid-single-digit compound annual growth rate (CAGR) of 4.61% over the 2026–2032 forecast window — with the market valued at roughly USD 3.9 billion in 2025 and trending toward the mid–single‑billion range by 2032 under the baseline scenario.
Residue Hydrodesulfurization Catalyst Market
Why this matters for 2026 planning cycles
Refiners, catalyst manufacturers, private equity investors and strategy teams will face a confluence of pressures in 2026 that make forward-looking, granular intelligence indispensable. Tighter global ultra‑low sulfur fuel standards continue to underpin demand for high-activity NiMo and CoMo R‑HDS catalysts capable of processing sour and heavy residues. At the same time, raw‑material volatility (notably molybdenum spot swings observed in 2025) and concentrated upstream supply dynamics are creating cost and supply risks that reverberate through margin models, capital project economics, and inventory strategies.
Residue Hydrodesulfurization Catalyst Market
What the report delivers (practical content)
- Market sizing and method notes: transparent build-up from refinery feedstock flows to installed reactor capacities, with sensitivity cases for feedstock quality and regulatory tightening.
- Forward-looking demand scenarios: baseline, accelerated regulation, and softening-refinery cases that enable rapid stress-testing of capital plans and contract structures.
- Value-chain and margin analytics: component cost drivers (including raw material pricing dynamics), manufacturing cost benchmarks, and refinery-level margin impact per incremental HDS performance.
- Technology and product positioning: qualitative and comparative assessments of fixed‑bed, ebullating‑bed and slurry technologies, with decision frameworks for selection based on feedstock, uptime, and downstream quality targets.
- Supply-chain resilience playbook: procurement hedging strategies, supplier qualification matrices, and inventory optimization models calibrated for 2026 procurement cycles.
- Competitive intelligence: concise, business‑relevant profiles of leading catalyst suppliers, recent M&A developments, partnership models, and route-to-market strategies.
- Investment and M&A guidance: deal-readiness checklists, valuation drivers for catalyst technology assets, and integration risk factors for acquirers and targets.
Market structure and competitive dynamics — what we found
The R‑HDS catalyst market displays oligopolistic tendencies with a relatively high degree of concentration among the top suppliers. This concentration translates into differentiated bargaining power across manufacturers and creates distinct strategic options for buyers: long-term supply agreements with incumbents, co-development partnerships for tailored catalyst formulations, or vertical integration in captive catalyst production. Our competitive framework evaluates players on four axes: technological performance (HDS/HDN/HDCCR), feedstock breadth (atmospheric and vacuum residues), manufacturing scale and geographic footprint, and aftermarket service capability (reactivation, monitoring, lifecycle management).
Residue Hydrodesulfurization Catalyst Market
Key industry participants profiled in the report include multinational catalyst and technology houses as well as integrated national producers. Recent transaction activity has accelerated consolidation and capability re‑alignment — notably, a late‑2025 acquisition that materially strengthened a supplier’s position in fixed and ebullated bed resid hydroprocessing. These moves are reshaping commercial negotiation dynamics and creating opportunities for strategic partnerships and bolt‑on acquisitions aimed at complete solution offerings (catalyst + process licensing + aftermarket services).
Raw material and cost pressures — actionable implications
Two cost realities stand out for 2026 procurement and capital planning:
- Metal supply volatility: Molybdenum experienced pronounced spot volatility in 2025, generating margin pressure for formulators who rely on concentrated supply sources. Buyers should assume periodic price shocks remain likely without diversified sourcing or hedging programs.
- Formulation premiums: Standard base‑metal catalyst inputs trade within a defined price band; specialty formulations designed for residue applications command material premiums relative to standard grades. These premiums meaningfully affect lifecycle cost of ownership and should be incorporated into unit economics of upgrade projects.
Regulatory and feedstock dynamics driving technology choice
Regulatory tightening toward ultra‑low sulfur products is the primary structural demand driver for high‑activity R‑HDS catalysts. For 2026 decision-makers this translates into three practical imperatives:
- Prioritize catalyst formulations and reactor technologies that deliver deep desulfurization without catastrophic sacrifice of conversion or catalyst life when processing sour, high‑CCR residues.
- Embed performance‑based contracts and KPIs into supplier engagements to align lifetime cost‑of‑ownership incentives — uptime, cycle life, and regenerator performance matter as much as initial activity ratings.
- Implement feedstock surveillance programs and blending controls to reduce catalyst poisoning risk and optimize regeneration cycles.
Strategic options for 2026 — recommended actions
Based on scenario analysis and supplier assessment, PW Consulting recommends the following high‑impact actions for organizations setting strategy in 2026:
- Procurement and commercial strategy: Move from spot purchases to hybrid contracting — combine shorter indexed supply contracts with strategic buffer stocks and supplier performance incentives. This dampens exposure to metal price spikes and manufacturer lead‑time risk.
- Technology selection: Match reactor choice to long‑term feedstock profile. For refineries expecting sustained heavy/resid inputs, prioritize ebullating and slurry solutions where conversion flexibility and fouling tolerance justify higher capital intensity; for incremental sulfur reduction on lighter residues, advanced fixed‑bed formulations may provide the best return.
- M&A and partnership playbook: For incumbents and new entrants alike, target bolt-on capabilities in aftermarket services (reactivation, monitoring) and catalyst recycling to protect margins and unlock post‑sales revenue streams.
- R&D and product differentiation: Invest in formulations that reduce susceptibility to metal contaminants and that lower hydrogen consumption per unit of sulfur removed — this is a direct lever on refinery operating costs.
- Risk mitigation: Deploy commodity hedging for key input metals and diversify supplier base across geographies to reduce single‑source exposures.
Case study highlight (illustrative)
Refinery X (North Africa, illustrative): by redesigning its procurement and switching to a performance‑tied catalyst contract, the refinery de‑risked molybdenum price exposure and extended catalyst cycle life via a supplier co‑development program — outcomes included improved sulfur removal consistency and smoother capex phasing for a downstream upgrading unit. Details of the model and sensitivity analysis are provided in the full report for replication.
What we are not disclosing here (and why)
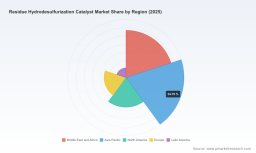
This release is intentionally a strategic “trailer.” While we present the macro market sizing, growth trajectory, and high‑level concentration metrics, the full report contains granular segmentation by region, detailed application and type split values, supplier market shares, pricing forecasts, and downloadable data tables that are indispensable for detailed procurement, investment, and engineering work. We withhold those line‑by‑line figures in this public release to preserve the commercial utility of the full dataset and to ensure readers engage with the complete analysis when executing 2026 strategies.
How to use our intelligence in 2026 decision cycles
Decision-makers should treat the report as both a diagnostic and playbook. Use it to:
- Validate your capex timing — run our regulatory and feedstock scenarios against your project IRR assumptions.
- Design supplier contracts — adopt our recommended KPI structure and renegotiation triggers tied to raw material benchmarks.
- Prioritize R&D agendas and M&A targets — focus on formulations and service capabilities that materially change lifetime economics.
Next steps and access
PW Consulting’s Residue Hydrodesulfurization Catalyst Market report is designed to be immediately actionable for 2026 planning. The full report includes the datasets, scorecards, and implementation templates referenced in this announcement. For access to the complete segmentation, company scorecards, forecast tables and downloadable models, please visit the report landing page or contact our market intelligence desk to schedule a briefing tailored to your organization’s priorities.
PW Consulting — helping clients convert complex market dynamics into executable advantage as they navigate the 2026 planning horizon and beyond.
For detailed analysis of this topic, please visit the official page: Residue Hydrodesulfurization Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


