



PW Consulting Report: Turbine Discs Broaching Machines Market Poised for 6.0% CAGR Through 2032

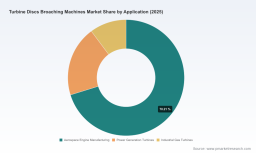
Turbine Discs Broaching Machines Market — Strategic Outlook for 2026 Decisions
PW Consulting’s new Turbine Discs Broaching Machines Market briefing provides a focused, decision-ready view for executives planning capital allocation, supplier strategy, and technology adoption in 2026. Our analysis shows the global market as a multi-hundred-million USD sector that has expanded steadily through the early 2020s and is forecast to continue growing at a compounded annual growth rate (CAGR) of approximately 6.0% across the 2026–2032 projection window. Specifically, the market moves from an estimated USD 435.8 million in 2025 toward a mid-600s million USD total by 2032 — a trajectory that compresses opportunity and risk into the immediate planning horizon.
Turbine Discs Broaching Machines Market
Why 2026 is a Strategic Inflection Point
-
Demand-side momentum. Commercial aviation recovery combined with continued investment in gas and steam turbines for power generation are increasing requirements for precision fir‑tree and dovetail broaching on turbine discs. This intensifies demand for machines that can handle high-strength, heat-resistant alloys at tight tolerances.
Turbine Discs Broaching Machines Market -
Materials and process intensity. Turbine discs are frequently produced from nickel‑based superalloys (e.g., Inconel-class materials) that mandate high-force, highly controlled broaching systems and tooling. This specialization elevates total cost of ownership (TCO) and supplier stickiness.
Turbine Discs Broaching Machines Market -
Regulatory gating. Aerospace broaching for engine components remains tightly regulated: NADCAP accreditation and equivalent quality programs are essentially prerequisite for contractors participating in aero engine supply chains. Compliance timelines should be built into procurement and qualification plans for 2026 projects.
-
Industry structure. The market exhibits significant concentration among a small number of specialist providers — a driver of both pricing power and strategic partner emphasis. Firms evaluating machinery purchases will need to weigh supplier resiliency and aftermarket capability alongside initial price.
What this Report Delivers — Practical, Actionable Content
-
Market sizing and outlook: global totals and trend analysis (base year 2025; forecast 2026–2032), with scenario stress-testing for demand shocks and supply disruptions.
-
Segmentation mapping: machine types (vertical vs. horizontal), application classes (aerospace engine manufacturing, power generation, industrial gas turbines), and regional dynamics — presented in a way that supports deployment sequencing and go‑to‑market prioritization. Note: detailed segment tables and line‑item splits are reserved for full report subscribers.
-
Vendor scorecards and capability matrices: technology scope, automation readiness, process monitoring, maximum part envelope, aftermarket support, and NADCAP/quality certification status.
-
CapEx decision framework: TCO modelling templates that capture machine acquisition, tooling lifecycle, NADCAP/qualification costs, cycle-time impacts, and expected uptime under alternative production scenarios.
-
Supply‑chain risk assessment: raw-material exposure, single‑source supplier flags, and reman/used equipment pathways to shorten lead times.
-
Technology roadmaps and adoption playbooks: automation and Industry 4.0 integration, in‑process metrology, broach condition monitoring, and retrofit opportunities for legacy assets.
-
Case studies and procurement checklists: real-world examples of broaching cell redesign, automation of disc handling, and contracted service models that reduced cycle time or improved qualification lead times.
Key Market Dynamics and Strategic Implications
-
Consolidation and concentration. With the top-tier players capturing a dominant share of the market, large OEMs and strategic MROs face a trade‑off between supplier specialization (higher performance and integration) and supplier dependency (commercial leverage and supply risk). Our market concentration metrics signal that partnering strategies and long‑term service contracts should form a central pillar of procurement plans.
-
Aftermarket and services as differentiation. Suppliers that build credible service footprints — including NADCAP‑adherent processes, on‑site maintenance, spare broach inventories, and rapid reconditioning — win repeat business and can command premium pricing. Expect aftermarket revenue to be a growing part of supplier economics through 2032.
-
Capital intensity vs. agility. New machine purchases are high-capex commitments. For buyers with variable volumes, used or remanufactured equipment, modular retrofit packages, and third‑party broaching services offer pragmatic ways to balance capacity with capital preservation.
-
Skill and tooling constraints. Advanced broaching requires specialist tooling design and life‑cycle management. Investment in tooling engineering, process monitoring, and in‑house expertise will materially affect cycle time, yield, and qualification speed.
-
Technology enablement. Integration of process monitoring, predictive maintenance, and automated loading/unloading is moving from differentiator to baseline expectation. Suppliers that demonstrate PLC-to-cloud telemetry, analytics, and closed-loop SPC will be preferred by quality‑sensitive buyers.
Competitive Landscape — Who Matters and Why
-
FORST Technologie GmbH & Co. KG (Germany) — FORST’s compact, high‑rigidity lines (horizontal and vertical series) are engineered specifically for external broaching of dovetail and fir‑tree profiles on turbine and compressor discs. Their emphasis on process monitoring, automation options, and capacity for large disc diameters makes them a natural partner for OEMs seeking integrated production cells and strong European supply chain credentials. Recent trade show participation underscores an active product‑development pipeline.
-
Broaching Machine Specialties (BMS, USA) — BMS’s capability to source, remanufacture, and supply both new and used large horizontal machines (including legacy models) positions it uniquely for North American customers pursuing rapid capacity expansion or cost‑efficient asset acquisition. Their high‑visibility engagement with policymakers and community outreach reflects a strategic focus on domestic manufacturing continuity.
-
Arthur Klink GmbH (Germany) — A specialty manufacturer with expertise across special broaching, surface broaching, and tooling. Arthur Klink is well placed for bespoke applications where part geometries or production processes depart from standard configurations.
-
Colonial Tool Group (USA) — Colonial combines CNC broaching platforms (including multi‑axis horizontal designs) with aerospace production know‑how. Their support for large stroke systems and tailored configurations aligns with tier suppliers and MROs seeking scalable horizontal broaching capacity.
-
Nachi‑Fujikoshi Corp. / Nachi America (Japan) — Known for vertical processing machines capable of heavy cutting and high accuracy, Nachi’s product set is attractive where vertical broaching aligns with existing cell layouts or specific process flows. Their tooling for fir‑tree grooves is an important capability for aero-focused plants.
-
Pioneer Broach Company (USA) — Beyond machine manufacture, Pioneer’s combination of broaching services and NADCAP‑aligned process credentials makes it a go‑to partner for engine component makers requiring accredited subcontracting or technical support during qualification phases.
-
Taizhou Chengchun Automation Equipment (China) — Offers competitively priced turbine disc broaching machines emphasizing groove broaching with electrical and hydraulic systems. Their value proposition is relevant for cost‑sensitive programs and regions where local sourcing is prioritized.
Two recent vendor developments to note: Broaching Machine Specialties hosted a U.S. congressional engagement as part of a manufacturing advocacy initiative, signaling political and industrial relevance for domestic broaching manufacturing; FORST’s participation at a major production-technology trade fair underscores continued vendor investment in product visibility and incremental innovation.
Recommended 2026 Actions — For OEMs, Tier Suppliers, MROs, and Investors
-
Embed scenario-based CapEx planning. Build base, upside, and downside CapEx scenarios into 2026 budgets that account for lead times, NADCAP qualification costs, and tooling ramp‑up. Use TCO templates to compare new vs. reman/used acquisitions.
-
Prioritize supplier selection criteria beyond price. Evaluate process monitoring, automation readiness, aftermarket footprint, and qualification support as first-order selection factors.
-
Invest in tooling and process engineering capability. Shorter tooling cycles and better broach life‑cycle management are high‑ROI levers for yield improvement and cost control.
-
Negotiate long‑term service partnerships. Given market concentration and aftermarket value, structured service agreements (SLA + spares + guaranteed lead times) reduce operational risk and protect time‑to‑market.
-
Use phased automation and retrofit strategies. Where immediate full‑line automation is unaffordable, deploy modular retrofits for handling and in‑process inspection to capture early productivity gains.
-
Consider dual‑track sourcing. Combine a primary specialist provider for mission‑critical capacity with a secondary, cost‑efficient supplier or reman provider to buffer lead‑time risk.
Get the Full Intelligence
This briefing highlights the strategic contours of the Turbine Discs Broaching Machines Market and why 2026 decisions will disproportionately influence value capture across the next technology cycle. PW Consulting’s full report contains the detailed segmentation tables, machine-level specifications, supplier scorecards, downloadable TCO models, and supplier negotiation playbooks that operational and procurement teams need to execute with confidence. Core segment tables and the proprietary vendor scoring dataset are intentionally omitted from this summary — they are available in the full report.
To access the complete market model, vendor matrices, and downloadable tools that underpin our recommendations, visit PW Consulting’s research portal or contact our client services team to request the full Turbine Discs Broaching Machines Market report and tailored briefings for your procurement or investment committee.
For detailed analysis of this topic, please visit the official page: Turbine Discs Broaching Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


