



PW Consulting Forecasts Electrical Measurement System Market to Expand at a 6.03% CAGR During 2026–2032

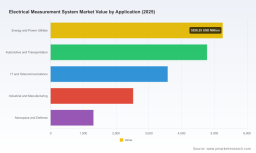
Electrical Measurement System Market 2026: Strategic Intelligence for Executive Decision‑Making
PW Consulting’s latest market study on Electrical Measurement Systems delivers a concise, actionable intelligence package designed to inform boardroom decisions in 2026. Built from a robust historical base and forward-looking scenario analysis, the report explains what market movement means for product strategy, supply‑chain resilience, M&A prioritization, and service monetization—while reserving proprietary segment-level detail for the full dossier available on our website.
Electrical Measurement System Market
Why this report matters to 2026 strategy
After a steady expansion through the first half of the decade, the global electrical measurement systems market reached approximately USD 17.45 billion in our base year (2025). Our model projects continued expansion through the forecast window (2026–2032) at a compound annual growth rate of 6.03%, taking the market to roughly USD 26.29 billion by 2032. These headline dynamics are driven by accelerating electrification across industries, the rapid rise of power‑electronics applications (notably EVs and renewables), and growing demand for precision measurement in semiconductor and telecom test flows.
Electrical Measurement System Market
For executives planning capital allocation, product roadmaps, or strategic partnerships in 2026, the implications are clear: incremental top‑line growth is available, but capture will be uneven and contingent on managing technology, supply and regulatory risk. The report transforms these macro trends into immediate, executable strategic choices.
Electrical Measurement System Market
What the report contains — practical, decision‑ready workstreams
- Market sizing & validation: a transparent methodology linking historical vendor shipments, bill‑of‑materials analysis, and demand signals from R&D, manufacturing and field service segments—producing conservative and aggressive scenarios for 2026 planning.
- Technology & product roadmaps: comparative matrices that map instrument families (bench, rack, portable, automated test) to capability gaps, emerging measurement requirements (higher bandwidth, lower noise floors, power quality analytics), and near‑term component constraints.
- Supply‑chain stress tests: scenario playbooks that quantify exposure to raw material concentration, semiconductor export controls, and long analog‑IC lead times—plus tactical mitigations such as dual‑sourcing, strategic inventory, and localized assembly options.
- Regulatory impact scenarios: tailored analyses of trade controls, import/export policy trends, and product compliance requirements that may affect market access, pricing, and certification timelines.
- Commercial playbooks: segment‑specific GTM strategies, service and calibration monetization models, pricing sensitivity analyses, and channel optimization recommendations for enterprise and field markets.
- Competitive positioning & vendor scorecards: evidence‑based profiles, capability heatmaps, and “fit for partnership” indices to identify potential M&A targets, OEM suppliers, and alliance partners.
- Case studies and deployment checklists: real‑world examples illustrating how leading users reduced total cost of ownership, accelerated test throughput, and improved safety/compliance using novel measurement approaches.
- Data annex & templates: downloadable forecast tables, supplier risk matrices, and a procurement RFI template tailored for 2026 procurement cycles.
Competitive landscape — who wins and why
The market remains moderately consolidated with clear tiers of capability. Our concentration analysis shows the top three vendors capture a meaningful share of global revenues, and the top five extend that influence further—underscoring the importance of scale, channel reach, and R&D depth in shaping outcomes.
At the premium/high‑performance end, incumbent test & measurement leaders differentiate on bandwidth, fidelity, and systems integration. These vendors are best positioned to serve high‑value applications in semiconductor R&D, aerospace, and advanced telecom testbeds—where measurement accuracy and protocol support command premium pricing.
Field and handheld instrument leaders retain advantaged positions through deep channel relationships with utilities, industrial service providers and contractors. Their strengths are product robustness, service networks, brand trust in safety‑critical settings, and breadth of portable test portfolios.
Specialist suppliers and automation OEMs compete to capture the growing automated test and power‑electronics segments. These players pair hardware with software, test‑system integration, and assembly‑line automation capabilities that appeal to EV, inverter and semiconductor manufacturers seeking end‑to‑end test solutions.
Newer entrants and low‑cost vendors continue to expand global presence by undercutting price points for education, small labs, and entry‑level industrial use, exerting margin pressure in the lower tiers while stimulating demand at the base of the market.
Company callouts (strategic implications)
- Keysight, Rohde & Schwarz, Tektronix and Teledyne: continue to invest heavily in R&D and platform ecosystems—recommended actions for competitors include deepening software services, pursuing joint‑product roadmaps with chipset suppliers, and selectively co‑funding compliance labs with customers.
- Fluke and Amprobe: maintain dominant field presence—recommended strategies include expanding managed service contracts, leveraging digital calibration records, and bundling hardware with remote diagnostics to drive recurring revenue.
- National Instruments (NI), Advantest and Chroma: strong in automated and production test systems—strategic buyers should evaluate integration opportunities that shorten time‑to‑test for EV and semiconductor customers.
- Yokogawa, Hioki, Megger and Hipotronics: specialized strength in power analysis and high‑voltage testing—opportunities exist to cross‑sell analytics and condition‑based maintenance services to utilities and large industrials.
- Rival low‑cost manufacturers (Rigol, Siglent, GW Instek): can rapidly scale in emerging markets—incumbents must defend premium value by emphasizing lifecycle support, accuracy, and certifications.
External risks and structural headwinds
A number of exogenous factors will materially influence strategy execution in 2026:
- Concentration in upstream materials: the dominant global position of a single refining geography for critical rare earths increases exposure for magnet and precision component supply—scenario planning for substitution and recycling is prudent.
- Trade and export controls: recent adjustments to semiconductor and equipment trade policies create uncertainty in sourcing advanced components; legal and compliance functions should be embedded into procurement decisions immediately.
- Component market volatility: AI‑driven semiconductor demand caused sharp price and availability dislocations in late 2025; analog ICs and passives are showing extended lead times, in some cases exceeding many months—this can slow new instrument releases or force design compromises.
- Operational labor and logistics: extended lead times and regional policy responses heighten the value of flexible manufacturing and nearshoring options for critical assemblies.
Practical recommendations for 2026 executive agendas
- Adopt scenario‑based sourcing: implement tiered sourcing plans that include qualified secondary suppliers, pre‑negotiated allocation agreements, and option clauses to convert to local assembly where needed.
- Prioritize software and service monetization: instruments will increasingly be differentiated by analytics, firmware upgrade paths, and cloud‑based calibration services—shift to subscription models to stabilize revenue.
- Invest in modularity: design modular instrument platforms that allow component substitutions without full re‑qualification to reduce obsolescence risk and accelerate response to supply shocks.
- Focus M&A on capability fills: prioritize targets that bring software, systems integration, or field‑service scale rather than incremental hardware breadth alone.
- Embed regulatory foresight: incorporate export control and compliance scenarios into new product development gating and partner selection processes.
Recent market motion — signal, not noise
Activity in early 2026 underlines shifting product priorities. For example, a leading test vendor released a new catalog emphasizing ultra‑low leakage detection for safety‑critical insulation testing—illustrating how incremental instrumentation sensitivity can open adjacent service markets in asset‑intensive industries.
Meanwhile, component market turbulence and policy shifts are not transient background noise; they materially affect product roadmaps and supplier commitments. Companies that treat these as strategic constraints rather than tactical annoyances will secure competitive advantage.
How PW Consulting’s report supports 2026 decision cycles
Our study is structured to move executives from insight to action within typical planning cadences: quick executive summaries for board briefings, detailed annexes for procurement and engineering teams, and playbooks for commercial leaders. The work is explicitly designed to be a decision‑support tool for capital allocation, product timing, supplier negotiations, and M&A screening in the year ahead.
To preserve commercial value and protect client confidentiality, this release highlights core findings and actionable recommendations while withholding proprietary segment‑level tables and vendor scorecards. Access to the full report—including granular segmentation, vendor benchmarking, and downloadable forecast models—is available via our report page.
Next steps
For executive briefings, bespoke workshops, or immediate access to the full Electrical Measurement System Market report (with detailed segment splits, vendor scorecards, and procurement templates), please visit our site or contact PW Consulting’s industry practice. Equip your 2026 planning with market‑tested scenarios, supplier stress tests, and practical playbooks that turn growth opportunity into reliable outcomes.
For detailed analysis of this topic, please visit the official page: Electrical Measurement System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


