



PW Consulting: Disproportionated Rosin Market Poised to Reach USD 567.5 Million by 2032 with 4.19% CAGR (2026–2032)PW Consulting: Polariscope Strain Viewer Market to Rise from USD 70.4M in 2025 to USD 101.37M by 2032 at a 5.35% CAGR, Driven by Benchtop Devices and PET Preform Inspection

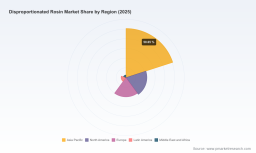
Disproportionated Rosin Market — Strategic Imperatives for 2026
PW Consulting’s latest market research briefing on the Disproportionated Rosin (DPR) market synthesizes commercial intelligence, upstream feedstock dynamics, regulatory pressure, and supplier economics into an operationally focused playbook for 2026 decision‑makers. This preview highlights the report’s strategic value for procurement, product development, M&A, and regulatory planning — while withholding the granular segment tables and proprietary scenario outputs that are available in the full report.
Disproportionated Rosin Market
Market snapshot: macro trajectory and what it means for 2026
Using 2025 as the reporting base year, PW Consulting measures the global DPR market as a mid‑hundreds million USD industry that has expanded materially since 2020. From our baseline through the forecast horizon (2026–2032), the market is projected to grow at a compound annual growth rate (CAGR) of 4.19%, reaching a materially larger scale by 2032 under our central case. That growth rate reflects steady industrial demand for DPR across adhesives, rubber emulsions and specialty coatings, tempered by periodic cyclical swings in downstream manufacturing and raw material availability.
Disproportionated Rosin Market
For executives planning 2026 budgets, the implication is clear: DPR is a stable, growing commodity‑adjacent specialty chemical rather than a high‑velocity breakout market. This positioning favors disciplined, medium‑term investments — supply security, incremental capacity optimization, selective product premiumization — rather than aggressive, high‑risk expansion programs.
Disproportionated Rosin Market
What the full PW Consulting report contains (practical content preview)
- Market sizing and validated forecast model (base year 2025; forecast period 2026–2032) with scenario stress‑testing.
- Supply chain and feedstock analysis, including rosin sourcing, price elasticity, and logistics risk maps.
- Competitor benchmarking and supplier scorecards covering manufacturing footprint, grade breadth, and go‑to‑market strategies.
- Regulatory impact assessment (including REACH implications) and practical compliance checklists for formulation and stabilization.
- Commercial playbook for buyers and sellers: contract structures, price pass‑through models, and working capital levers.
- M&A and partnership candidate shortlist with rationale and integration risk profiles.
The full dataset includes segment‑level volumes, regional and application splits, and price sensitivity matrices — intentionally excluded here to preserve the role of this article as a strategic preview.
Key dynamics shaping DPR supply and demand in 2026
- Upstream feedstock concentration and quality variability. Gum rosin remains the principal upstream feedstock for DPR manufacture, complemented by tall oil rosin from pulp operations. Global rosin tonnage is substantial, but purity and availability vary by source and processing route, which creates localized cost differentials and qualification requirements for downstream formulators.
- Price discovery and export dynamics. DPR trade exhibits distinct price tiers by grade and specification. Average export price benchmarks provide useful negotiation anchors for purchasers, but quality and logistics add meaningful premium or discount to any transactional price.
- Regulatory and product stewardship pressure. DPR and related rosin derivatives sit inside established regulatory frameworks (for example, REACH registrations and associated stabilization considerations). Buyers and sellers must incorporate registration timelines, testing needs, and label/communication obligations into 2026 procurement cycles.
- Application demand patterns. Traditional industrial uses — synthetic rubber emulsifiers, adhesives and sealants, pigments and printing inks — continue to drive the bulk of consumption. Innovation pockets (e.g., higher‑performance tackifiers for sustainable adhesives, or heat‑resistant DPR grades for specialty elastomers) are emerging as the most likely vectors for margin expansion.
Competitive landscape — positioning and strategic takeaways
Market concentration is moderate: the three largest suppliers account for just over thirty percent of global DPR supply, while the five largest capture less than half the market. This structure creates a dual market logic — there are scale advantages (integration with pine chemicals, access to tall oil feedstock, global distribution) but also persistent opportunities for regional and technical challengers.
Three archetypes dominate supplier strategies:
- Large integrated players (global footprint, broad portfolio). Established specialty chemical groups based in North America, Europe and Japan bring integrated pine‑chemicals portfolios, channel relationships into adhesives and rubber markets, and the balance‑sheet capacity to invest in regulatory compliance and product development. Their advantage is breadth of application support and global logistics.
- Regional specialists (cost‑competitive production and proximity to rosin feedstock). Numerous manufacturers in Asia, particularly China and India, combine proximity to gum rosin sources and lower cost structures with rapid grade development cycles. These companies are the first choice for high‑volume industrial formulations where specification requirements are standard and cost sensitivity is high.
- Technical niche players (differentiation through grade or service). Smaller firms and certain European/Japanese specialists win business by supplying premium grades, technical support for complex formulations, or by solving specific processing challenges (e.g., improved heat resistance, lower oxidation susceptibility).
For 2026 strategy, that translates into concrete actions: global buyers should secure a balanced supplier mix that combines regional low‑cost exposure with at least one technically oriented partner; sellers should decide whether to compete on cost, technical differentiation, or a hybrid model supported by targeted capacity investment.
Practical strategic recommendations for 2026
- Prioritize supply security via diversified contracting. Use a mix of long‑term supply agreements for base load and shorter, indexed contracts for flex volume. Embed quality acceptance tests and logistics SLAs to reduce qualification friction.
- Invest selectively in product premiumization. R&D efforts that yield DPR grades with improved thermal stability, lower odor, or better emulsification performance produce higher margin potential and reduce direct price competition.
- Lock upstream feedstock partnerships. Consider tolling or vertical arrangements with rosin processors and pulp mills to stabilize input costs and ensure access to preferred raw material grades, especially where tall oil offers logistical or purity advantages.
- Adopt a regulatory readiness posture. Align compliance budgets to handle registrations, testing, and reformulation risk. Early engagement with regulatory bodies and proactive product stabilization testing reduces time‑to‑market friction.
- Use M&A and alliances tactically. Given the moderate concentration profile, bolt‑on acquisitions that add technical grades, regional distribution, or feedstock access can be value‑accretive without requiring transformational capital.
- Implement demand‑side initiatives. Work with formulators to redesign adhesive, rubber, and coating systems that reduce DPR dependency where appropriate, or that convert DPR into a value‑added performance input commanding a premium.
How PW Consulting’s report supports 2026 decision cycles
Executives, procurement leads, and corporate development teams will find the full PW Consulting Disproportionated Rosin Market report actionable for the 2026 planning window because it combines:
- Robust, auditable market sizing and a transparent forecast model with scenario toggles for raw material shocks and downstream demand shifts.
- Supplier scorecards and integration risk assessments that translate into due diligence checklists for sourcing and M&A.
- Commercial tools — contract templates, indexation approaches, and a margin sensitivity heatmap — that can be operationalized immediately in negotiations.
We intentionally withhold segment‑level tables, minute regional shares, and our proprietary pricing matrix from this preview to preserve their value for subscribers and direct decision‑makers. Those outputs form the core of the “buy” decision for firms that require executable plans rather than high‑level context.
Next steps and access
For teams building 2026 procurement, R&D or M&A roadmaps, the full PW Consulting report contains the granular segmentation, supplier contact mapping, and model files necessary to move from strategy to execution. Contact PW Consulting or visit our report page to obtain the complete dataset, supplier scorecards, and our advisory engagement options.
In an industry where feedstock quality, regulatory readiness, and targeted technical differentiation drive commercial outcomes, having a data‑driven, execution‑oriented intelligence package is not optional — it’s a competitive necessity. Our Disproportionated Rosin Market report is designed to be that package for 2026.
For detailed analysis of this topic, please visit the official page: Disproportionated Rosin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


