



PW Consulting: Embedded Wi‑Fi Modules Market Poised to Expand at a 13.59% CAGR Through 2032

Embedded Wi‑Fi Modules Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
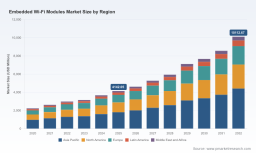
As enterprises accelerate device digitization, PW Consulting’s latest Embedded Wi‑Fi Modules Market study offers a concise, decision‑grade briefing for leadership teams planning product, procurement, and ecosystem strategies in 2026. The market has demonstrated robust expansion over the past half decade — growing from USD 2,235.12 Million in 2020 to USD 4,142.05 Million in 2025 — and is forecast to scale to USD 10,112.67 Million by 2032 at a compound annual growth rate (CAGR) of 13.59% across the 2026–2032 forecast window. This growth trajectory underpins near‑term investment choices across product roadmaps, supply chain hedging, and standards adoption.
Why this report matters for 2026 decisions
-
Prioritize technology roadmaps with confidence — The acceleration toward Wi‑Fi 6E/7 capabilities and long‑range variants makes timing decisions (when to redesign, when to obsolesce, when to migrate) critical. Our analysis converts standards timelines and regulatory shifts into actionable milestone windows for product managers and systems architects.
-
Align sourcing with risk‑adjusted supply scenarios — Semiconductor supply constraints, including DRAM availability that affects Wi‑Fi 7 platforms, create asymmetric lead‑time and cost risks. The report maps realistic procurement hedges, dual‑sourcing approaches, and inventory strategies calibrated to expected lead‑time volatility in 2026.
-
Define go‑to‑market and certification playbooks — Embedded Wi‑Fi modules require careful certification and integration paths across consumer, industrial, automotive and medical segments. We provide playbooks that reduce time‑to‑market while limiting integration rework and certification delays.
-
Shape M&A, partnership, and ecosystem moves — Market concentration metrics and vendor capability matrices in the study help identify partnership targets, bolt‑on acquisition profiles, and potential OEM/ODM alliances that accelerate platform delivery without diluting IP control.
-
Navigate regulatory uncertainty — With recent regulatory changes in the 6 GHz spectrum and ongoing consultations across jurisdictions, the report translates regulatory outcomes into practical constraints and opportunities for product feature sets and regional product strategy.
What the report contains (practical, executable content)
-
Market sizing and forecast model (2020–2032) with scenario and sensitivity workstreams that let you stress‑test product demand under alternate adoption rates and regulatory outcomes.
-
Technology deep dives — comparative analysis of Wi‑Fi 4/5, Wi‑Fi 6/6E, Wi‑Fi 7 and long‑range/low‑power variants (e.g., Wi‑Fi HaLow), including integration tradeoffs (power, latency, throughput, certification) for embedded designs.
-
Supply chain and BOM impact assessment that quantifies exposure to chipset and module constraints, and recommends procurement levers and buffer strategies tailored to embedded product lifecycles.
-
Vendor scoring toolkit — objective evaluation criteria across technical capability, certification completeness, manufacturing footprint, and partner ecosystem to support vendor selection and RFP/RFQ design.
-
Regulatory and standards annex — timeline mapping for 6 GHz access, Wi‑Fi 7 standardization milestones, and national/regional compliance checklists that affect feature enablement and go‑to‑market sequencing.
-
Commercial playbooks — pricing, channel, and volume contracting templates to protect margin while scaling embedded product deployments.
Note: this press release intentionally omits granular segment split values (regional, by‑type, and by‑application breakdowns) to preserve the value of the full, source report; the study includes these detailed splits and dynamic scenario outputs for subscribers.
Competitive landscape — concentration and strategic implications
The embedded Wi‑Fi modules market displays moderate concentration: the top three vendors account for a meaningful portion of market supply while a broader set of five further increases market share concentration. This structure produces both bargaining power for large OEMs and opportunity windows for differentiated module suppliers that combine certification breadth, integration ease, and cost competitiveness.
-
Espressif Systems (Shanghai) — Known for the ESP32/ESP8266 families, Espressif emphasizes developer‑friendly, integrated Wi‑Fi + Bluetooth SoCs tailored to IoT and industrial applications. Their ecosystems and low‑cost platforms remain go‑to choices for rapid prototyping and high‑volume consumer deployments.
-
Murata Manufacturing (Kyoto) — Focuses on miniaturized, certified modules and combo solutions, with design strengths in form factor and automotive/industrial grade reliability. Murata’s emphasis on ultra‑low‑power and HaLow solutions targets long‑range IoT segments.
-
Silicon Labs (Austin) — Supplies low‑power Wi‑Fi SoCs and modules with multi‑protocol support, positioning for industrial and battery‑sensitive embedded devices.
-
Infineon Technologies (Neubiberg) — Brings deep competence in secure connectivity and industrially hardened chipsets, appealing to customers where security and resilience are prime concerns.
-
Texas Instruments (Dallas) — Provides SimpleLink modules and SoCs with proven performance in automation and smart‑home contexts, backed by broad software stacks and ecosystem support.
-
Qualcomm Technologies (San Diego) — Leads on high‑performance and micro‑powered IoT module platforms, combining advanced PHY capabilities with programmable connectivity features.
-
Broadcom (San Jose) — Dominant in high‑performance chipsets used in gateways and advanced embedded modules supporting the newest feature sets.
-
Realtek (Hsinchu) — Competes on cost‑effectiveness for high‑volume consumer electronics and embedded IoT modules.
-
Microchip Technology (Chandler) — Offers certified plug‑and‑play modules and MCUs targeted at low‑power and industrial use cases.
-
Quectel (Shanghai) — Provides a broad IoT module portfolio, including combo modules for converged connectivity in embedded devices.
-
Telit Cinterion (Irvine) — Integrates Wi‑Fi offerings within a broader IoT connectivity platform for industrial applications.
-
NXP Semiconductors (Eindhoven) — Packs Wi‑Fi + Bluetooth partner modules and SoCs for industrial and automotive customers focused on integration and safety.
-
AzureWave Technologies (Taipei) — Specializes in embedded Wi‑Fi modules for consumer, automotive, and industrial integration, emphasizing time‑to‑market advantages.
Regulatory and technology inflection points shaping 2026 strategy
-
6 GHz policy movement — Recent regulatory authorizations broaden unlicensed access but introduce differentiated power and coordination regimes. In the U.S., new allowances for geofenced variable power (GVP) devices and established very low power (VLP) rules alter the spectrum opportunity set for device designers.
-
Wi‑Fi 7 standardization — With core specifications and subsequent revisions finalizing through 2024–2025, embedded module vendors are racing to implement support for wider channels (up to 320 MHz) and feature sets that materially change throughput and latency characteristics for edge‑connected systems.
-
Supply chain constraints — Semiconductor component bottlenecks (including DDR memory impacting Wi‑Fi 7 platforms) will continue to influence supplier selection and lead‑time assumptions in 2026; the study quantifies risk exposure by chipset family and supplier geography.
Recent vendor moves that signal market direction
-
Product introductions across the ecosystem — From new Wi‑Fi 7 modules and SoCs to HaLow long‑range and ultra‑low‑power variants, recent launches indicate parallel product migrations: premium, high‑throughput modules for performance‑critical devices and specialized low‑power modules for wide‑area IoT.
-
Industry engagement continues to accelerate — Leading component suppliers and RF specialists are increasingly active at trade events and in pre‑certification initiatives, reducing integration friction for OEMs that partner early.
Recommended next steps for 2026
-
Run a three‑tier product risk assessment (core, bridge, experimental) aligned to the report’s scenario outputs to prioritize which SKUs to update for Wi‑Fi 6E/7 and which to postpone.
-
Embed regulatory scenario planning into product launch checklists — incorporate GVP/VLP and regional 6 GHz outcomes into certification timelines and channel selection.
-
Engage with at least two module suppliers from distinct ecosystem clusters (performance‑centric and cost‑optimized) to implement parallel development tracks that reduce single‑supplier risk.
-
Use the report’s vendor scoring toolkit during upcoming RFP cycles to ensure procurement balances price, certification speed, and roadmap compatibility.
PW Consulting’s Embedded Wi‑Fi Modules Market report is purpose‑built for leaders who must balance speed, cost, and technical differentiation in embedded connectivity. To access the full dataset, segmentation matrices, vendor scorecards, and executable templates referenced here, please visit PW Consulting’s official report page for subscribers.
For detailed analysis of this topic, please visit the official page: Embedded Wi Fi Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


