



PW Consulting: Road Construction Services Market Set to Grow at 7.51% CAGR Through 2032 as Asia Pacific Dominates

Road Construction Services Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
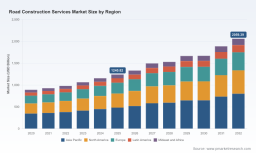
The global Road Construction Services market stands at a critical inflection point as firms set strategies for 2026. PW Consulting’s latest market research positions the overall market at approximately USD 1,240.82 Billion in 2025, expanding to roughly USD 1,332.32 Billion in 2026 and tracking toward continued growth through the forecast window (2026–2032) at a compounded annual growth rate (CAGR) of 7.51%. By 2032 the market is projected to exceed USD 2,000 Billion — a dynamic backdrop that demands timely, actionable choices from investors, contractors, equipment suppliers, and public-sector planners.
Road Construction Services Market
What this report delivers — practical, decision-grade outputs
- Executive playbooks for near-term bid and procurement strategy that reconcile margin preservation with aggressive backlog capture in inflationary environments.
- Scenario-based financial models (base, stress, upside) that translate macro growth into project-level investment thresholds, IRR sensitivities, and working-capital implications.
- Labor and materials sensitivity matrices that model the P&L impact of wage pressure, input-price shocks, and tariff regimes on typical road construction contracts.
- Contract and risk-allocation templates tailored for design-build, EPC and PPP arrangements, with annotated negotiation levers that preserve cashflow under cost escalation.
- Technology and fleet upgrade roadmaps, prioritizing digital tendering, asset-management telematics, and mechanization pathways to offset rising labor costs.
- Regulatory and procurement guidance for public agencies to accelerate renewals, maintenance programs, and concession structures while protecting budgetary outcomes.
Market dynamics and implications for 2026 decision-making
The headline growth trajectory masks important operational headwinds and structural drivers. Our analysis synthesizes macro growth with near-term industry "noise" to surface the decisions that will define winners and losers in 2026:
Road Construction Services Market
- Labor scarcity and wage inflation: North American and select other markets are projecting acute shortfalls in skilled trades. For example, the U.S. construction sector faces a multihundred-thousand-worker gap by 2026, and construction wages rose materially year-over-year in 2025. For contractors, this elevates the strategic importance of workforce planning, modularization, and automation investments that reduce crew-hour exposure.
- Material-price volatility and tariff risk: Nonresidential construction input prices surged sharply in early 2026, and steel/aluminum tariffs implemented across 2025–2026 have amplified cost unpredictability. Structural-steel cost inflation alone added double-digit pressure during 2025 — a direct margin risk for bridge-heavy programs. Procurement teams must shift from ad hoc buying to hedged, indexed contracts and vendor partnerships that pass through limited, predefined cost adjustments.
- Procurement and financing dynamics: Public-sector stimulus, maintenance backlogs, and road-safety mandates continue to underpin demand. However, funding profiles and concession structures are shifting — requiring contractors and investors to model extended payment cycles, availability-based payments, and hybrid financing solutions.
- Consolidation and competition: While headline growth creates volume, market concentration remains low — the top three and five players account for a modest share of global activity — signaling a fragmented marketplace. This structure favors regional champions, niche specialists, and acquisitive firms seeking scale in target corridors.
Competitive landscape — what the major players signal for 2026
The vendor landscape spans global integrated contractors, national heavy-civil specialists, and engineering-driven delivery firms. Prominent names active across major portfolios include large state-backed engineering contractors, multinational infrastructure groups, and established heavy-civil firms. Recent public moves illustrate strategic patterns:
Road Construction Services Market
- Contract awards in developed markets demonstrate a willingness by governments to accelerate large-capacity expansions and renewals, with incumbents and consortiums capturing long-duration EPC scopes.
- Strategic corporate initiatives — business-plan articulations and backlog disclosures — show leading contractors repositioning for growth through backlog optimization, selective international expansion, and service-line diversification.
- Engineering and design firms are winning statewide and framework agreements that convert advisory capability into recurring delivery pipelines, underlining the value of integrated program-management capability.
Strategically, the low headline market concentration (a fragmented supplier base) means that scale is not the only route to advantage. Firms with differentiated delivery models — e.g., superior risk-transfer contracting, embedded digital tools, or fleet modernization — can leapfrog larger competitors in targeted segments. Our competitive profiles analyze each major player’s geographic posture, capital structure, alliance patterns, and demonstrated capability to deliver turnkey road projects under inflationary stress.
Strategic imperatives for executives making decisions in 2026
Actionable choices fall into four pragmatic buckets. Firms that prioritize these will be positioned to protect margins, accelerate backlog, and harvest long-term value from the growth cycle.
- De-risk procurement and contracting: Implement index-linked material clauses, adopt dual-sourcing for critical inputs, and insist on staged acceptance criteria in long-duration contracts to minimize cost-to-complete exposure.
- Embed labor resilience: Rapidly scale apprenticeship and cross-training programs, deploy mechanization in labor-intensive tasks, and explore labor-sharing consortiums for regional projects to smooth peak demand.
- Invest in measurable productivity: Prioritize telematics, machine-control systems, and predictive maintenance to increase utilization and reduce downtime — investments that pay back most rapidly where wage inflation is highest.
- Pursue selective M&A and partnerships: Target bolt-on acquisitions that add geographies or technology, and form alliances with material suppliers to secure capacity and price transparency.
- Revise financial planning: Stress-test project pipelines against material and wage shocks, maintain higher working-capital buffers, and structure financing to align with availability-based revenue where possible.
- Engage public clients on pragmatic policy solutions: Advocate for procurement designs that allow adaptive pricing, quick-release contingency funding for emergency repairs, and longer-term concession models that improve lifecycle outcomes.
Decision-making tools in the PW Consulting report
The report is designed to be an execution companion — not an abstract overview. Key tools include:
- Interactive scenario spreadsheets that translate market CAGR and macro volatility into project-level cashflow outcomes, with toggles for tariff exposures and wage inflation paths.
- Contract drafting checklists and risk-allocation templates mapped to three common delivery models (design-bid-build, design-build/EPC, PPP), each with clause-level language to protect margin and schedule.
- CapEx/Opex replacement models for fleet renewal decisions, showing payback under alternate labor-cost trajectories and fuel/energy assumptions.
- Stakeholder engagement playbooks for public—private dialogues, including example concession structures and government-friendly performance metrics that reduce funding friction.
How to use these insights in 90/180/365-day plans
- 90 days: Rebaseline active tenders for realistic input-cost assumptions; implement mandatory material-index clauses; prioritize bids with favorable payment profiles.
- 180 days: Launch a workforce resilience program; pilot mechanization on two high-hour projects; secure key supplier agreements to lock in capacity.
- 365 days: Execute targeted M&A or alliance to shore up regional scale; roll out digital asset-management across the fleet; transition a share of revenue to availability-based contracts.
Why PW Consulting’s Road Construction Services study matters for 2026
Growth is robust at the market level, but the pathway from volume to profit is narrow and reliant on managing input volatility, regulatory shifts, and human-capital constraints. Our report couples the macro view (market size and a 7.51% CAGR over the forecast window) with granular decision tools that allow executives to translate forecasted expansion into resilient execution strategies. The fragmented competitive landscape further amplifies opportunity: firms that sequence investments wisely and adopt disciplined contracting will consolidate advantage.
Next steps and access to the full intelligence
This article highlights the strategic framing and practical outputs available in PW Consulting’s full Road Construction Services Market report. To preserve the tactical value of our segment-level models, granular regional splits, and downloadable scenario files, those detailed tables and proprietary forecasting models are available exclusively in the full report package and via our client portal. Organizations preparing capital budgets, bid strategies, or procurement reforms for 2026 should request the complete report and a tailored briefing with a PW Consulting senior analyst.
For detailed analysis of this topic, please visit the official page: Road Construction Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


