



PW Consulting: Cartridge Systems Market Poised for 5.04% CAGR in 2026–2032, New Report Shows

Cartridge Systems Market 2026: Strategic Imperatives from PW Consulting’s Newest Industry Report
Executive preview
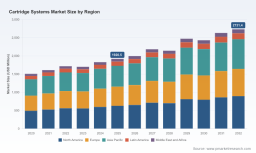
PW Consulting today releases a forward-looking industry brief that synthesizes our full Cartridge Systems Market study (base year 2025, historical 2020–2025, forecast 2026–2032). The market reached approximately USD 1.92 billion in 2025 and, under our central scenario, is projected to expand at a compound annual growth rate of about 5.04% through the 2026–2032 forecast window, approaching roughly USD 2.73 billion by 2032. These topline dynamics reflect a maturing, innovation-driven market that remains highly sensitive to raw-material cycles, sustainability mandates and ongoing pharmaceutical and industrial demand shifts.
Cartridge Systems Market
Why this report matters for 2026 corporate decision-making
-
Actionable forecasting calibrated for near-term disruption: the report blends statistical trend analysis with scenario stress-testing to help commercial, procurement and strategy teams translate macro momentum into operating metrics that matter for 2026 planning cycles.
Cartridge Systems Market -
Playbook for capital allocation: we map where CAPEX directed at automation, fill-finish capability, or PCR-compatible tooling yields the highest ROI under alternative commodity and regulatory scenarios.
Cartridge Systems Market -
Supplier and risk triage: our supplier-scoring templates and supply-chain heat maps are designed so sourcing leads can run a 90- to 180-day supplier resilience and mitigation program against the commodity and logistics constraints now shaping cartridge-system availability.
-
Commercial prioritization: commercial teams receive a practical routing guide for piloting new product introductions (NPIs) and customer trials, aligning go-to-market tactics with expected end-use demand patterns and evolving pharma containment requirements.
Report scope — what’s inside (practical and operational)
-
Methodology & data foundations: end-to-end explanation of our sizing approach (base year 2025, revenue in USD Million), data triangulation methods, primary interviews, and sensitivity testing around commodity inputs.
-
Market sizing and forecast: topline historical series (2020–2025) and a scenario-driven projection for 2026–2032 with clear assumptions for demand drivers, penetration curves and technology adoption rates.
-
Segmentation framework: granular segmentation by geography, product architecture (single-, dual- and multi-component systems), and end-use sectors — presented with commercial implications (note: detailed segment financial splits are reserved for the full report).
-
Competitive landscaping & benchmarking: company scorecards, concentration metrics, capability maps and go/no-go criteria for strategic partnerships and acquisition targets.
-
Supply-chain and input-cost modeling: dynamic cost models that capture polypropylene, HDPE and other polymer price sensitivity, plus scenario layers for logistics disruption and regulatory shifts.
-
Sustainability and regulatory playbooks: pathways to circularity (PCR/PIR adoption, paper-based formats), compliance checklists for pharmaceutical containment, and lifecycle carbon-impact modeling.
-
Commercial and M&A playbooks: 100‑/180‑/360 day routines for market entry, roll-up strategies in mid-market segments, and integration templates for fast value capture.
-
Case studies and useable templates: digital twin examples for manufacturing footprint optimization, supplier RFP templates, and pilot metrics for RTU (ready-to-use) cartridge filling lines.
Market dynamics and near-term drivers
The Cartridge Systems Market in recent years has exhibited uneven but resilient expansion: an underlying recovery post-2023 and steady appetite across healthcare, industrial adhesives and specialized assembly applications. Demand trajectories are increasingly driven less by volume alone and more by product-system complexity — two-component and ready-to-use systems have disproportionate influence on innovation investment, while single-component formats remain the workhorse for scale and cost-efficiency.
Key externalities to watch in 2026:
-
Raw material pressure: polymer pricing and packaging PPI volatility are material inputs to cost curves. Procurement teams need hedging options and alternate-material playbooks to protect margin in low-to-medium elasticity segments.
-
Sustainability transitions: several manufacturers are accelerating PCR/PIR adoption and alternative materials (including novel paper-based cartridge concepts). These shifts are not only regulatory but increasingly customer-driven, affecting procurement, design and capital planning.
-
Pharmaceutical containment & quality: pharma demand for high-integrity primary packaging and RTU solutions is pushing specialized glass and multi-material systems toward premiumization — influencing partner selection and capacity investments.
-
Consolidation and competitive positioning: the market concentration profile indicates that a modest share of volume is controlled by a small set of global players, while the remainder is fragmented — creating both acquisition opportunities and a competitive imperative for scale and differentiation.
Competitive landscape — profiles and strategic takeaways
Our report profiles the major players and their strategic postures. Highlights include:
-
Stevanato Group (Piombino Dese, Italy): a leader in pharmaceutical glass cartridge systems with deep experience in parenteral applications and on-body delivery. Their strategic play centers on high-quality containment and advanced drug-delivery integrations.
-
SCHOTT AG (SCHOTT Pharma) (Mainz, Germany): known for precision glass primary packaging, with strong emphasis on sterility and drug-compatibility—a preferred partner for high-value injectable portfolios.
-
West Pharmaceutical Services (Exton, Pennsylvania, USA): a broad containment and delivery systems provider with capabilities spanning elastomers and engineered delivery components.
-
Gerresheimer AG (Düsseldorf, Germany): supplies both glass and plastic cartridges as part of a diversified primary-packaging portfolio, offering modularity for pharmaceutical clients seeking single-source supply.
-
Nordson EFD (East Providence, Rhode Island, USA): a specialist in industrial dispensing cartridges and precision fluid technology for adhesives and sealants, focusing on dispensing accuracy and application engineering.
-
Sulzer Ltd / medmix (Winterthur, Switzerland): two-component cartridge leader (Mixpac/medmix) with an explicit sustainability angle through greenLine recycled-plastic options.
-
Fischbach GmbH, AptarGroup, Nipro Corporation, Syntegon and others: collectively cover the full spectrum from plastic cartridge hardware and plungers to RTU filling lines — creating an ecosystem where partnerships and vertical integration frequently determine value capture.
Strategic implication: incumbents with integrated fill-finish and quality systems remain advantaged for pharma work; niche specialists that deliver application engineering or sustainability differentiation can command premium pricing in industrial and healthcare segments.
Recent developments that will shift 2026 decisions
-
Material innovation: the introduction of paper-based and recycled-plastic cartridge formats signals a practical shift toward lower-carbon alternatives. These innovations reduce lifecycle emissions while raising questions on compatibility with existing dispensing equipment and barrier performance for certain chemistries.
-
Trade-show and technology diffusion: manufacturers continue to showcase nitrocellulose-free inks and sustainable printing technologies relevant to cartridge decoration and traceability — enabling branding and serialization requirements without the sustainability trade-offs of older chemistries.
-
Modular fill-finish adoption: RTU and modular cartridge-filling lines are expanding, enabling faster qualification cycles for pharma customers and lower capex thresholds for contract manufacturers seeking to add capacity.
Practical recommendations for executives planning 2026
-
Procurement: institute a two-tier hedging strategy for polymers — tactical purchase windows combined with strategic partnerships for PCR volumes. Negotiate supply agreements tied to performance metrics (fill-rate, particulate specs, serialization readiness).
-
R&D & product: prioritize compatibility studies for lower-carbon substrates and pilot RTU solutions with key pharma customers; allocate a small innovation budget to test alternative adhesives, barrier coatings and secondary packaging made from recycled content.
-
Manufacturing & operations: accelerate flexible-line investments that can switch between single- and multi-component production runs without large changeover costs; target automation investments that reduce labor dependency and improve traceability.
-
Commercial & M&A: use the current dispersion between global leaders and regional specialists to pursue tuck-ins that quickly add technical capability (RTU filling, specialized dispensing nozzles, printed traceability). Leverage our target-screening framework to size accretive deals with realistic integration timelines.
-
Sustainability & compliance: build a roadmap linking material substitutions to quantifiable CO₂ reductions and cost-to-serve impacts, and stress-test regulatory compliance for pharma containment under multiple jurisdictions.
What PW Consulting delivers beyond the public preview
The full Cartridge Systems Market report includes the proprietary data tables, granular regional and end-use splits, supplier scorecards, downloadable financial models, and editable commercial templates that support 90‑ to 180‑day action plans. We deliberately withhold detailed segment financial splits in this press release to preserve the commercial value of the full study and to channel stakeholders to the source document where they can access the full evidence base and execution tools.
How to use this briefing now
-
C-suite: integrate the headline growth rate and scenario implications into the 2026 strategic plan and capital allocation discussions.
-
Head of procurement: run the supplied commodity-sensitivity matrix to identify the top three suppliers for strategic hedging pilots.
-
Business development: prioritize pilot conversations around RTU and sustainable cartridge platforms with existing pharma customers where premiumization is feasible.
Closing
Cartridge systems are at an inflection: incremental innovation, sustainability mandates and supply-chain dynamics are reshaping value pools faster than many organizations expect. PW Consulting’s new report equips decision-makers with the forecasted topline, scenario tools, competitor intelligence and operational playbooks needed to convert 2026 uncertainty into competitive advantage. For the complete dataset, segment breakdowns, supplier matrices and executable templates, access the full report on the PW Consulting insights portal.
For detailed analysis of this topic, please visit the official page: Cartridge Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


