



PW Consulting: Automotive Wire & Cable Market to Hit $84.65B by 2032 at 6.1% CAGR

Navigating the Automotive Wire and Cable Market: Strategic Intelligence for 2026 Decision-Making
Executive Overview: Why This Market Demands Executive Attention Now
The automotive wire and cable sector is undergoing a structural transformation that will define competitive positioning for the next decade. As vehicles become increasingly electrified, digitally connected, and safety-critical, the wiring infrastructure that powers them has evolved from a commodity component to a strategic differentiator. Global revenue across automotive wire and cable solutions reached approximately 56.65 billion USD in 2025, and our latest research projects the market to expand to 84.65 billion USD by 2032, reflecting a compound annual growth rate of 6.1 percent over the 2026-2032 forecast horizon. These figures represent more than incremental growth; they signal a recalibration of capital allocation, supply chain architecture, and product portfolio strategy across original equipment manufacturers, tier-one suppliers, and material innovators.
Lithium Battery Roller Press Machine Market
For executives planning 2026 investment cycles, sourcing decisions, and technology roadmaps, understanding the momentum behind this trajectory is no longer optional. The transition from internal combustion architectures to new energy platforms, the proliferation of high-voltage powertrains, and the tightening of safety and environmental regulations are reshaping demand patterns at every tier of the value chain. Our comprehensive market study is designed to translate these macro forces into actionable intelligence. This article serves as a strategic preview of the research, highlighting the analytical framework, the competitive landscape shaping the sector, and the regulatory and material dynamics that will influence margins and procurement strategies throughout the forecast period. Readers seeking the full segmentation analysis, detailed regional demand breakdowns, company-level market share estimates, and scenario-based volume projections are invited to access the complete report through our official research portal.
Carpet Finishing Lines Market
Market Trajectory and Structural Growth Drivers
The historical revenue record from 2020 through 2025 demonstrates consistent expansion despite macroeconomic volatility, supply chain disruptions, and shifting production schedules. Revenue grew from 43.05 billion USD in 2020 to 56.65 billion USD in 2025, a progression that underscores the embedded resilience of automotive wiring demand. Even as factory output fluctuated across regions, the underlying requirement for power distribution, signal transmission, and sensor integration continued to scale with vehicle complexity. The forecast period from 2026 through 2032 extends this upward path, with projected revenue climbing from 61.95 billion USD in 2026 to 84.65 billion USD in 2032.
Commercial and Industrial Built in House Humidifier Market
Several interlocking drivers explain this momentum. First, the industry is witnessing a steady rise in the share of new energy vehicles, which require more extensive high-voltage cabling, heavier gauge conductors, and specialized insulation materials to manage thermal loads and electrical safety. Second, advanced driver-assistance systems and autonomous driving architectures are expanding the number of sensors, cameras, and communication nodes integrated into each vehicle, increasing the length and complexity of wiring harnesses. Third, vehicle platforms are becoming more modular, which can initially raise engineering and component integration costs but ultimately drives demand for standardized, high-reliability cable assemblies across multiple vehicle lines.
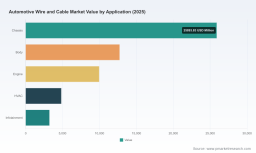
Importantly, the growth profile is not uniform across all vehicle categories or propulsion technologies. The market reflects a mix of conventional platforms and new energy vehicles, with each segment generating distinct material specifications, volume profiles, and supplier relationships. Passenger cars represent a substantial portion of overall demand, while light and heavy commercial vehicles contribute specialized requirements driven by durability thresholds, duty cycles, and fleet electrification timelines. Applications spanning chassis, body, engine, HVAC, and infotainment systems each impose unique performance criteria, ranging from vibration resistance and temperature tolerance to data integrity and electromagnetic shielding. Our research decomposes these demand streams in detail, providing procurement and strategy teams with the granularity needed to align product development and sourcing plans with end-market realities.
Competitive Landscape: Consolidation, Specialization, and Strategic Positioning
The automotive wire and cable market features a concentrated but diverse supplier base, with the top three players accounting for approximately 25 percent of industry revenue and the top five reaching roughly 33 percent. This concentration indicates that scale, technical capability, and global manufacturing footprints confer meaningful advantages, while also leaving room for specialized firms that compete on innovation, regional proximity, or application-specific engineering. The leading companies in this space are pursuing differentiated strategies that reflect their geographic origins, product portfolios, and customer relationships.
Furukawa Electric Co., Ltd., headquartered in Tokyo, Japan, supplies high-performance wiring harnesses and specialty cables designed for electric vehicles and autonomous driving systems. Its product emphasis on advanced signal and power transmission aligns with the increasing complexity of in-vehicle networks. Southwire Company, based in Carrollton, Georgia, United States, produces and supplies automotive wire and cable solutions including power cables and harness components, serving a broad customer base with established manufacturing capacity and distribution reach. TE Connectivity, with headquarters in Schaffhausen, Switzerland, manufactures a wide range of wire and cable products including sensor cables, power cables, and assemblies for automotive applications, leveraging its cross-industry engineering expertise to serve demanding sensor and connectivity requirements.
Yazaki Corporation, also headquartered in Tokyo, Japan, is recognized as a global leader in wire harnesses, automobile wires and cables, battery cables, and in-vehicle network systems, maintaining deep integration with vehicle manufacturers across multiple continents. Leoni AG, based in Nuremberg, Germany, has historically offered wiring systems and automotive cable solutions through dedicated manufacturing and product lines for automotive wiring. Sumitomo Electric Industries, Ltd., located in Osaka, Japan, supplies high-voltage automotive wires and cables with a focus on EV and powertrain applications, reflecting the strategic importance of electrical architecture in next-generation platforms. Coroplast Fritz Müller GmbH & Co. KG, headquartered in Neumünster, Germany, develops and produces wire and cable solutions for automotive, industrial, and mechanical applications through its Coroflex brand, combining material science capabilities with application engineering.
Recent corporate activity illustrates how the competitive landscape is evolving beyond organic growth. In July 2025, Leoni AG's Automotive Cable Solutions division was fully acquired by TIME Interconnect, a subsidiary of Luxshare-ICT, and integrated into the Time Interconnect Group. This transaction signals a broader trend of consolidation and capability aggregation, as larger electronics and interconnect ecosystems absorb specialized cable expertise to offer more comprehensive solutions to vehicle manufacturers. More recently, in June 2026, the Coroplast Group showcased innovative e-mobility solutions, including wire harness tapes and cable management systems for battery and EV applications, at the Battery Show Europe. Such trade show participation highlights how material and component suppliers are strengthening their visibility around electrification-specific products, where insulation, thermal management, and space optimization are becoming critical purchase criteria.
For strategists, the competitive environment presents both opportunities and risks. Suppliers that can demonstrate proven performance in high-voltage environments, deliver consistent quality across global production sites, and respond rapidly to design changes will be positioned to capture premium contracts. At the same time, consolidation may alter supply continuity, pricing dynamics, and negotiation leverage. Our report includes a detailed competitive analysis that maps company capabilities, recent strategic moves, and market share distributions, equipping leadership teams with the context needed to evaluate supplier relationships and identify potential partnership or diversification strategies.
Regulatory and Material Dynamics Shaping Cost Structures and Design Choices
Market growth does not occur in a regulatory vacuum. Automotive cable specifications are increasingly governed by rigorous safety and environmental standards that influence material selection, testing protocols, and total cost of ownership. European regulations are increasingly mandating halogen-free cable materials that do not release toxic gases when burned, protecting vehicle occupants and first responders. This regulatory trajectory has pushed manufacturers to adopt new insulation compounds that achieve flame resistance ratings exceeding 850°C, meeting updated safety standards adopted in over 35 automotive manufacturing countries. These developments directly affect formulation choices, supplier qualification processes, and the cost profile of wiring assemblies, especially in vehicles destined for markets with stringent fire safety and occupant protection requirements.
At the technical standard level, UNECE WP.29 regulations and ISO 6722 standards govern automotive cable specifications for material composition and performance testing. Compliance with these frameworks is not merely a certification exercise; it shapes engineering design cycles, validation timelines, and the ability to scale production across multiple vehicle programs. As manufacturers broaden their geographic footprints, harmonizing cable specifications across jurisdictions becomes a strategic priority, and suppliers that can provide globally compliant solutions with consistent performance data gain a measurable advantage.
Material costs remain another critical variable. Copper, a foundational input for automotive wiring, has experienced notable price fluctuations. As of late March 2026, reference market prices showed copper at about 5.44 USD per pound on Trading Economics, down from its January 2026 all-time high of 6.58 USD per pound. While this moderation may ease short-term input pressure, the broader volatility underscores the importance of hedging strategies, inventory planning, and design optimization. Lightweight alternatives, optimized conductor layouts, and advanced insulation technologies can help mitigate raw material exposure, but these options require careful evaluation against performance, reliability, and certification requirements. Our research examines how material price dynamics interact with product design, supplier negotiations, and regional procurement strategies, enabling finance and operations teams to build more resilient cost models.
What the Full Research Delivers: Practical Intelligence for 2026 Planning
This market research is built for executives who need to move from high-level awareness to precise decision-making. The study combines historical analysis with forward-looking forecasts, segmentation breakdowns, competitive profiling, and regulatory context into a single integrated framework. While this preview highlights the strategic themes and industry structure shaping the automotive wire and cable market, the full report provides the deeper data architecture required to operationalize insights across procurement, product strategy, and market entry planning.
Specifically, the report delivers detailed segmentation analysis across application categories, vehicle types, and propulsion technologies, allowing readers to identify the demand pools most relevant to their portfolio and regional focus. It maps revenue evolution across the forecast horizon, highlighting growth inflection points and the relative contribution of each segment to overall market expansion. The competitive section goes beyond corporate descriptions to assess positioning, capability overlap, and strategic implications of recent transactions and product launches. Regulatory and material analysis is integrated with market dynamics so that compliance requirements and input cost trends can be interpreted in the context of pricing, sourcing, and engineering decisions.
To support practical application, the research includes structured exhibits and scenario-friendly frameworks that can be adapted to internal planning processes. These materials are designed to help teams answer questions such as where to prioritize supplier qualification efforts, how to anticipate volume shifts associated with electrification timelines, which application areas present the strongest growth opportunities, and how regulatory divergence across regions may influence global sourcing architectures. By combining quantitative forecasts with qualitative industry interpretation, the study aims to reduce uncertainty in capital allocation, inventory strategy, and product development sequencing.
Strategic Takeaways for Leadership Teams
As organizations finalize their 2026 priorities, several strategic implications emerge from the current market structure. First, the growth trajectory of the automotive wire and cable sector reflects durable demand tied to vehicle complexity rather than short-term cyclical factors. Even with fluctuations in production schedules, the long-term requirement for reliable power distribution, sensor connectivity, and safety-compliant cabling continues to expand. Second, the mix of conventional and new energy vehicles is reshaping product specifications and supplier expectations, making technical capability in high-voltage and advanced insulation systems increasingly valuable. Third, consolidation activity and the growing emphasis on e-mobility-specific materials suggest that supply chain strategies should account for both scale advantages and specialized innovation.
Fourth, regulatory mandates around halogen-free materials and internationally recognized cable standards are becoming embedded in design and procurement requirements, which means compliance capabilities should be evaluated alongside price and delivery performance. Fifth, raw material price volatility, exemplified by recent copper market movements, reinforces the need for flexible sourcing models and engineering strategies that reduce exposure without compromising reliability. Taken together, these dynamics point to a market where informed positioning can create meaningful competitive advantage, while reactive or undifferentiated approaches may increase cost and supply risk.
Access the Complete Intelligence
The automotive wire and cable market is entering a phase where strategic foresight and detailed data converge to determine execution quality. This article has outlined the major growth drivers, competitive forces, regulatory pressures, and material dynamics that our research examines in depth. To obtain the full segmentation breakdowns, regional demand detail, company-level market share analysis, and forecast exhibits necessary for 2026 decision-making, please visit the official PW Consulting research page and access the complete Automotive Wire and Cable Market study. The full report is designed to serve as a working intelligence asset for executive planning, procurement strategy, and product portfolio decisions across the forecast period.
For detailed analysis of this topic, please visit the official page: Automotive Wire and Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


