



PW Consulting: Wireless Antenna Market Hits $5.5B in 2025, Projects 5.3% CAGR Through 2032

Strategic Radio Frequency Foundations: Navigating the Wireless Antenna Market in 2026
The wireless connectivity landscape is entering a decisive phase. As enterprises across telecommunications, automotive, infrastructure, and industrial IoT scale their next-generation deployments, the antenna system has evolved from a passive peripheral to a critical strategic asset. The performance envelope of every network now hinges on antenna architecture, RF integration, and the ability to localize production while navigating volatile raw material economics. For leadership teams making capital allocation, vendor selection, and roadmap decisions in 2026, a rigorous, data-anchored view of the wireless antenna market is no longer optional—it is a prerequisite for defensible execution.
Content Management Tool Market
The market research published by PW Consulting maps this ecosystem with a longitudinal lens, tracing historical performance from 2020 through 2025 and projecting trajectory dynamics across the 2026 to 2032 forecast horizon. The narrative that emerges is one of steady structural expansion under intensifying technical and supply chain complexity. Total market revenue has demonstrated consistent year-over-year progression, moving from approximately 4.25 billion USD in 2020 to a 2025 base of 5.5 billion USD. The forward outlook points to continued scale with a projected 2026 valuation near 5.95 billion USD, followed by a measured climb toward 7.9 billion USD by 2032. This growth arc corresponds to a compound annual growth rate of approximately 5.3 percent across the full forecast window—indicating resilient demand that is neither speculative nor fragile, but rather rooted in multi-sector infrastructure build-out.
Worldwide Agricole Joystick Handle Market
Yet top-line trajectory is only the surface layer of strategic relevance. The real differentiation for enterprise decision-makers lies in understanding where value concentrates, which technology archetypes command premium positioning, and how regulatory shifts and commodity exposure will reshape cost structures. The following analysis previews the analytical dimensions of our full market research, illustrating how the study is engineered to convert market complexity into executable intelligence. The granular regional shares, segment-specific dollar allocations, and sub-segment performance splits are preserved within the complete dataset. This article serves as a strategic orientation—demonstrating methodology, competitive context, and decision-use cases—while directing readers to the full report for the precise figures required for board-level modeling and procurement planning.
Worldwide Industrial Pneumatic Brake Market
From Macro Trajectory to Strategic Signal
A market expanding at this cadence does not reward reactive purchasing or generic vendor evaluation. The wireless antenna space is shaped by overlapping demand vectors: continued densification of mobile networks, the proliferation of high-throughput Wi-Fi environments, the data collection requirements of radar and sensing architectures, and the antenna-intensive design of connected vehicle platforms. Each vector imposes distinct performance tolerances, form-factor constraints, and reliability expectations. Understanding how these application domains interact with evolving antenna types—MIMO, MISO, SIMO, and other specialized configurations—requires an analytical framework that ties architectural capability to market share dynamics without oversimplifying the trade-offs.
Our research is structured to make that connection actionable. Rather than presenting market size as an isolated number, the analysis develops a multi-dimensional segmentation that reveals how demand patterns diverge across technology classes, deployment environments, and geographic operating conditions. This approach allows strategists to identify where growth is genuinely structural versus where it reflects temporary project cycles. It also clarifies how concentration dynamics shape negotiation leverage, supplier risk, and long-term pricing behavior. With the top five firms collectively accounting for roughly 46 percent of market revenue and the top three approaching 42 percent, the competitive environment exhibits meaningful consolidation alongside a persistent tail of specialized innovators. That duality—concentrated scale players alongside targeted niche capabilities—defines the sourcing strategy challenge that many procurement and engineering leaders face in 2026.
What the Research Delivers: Practical Intelligence for Execution
The full market research is designed as a working instrument rather than a static snapshot. Beyond foundational sizing and trajectory modeling, the study integrates qualitative and quantitative layers that directly support planning across R&D, procurement, sales strategy, and risk management. The analytical content is organized to answer the operational questions that executives routinely raise when evaluating antenna-intensive programs:
- Technology architecture comparisons that clarify how different antenna configurations align with coverage, capacity, and integration requirements across 5G, Wi-Fi, radar, and connected mobility environments.
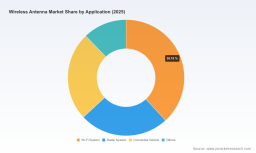
- Application-level demand mapping that traces how Wi-Fi systems, radar platforms, connected vehicle architectures, and adjacent use cases are influencing volume mix, specification expectations, and procurement timelines.
- Competitive profiling that moves beyond press-release narratives to examine product orientation, solution breadth, and strategic emphasis across leading incumbents and specialized suppliers.
- Recent corporate developments that illustrate how major players are adjusting manufacturing footprints, product portfolios, and partnership strategies in response to regional market pressures and infrastructure priorities.
- Macro and input-cost context that connects material exposure, regulatory actions, and commodity trends to realistic cost-structure scenarios for antenna and RF component programs.
This integrated design matters because antenna strategy is rarely a single-variable decision. Choosing a supplier, selecting an antenna type, or committing to a localization plan typically requires simultaneous consideration of performance specs, supply continuity, compliance exposure, and total cost of ownership. By combining market sizing with company-level development tracking and input-market monitoring, the research provides a basis for scenario planning rather than point forecasting. Decision-makers can pressure-test assumptions about lead times, pricing stability, and technology roadmaps against a common evidence base, reducing reliance on fragmented intelligence or supplier-derived narratives.
Competitive Dynamics: Scale Incumbents and Specialized Innovators
The competitive landscape in wireless antenna systems is characterized by companies that compete at different layers of the value chain. Several established network infrastructure leaders anchor the market through high-performing mobile network portfolios, passive antenna production, and RAN-integrated antenna solutions. These players continue to emphasize network-level performance, ecosystem coordination, and the ability to support large-scale operator deployments. At the same time, a parallel track of firms focuses on digital antenna advancement, intelligent optimization, and emerging optical or meta-structure approaches that anticipate next-generation base station requirements. The strategic implication is clear: antenna procurement and partnership decisions increasingly involve trade-offs between proven scale, integration depth, and technology optionality.
In addition to the large infrastructure-oriented players, the market includes specialists whose relevance is defined by product focus rather than total portfolio breadth. High-gain multi-protocol antenna and distributed antenna system providers serve deployment environments where densification and multi-standard compatibility are paramount. RF semiconductor and antenna module suppliers contribute at the component and integration level, where size, efficiency, and RF performance directly shape end-device and infrastructure design. Others concentrate on connectivity-intensive venues, stadium-grade infrastructure, and DAS-oriented architectures, while a distinct set of organizations targets IoT, cellular modules, and broadband measurement systems. This pluralistic structure means that the optimal sourcing approach often depends on deployment context, and a single supplier relationship rarely satisfies every requirement.
Recent activity from core participants illustrates how strategy is being translated into operational moves. One major antenna systems producer has expanded local manufacturing in India through collaboration with electronics manufacturing partners, advancing toward full localization of passive antenna production by mid-2025 and bringing export-ready antennas into the market shortly thereafter. In parallel, another large technology provider has publicly showcased commercial achievements in digital antenna technology, emphasizing intelligent transformation for base station environments. Alongside these infrastructure-scale moves, specialized suppliers have secured multi-year programs tied to advanced Wi-Fi deployments and launched new high-gain antenna lines optimized for contemporary 5G and Wi-Fi environments. These developments are not isolated press items; they are indicators of where manufacturing proximity, product modernization, and application-specific engineering are being prioritized.
Our report surfaces these patterns in a structured competitive format, allowing readers to assess not only who the key players are, but how their recent actions signal shifts in capability, geographic emphasis, and product direction. Full company profiles, link references, and event-level tracking are available in the complete version of the study, supporting detailed vendor benchmarking and strategic fit analysis.
The 2026 Decision Environment: Materials, Regulation, and Resilience
Strategic planning for antenna-intensive programs in 2026 must account for input-market volatility and regulatory dynamics as first-order factors, not peripheral concerns. The materials ecosystem feeding RF and antenna manufacturing has shown significant price movement and geopolitical sensitivity. Copper, a core conductor and structural input across many antenna and RF designs, experienced notable price levels in 2025 with forward expectations pointing toward materially higher annual averages in 2026. At the same time, precious metal exposure continues to fluctuate, with palladium and gold prices reflecting recovery patterns and high-volatility trading ranges that influence component cost models, plating requirements, and broader electronics pricing sentiment.
These commodity trends become strategically meaningful when combined with regulatory actions affecting material availability. Export controls on selected rare earth elements and magnets introduced in 2025 have created additional licensing requirements and supply chain friction. Analysts expect these controls to contribute to production delays and cost pressure across semiconductor and RF antenna domains in 2026. For organizations dependent on specialized magnetics, rare-earth-informed components, or imported intermediate materials, the implication is not simply a pricing challenge but a planning challenge: lead-time assumptions, qualification cycles, and inventory strategies need to be re-evaluated in light of constrained and conditional supply.
This is precisely the context in which a structured market study adds value. The PW Consulting research incorporates macro and input-market indicators that help leadership distinguish between temporary fluctuation and structural cost shifts. By aligning market trajectory with material exposure and regulatory risk, the study enables more credible scenario analysis. Procurement teams can better anticipate where cost escalation is likely to persist; engineering leaders can weigh material-critical design choices with greater confidence; and executive teams can assess whether strategic options such as supplier diversification, design standardization, or regional sourcing are justified by the market environment rather than by speculation.
Using the Study to Strengthen 2026 Decisions
The practical value of this market research lies in how it connects external market conditions to internal decision processes. For telecom and infrastructure organizations, the study supports roadmap alignment between antenna capability selection and network transformation priorities, including Open RAN considerations, multi-protocol deployment needs, and densification strategies. For automotive and connected-vehicle stakeholders, it clarifies how antenna demand is integrating into mobility platforms and what product orientations are gaining commercial traction. For enterprises building out Wi-Fi and venue-grade connectivity, it highlights the relevance of high-gain and distributed antenna approaches while mapping recent contract and product activity in that segment. For industrial and IoT-focused teams, the study creates visibility into module-integrated antenna solutions and RF front-end trends that influence device form factors and performance targets.
Because the detailed segmentation data—regional shares, application splits, and technology-class allocations—are maintained in the full report, readers can use the complete dataset to build forecasts, budget models, and sourcing comparisons that reflect their specific operating context. The preview provided here intentionally preserves strategic direction while reserving the exact numerical breakdowns for the full publication. That design reflects a core principle of high-value market intelligence: the public-facing narrative demonstrates analytical credibility and relevance, while the precise figures that support competitive benchmarking and financial planning are delivered in the structured research product.
For organizations making antenna-related decisions in 2026, the strategic imperative is to move from general awareness to quantified readiness. That means understanding not just that the market is expanding, but where growth is concentrated, how competitive dynamics affect supplier leverage, and which external factors are most likely to alter cost and availability assumptions over the forecast period. It also means grounding those judgments in a consistent methodology that can be revisited as conditions change.
Closing Perspective
The wireless antenna market in 2026 presents a distinctive combination of steady growth, technological differentiation, and supply-side complexity. Demand is being sustained by broad infrastructure and connectivity imperatives, while competitive behavior and input-market conditions are reshaping the economics of participation. In this environment, effective strategy depends on intelligence that is both wide in scope and precise in execution. The full PW Consulting Wireless Antenna Market Research provides that foundation, offering executives a structured view of market size, segmentation dynamics, competitive moves, and material/regulatory risk factors that influence planning across the 2026 to 2032 horizon.
The complete edition includes the granular regional and application splits, technology-class allocations, and detailed company profiles required for rigorous benchmarking and financial modeling. We invite decision-makers, procurement leaders, and strategy teams to access the full report to retrieve the specific figures and structured datasets needed for board-ready analysis and actionable planning. In a market defined by both opportunity and volatility, depth of intelligence is the differentiator between reactive adaptation and disciplined strategic advantage.
For detailed analysis of this topic, please visit the official page: Wireless Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


