



PW Consulting: Instant Adhesive Market to Hit $344.8M by 2032, 6.58% CAGR Amid 2025's $215M Growth

Projecting the Instant Adhesive Market: A Strategic Blueprint for 2026 and Beyond
Introduction: The Adhesive Imperative in Modern Manufacturing
In the contemporary industrial landscape, bonding technologies have evolved from simple assembly aids to critical engineering components that dictate product performance, durability, and design flexibility. The instant adhesive market stands at the forefront of this transformation, serving as an essential enabler across sectors ranging from high-precision electronics to heavy-duty transportation manufacturing. As organizations navigate an increasingly complex global environment characterized by supply chain recalibrations, stringent environmental regulations, and shifting consumer expectations, the ability to make informed, data-driven decisions regarding adhesive procurement and investment has never been more vital.
Escape Door Control Unit Market
This comprehensive market research study examines the historical trajectory and future projections of the instant adhesive industry, offering a rigorous analytical framework designed to support executive decision-making through 2032. By synthesizing macroeconomic trends, competitive intelligence, raw material dynamics, and regulatory pressures, this report provides stakeholders with the actionable intelligence needed to position their organizations advantageously in a market projected to experience sustained growth.
Gasket Structure Keyboard Market
Market Trajectory: Navigating Growth Amid Volatility
The instant adhesive market has demonstrated remarkable resilience and expansion over the past half-decade, establishing a robust foundation for continued momentum. Historical data from 2020 through 2025 reveals a market that has not only recovered from disruptions but has accelerated its growth trajectory, reaching approximately 215.0 Million USD in the base year of 2025. This represents a significant evolution from the 163.15 Million USD recorded in 2020, underscoring the compound annual growth rate that has characterized the industry's maturation.
Worldwide Switch Expansion Joints (SEJ) Market
Looking ahead, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 6.58 percent, a figure that reflects both steady demand expansion and the industry's capacity to adapt to emerging technological and regulatory requirements. By 2026, market revenue is anticipated to reach 230.33 Million USD, climbing progressively to 344.8 Million USD by the close of the forecast horizon in 2032. This upward trajectory signals more than mere volume growth; it indicates a maturing market where value creation is increasingly tied to product innovation, application-specific formulations, and strategic geographic expansion.
Several structural factors underpin this growth outlook. The ongoing transition toward lightweight materials in transportation and automotive manufacturing continues to drive demand for high-performance bonding solutions that can replace traditional mechanical fasteners. Simultaneously, the electronics industry's relentless miniaturization and the medical sector's push for biocompatible, rapid-curing adhesion technologies create sustained pull factors across multiple end-use verticals. Companies that recognize these cross-industry demand signals and align their product development pipelines accordingly will be best positioned to capture disproportionate market share in the coming years.
Structural Composition: Demand Drivers Across Key Verticals
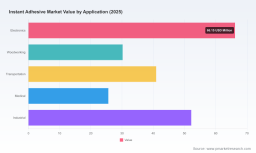
Understanding where instant adhesive demand concentrates is essential for strategic resource allocation and market entry timing. The application landscape reveals a diverse but clearly hierarchical set of consumption patterns that reflect broader industrial trends. Electronics represents a dominant consumption segment, driven by the sector's need for precise, high-speed bonding in component assembly, consumer devices, and increasingly sophisticated wearable technologies. The woodworking sector, while historically associated with slower-curing formulations, has embraced instant adhesive solutions for applications requiring rapid turnaround and strong initial tack in furniture manufacturing and cabinetry production.
Transportation applications continue to expand as original equipment manufacturers seek weight-reduction strategies and design flexibility that instant adhesives facilitate. This includes both traditional automotive manufacturing and the rapidly growing electric vehicle segment, where battery assembly and lightweight structural components demand specialized bonding chemistries. The medical sector represents another critical growth vector, with demand fueled by surgical device assembly, wound closure applications, and the development of increasingly sophisticated diagnostic equipment. Industrial applications broadly encompass manufacturing assembly, maintenance repair operations, and specialty bonding tasks that require rapid setting times without compromising ultimate bond strength.
From a product type perspective, the market is anchored by two principal categories. Cyanoacrylate-based instant adhesives command the largest share of the product landscape, reflecting their widespread adoption across consumer, industrial, and medical end uses due to their rapid curing characteristics and strong bonding performance on a variety of substrates. Epoxy-based instant adhesive formulations constitute a complementary segment, particularly valued in applications requiring higher temperature resistance, greater structural integrity, or specialized chemical resistance profiles. The interplay between these product categories creates a dynamic where formulators must continuously innovate to meet the diverging requirements of performance, safety, and cost-efficiency.
Geographic Distribution and Regional Dynamics
The geographic footprint of instant adhesive consumption reflects both established industrial bases and emerging growth corridors. North America represents a substantial revenue contributor, supported by mature manufacturing sectors, a strong electronics industry presence, and a healthcare market that demands advanced bonding solutions. Europe maintains a parallel position of significance, driven by its robust automotive and industrial manufacturing ecosystems, alongside increasing regulatory emphasis on environmental compliance that shapes product formulation strategies across the region.
Asia Pacific emerges as a particularly notable region in terms of market scale, reflecting the concentration of electronics manufacturing, rapid industrialization, and growing consumer markets across multiple economies. The region's expansive production capacity and increasing domestic consumption create a complex competitive environment where both multinational formulators and regional players vie for share. Latin America and the Middle East and Africa represent additional geographic dimensions, with growth potential tied to infrastructure development, industrial modernization initiatives, and gradually expanding manufacturing bases in select economies.
Regional dynamics are further complicated by divergent regulatory environments, varying raw material access, and differing labor cost structures that influence both product pricing and formulation priorities. Strategic market entry or expansion decisions require nuanced understanding of these regional characteristics rather than one-size-fits-all approaches. Companies that develop region-specific product portfolios and distribution strategies will find themselves better equipped to navigate the heterogeneous demands of global instant adhesive markets.
Competitive Landscape: Architects of Market Evolution
The instant adhesive market operates within a moderately concentrated competitive structure. Analysis of the competitive landscape reveals a market environment where the top three players command approximately 19.4 percent of total revenue, while the top five collectively account for roughly 22.5 percent. This concentration profile suggests a market that accommodates both established multinational corporations with extensive research and development capabilities and smaller, specialized formulators that compete through niche application expertise, regional distribution strength, or proprietary formulation technologies.
Among the prominent organizations shaping this landscape, Henkel AG and Co KGaA stands as a defining presence through its Loctite-branded instant adhesive and cyanoacrylate portfolio, which serves industrial, medical, and automotive applications with a reputation for performance reliability. The company's global distribution network and sustained investment in application-specific product development reinforce its position as a benchmark competitor. 3M Company maintains a parallel stature through its Scotch-Weld and Super-Fast instant adhesive lines, catering to electronics, industrial bonding, and medical use cases with a portfolio that emphasizes both performance and accessibility across diverse customer segments.
Huntsman Corporation contributes to the competitive ecosystem by supplying instant adhesive resins and solutions tailored for general industrial and construction bonding applications, leveraging its broader materials science expertise to support large-scale manufacturing customers. H.B. Fuller Company markets a diversified portfolio of instant adhesives designed for quick-bonding industrial and specialty applications, with recent strategic moves underscoring its commitment to capacity expansion and regional market servicing. Bostik SA, operating under the Arkema Group umbrella, develops and supplies instant engineering adhesives including the Born2Bond series, positioning its offerings for demanding environments that require robust performance under stress or temperature variation.
Toagosei Co Ltd brings specialized expertise in cyanoacrylate instant adhesives through its Aron Alpha brand, targeting industrial manufacturing markets with formulations optimized for production-line efficiency. Pidilite Industries Limited extends its reach across consumer, industrial, and craft bonding segments through the Fevikwik instant adhesive line, demonstrating the brand strength that can emerge from effective product positioning in both professional and retail channels. Permabond LLC, with its North American operations anchored from a UK base, specializes in high-performance instant adhesives designed for engineering and industrial use cases where bond reliability is paramount. Dymax Corporation rounds out the competitive array with its focus on UV and light-cure instant adhesives, particularly serving electronics and medical assembly applications where curing precision and speed are critical operational requirements.
Recent corporate developments highlight the strategic dynamism within this competitive field. In May 2026, H.B. Fuller Company executed significant capacity expansion initiatives, opening a new state-of-the-art facility in Cairo, Egypt, that adds manufacturing capacity for pressure-sensitive and non-pressure-sensitive adhesives serving over thirty market segments, including industrial adhesives. Concurrently, the company expanded its site in the United Arab Emirates to enhance manufacturing capabilities for waterproofing, woodworking, and industrial adhesives. These investments signal a deliberate strategy to strengthen regional manufacturing presence, reduce supply chain vulnerabilities, and position the company to capture growth in emerging markets with localized production capabilities.
The competitive dynamics extend beyond corporate strategy to encompass the broader forces that shape market access and product differentiation. Formulators must balance the imperative to innovate with the practical constraints of cost management and regulatory compliance, creating an environment where competitive advantage is increasingly derived from integrated solutions rather than commodity product offerings alone.
Raw Material Dynamics and Cost Structure Considerations
The economics of instant adhesive production are fundamentally shaped by raw material cost structures and supply chain volatility. Industry data indicates that raw material prices account for approximately 86 percent of the final instant adhesive product price, a proportion that makes feedstock cost management a central concern for profitability and pricing strategy. Monomer cost swings, in particular, exert significant influence on pack pricing, requiring manufacturers to maintain agile procurement strategies and, where feasible, hedging mechanisms to mitigate exposure to commodity price fluctuations.
During March 2026, stable but firm feedstock costs, particularly for methanol and acetone, contributed to steady firm pricing of cyanoacrylate in the USA market. This pricing environment reflects the interplay between raw material availability, production capacity utilization, and demand strength, creating conditions where margin preservation depends on operational efficiency and value-added product positioning rather than simple volume expansion. Companies that have invested in vertical integration, long-term supplier agreements, or alternative feedstock sourcing strategies are better insulated against the periodic cost pressures that characterize this segment of the materials market.
The sensitivity of final product pricing to raw material inputs also shapes competitive dynamics in meaningful ways. Larger, well-capitalized manufacturers may possess advantages in procurement scale and supply chain diversification, while smaller players may need to compete through service differentiation, specialized technical support, or regional market focus. Understanding these cost structure dynamics is essential for competitive analysis, pricing strategy development, and investment planning across the instant adhesive value chain.
Regulatory Pressures and Formulation Evolution
The instant adhesive industry operates within an increasingly complex regulatory environment that influences product formulation, market access, and compliance cost structures across multiple geographies. In the United States, Canada, and Australia, strict volatile organic compound regulations and occupational-health requirements compel formulators to develop low-VOC and low-odor instant adhesives, raising compliance costs while simultaneously creating opportunities for companies that can deliver compliant products without sacrificing performance. These regulatory pressures are not static; they evolve as governments and regulatory bodies refine their approaches to chemical safety, emissions control, and workplace health protection.
Across global markets, formulators are shifting toward low-VOC and REACH-compliant instant adhesives to meet tightening environmental standards. This shift represents more than a compliance exercise; it reflects a broader industry movement toward sustainable chemistry and environmentally responsible manufacturing practices that resonate with downstream customers and end consumers alike. Companies that proactively invest in compliant formulation development and maintain robust regulatory monitoring capabilities will find themselves with competitive advantages in markets where environmental compliance is increasingly a prerequisite for supply chain participation.
The medical sector introduces an additional regulatory dimension. New medical-grade cyanoacrylate formulations are being developed without CMR ingredients to comply with safety requirements for heat-resistant medical device applications. This formulation evolution addresses the stringent biocompatibility and safety standards that govern medical device manufacturing, creating specialized product opportunities for formulators with the technical expertise and regulatory documentation capabilities to serve this demanding segment. The intersection of regulatory compliance and product performance in medical applications underscores the value of specialized knowledge and the premium that sophisticated customers place on reliably compliant solutions.
These regulatory trends have strategic implications beyond product development. They influence market entry timing, geographic expansion feasibility, and the competitive positioning of companies with varying levels of regulatory infrastructure and expertise. Organizations that treat regulatory compliance as a strategic capability rather than a peripheral concern will be better equipped to navigate the evolving landscape and capitalize on the opportunities created by regulatory-driven product differentiation.
What This Report Delivers: Analytical Depth and Strategic Utility
This market research study is structured to provide executives, strategic planners, and industry analysts with a comprehensive yet actionable understanding of the instant adhesive market's current state and future trajectory. The report integrates macroeconomic market sizing and growth projections with detailed segmentation analysis, competitive intelligence, and an examination of the regulatory and raw material dynamics that shape market conditions. By situating quantitative data within a qualitative framework of industry forces, the study enables readers to move beyond surface-level market observations toward a nuanced grasp of the strategic factors that will drive performance over the forecast period.
The report's segmentation analysis provides visibility into how revenue distributes across product types, application verticals, and geographic regions, enabling readers to identify where demand concentration creates opportunities and where fragmentation requires targeted strategies. The competitive landscape assessment goes beyond company profiles to examine strategic positioning, recent corporate developments, and the structural characteristics of market concentration that influence competitive behavior and market access. The inclusion of raw material dynamics and regulatory trend analysis ensures that readers understand the cost and compliance environments that underpin product economics and market entry feasibility.
Importantly, this report is designed to support decision-making rather than merely describe market conditions. The analytical framework presented enables stakeholders to assess growth opportunities, evaluate competitive threats, plan capacity investments, and develop product strategies aligned with market realities. Readers seeking a comprehensive understanding of the instant adhesive market's opportunities and challenges will find the full report's detailed data sets, segmentation breakdowns, company profiles, and forward-looking analysis essential to formulating informed strategic responses.
Positioning for 2026 and the Decade Ahead
The instant adhesive market enters the 2026 to 2032 forecast period with a foundation of established growth, evolving competitive dynamics, and a regulatory and cost environment that demands strategic agility. The projected compound annual growth rate of 6.58 percent reflects sustained demand across multiple industrial sectors, but realizing the benefits of this growth requires more than passive market participation. Organizations must actively monitor raw material cost trajectories, adapt product portfolios to meet regulatory and performance requirements, and position themselves within the competitive landscape in ways that leverage their specific capabilities and market access advantages.
The companies that thrive in this environment will be those that treat market intelligence as a strategic asset, integrating deep understanding of segmentation trends, regional dynamics, raw material economics, and regulatory developments into coherent decision-making frameworks. Whether evaluating market entry opportunities, assessing competitive threats, planning capacity investments, or developing product innovation pipelines, access to comprehensive and timely market intelligence proves indispensable. This report is designed to provide exactly that foundation, offering the analytical rigor and strategic perspective needed to navigate the instant adhesive market with confidence through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Instant Adhesive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


