



PW Consulting: Rigid Endoscopes Market Hits $1.25B in 2025, Poised for 5.5% CAGR to 2032

Strategic Horizons: Navigating the Rigid Endoscopes Market in 2026 and Beyond
The landscape of minimally invasive surgery is undergoing a profound transformation, driven by technological innovation, stringent regulatory frameworks, and shifting reimbursement models. As organizations plan their capital allocation and product development strategies for 2026, the need for precise, actionable intelligence regarding rigid endoscopes has never been more critical. This article serves as a strategic primer, outlining the broader market trajectory and the key dynamics that will define the competitive landscape. It is designed to equip executive leadership with the contextual awareness necessary to interpret complex market signals, while underscoring the necessity of deeper granular analysis for final decision-making.
Worldwide RF Needles Market
Our latest comprehensive market research offers a detailed roadmap through this evolving ecosystem. The data indicates a resilient growth trajectory, with the global market valuation reaching significant benchmarks in the base year of 2025. Looking forward, the forecast period extending to 2032 suggests a sustained compounding growth rate that outpaces many traditional medtech segments. This momentum is not merely a function of volume but is deeply rooted in the value proposition of improved patient outcomes, reduced hospital stays, and the integration of advanced imaging technologies into standard surgical workflows.
Worldwide Smoke Mechanical Damper Market
Market Trajectory and Macro Economic Indicators
Migraine Wearables Market
Understanding the top-line growth is essential, but interpreting the underlying velocity is where strategic value is generated. Historical data from 2020 through 2025 demonstrates a consistent upward trend, recovering from global supply chain disruptions and emerging stronger with renewed investment in surgical infrastructure. The market revenue unit is tracked in USD Million, providing a standardized metric for cross-border comparison and investment appraisal.
For the forecast period spanning 2026 to 2032, the projected growth curve indicates a steady acceleration. The Compound Annual Growth Rate (CAGR) is estimated to sustain momentum over this seven-year horizon, suggesting that demand drivers are structural rather than cyclical. By the end of the forecast window, the total market size is anticipated to reach new heights, reflecting the cumulative effect of adoption in emerging economies and the premiumization of devices in mature markets. This macro view provides the boundary conditions for any strategic plan, setting the stage for more nuanced segmentation analysis.
Segmentation Dynamics: Type and Application Interplay
While the aggregate numbers provide the horizon, the true strategic opportunities lie within the segmentation splits. The market is categorized by distinct device types, each serving specific clinical needs. Laparoscopes continue to represent a substantial portion of the revenue mix, reflecting their ubiquity in general surgical procedures. Arthroscopes maintain a strong foothold, particularly driven by the sports medicine and orthopedic sectors. Cystoscopes and gynecological endoscopes form critical niches, often tied to specific reimbursement codes and procedural volumes.
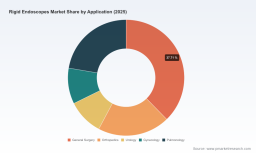
Beyond device classification, the application landscape reveals where value is being captured. General surgery remains a dominant application area, absorbing a significant share of procedural usage. Orthopedics and pulmonology represent high-growth vectors, leveraging advanced visualization for complex interventions. Urology and gynecology continue to be steady contributors, with innovation focused on ergonomics and durability.
It is crucial for stakeholders to recognize that these segments do not grow in isolation. Cross-segment synergies, such as the adoption of 4K imaging across both laparoscopes and arthroscopes, create platform opportunities for manufacturers. However, detailed revenue breakdowns for each specific type and application segment are complex and subject to regional variations. To obtain the precise valuation figures for each sub-segment and understand the internal share distribution, stakeholders are encouraged to consult the full dataset available in our complete market report.
Competitive Landscape and Key Players
The rigid endoscopes market is characterized by a moderately concentrated competitive environment. The presence of established multinational corporations alongside specialized niche players creates a dynamic ecosystem where innovation speed and regulatory compliance are key differentiators. Market concentration metrics suggest that a handful of major entities command a significant portion of the market share, indicating high barriers to entry and strong brand loyalty among healthcare providers.
Key Market Participants
- KARL STORZ SE & Co. KG : Based in Tuttlingen, Germany, this organization remains a cornerstone of the industry. Their portfolio encompasses a wide range of rigid endoscopes, including HOPKINS® telescopes, cystoscopes, and laparoscopes. They serve diverse applications spanning gynecology, ENT, and general surgery, maintaining a reputation for optical quality and system integration.
- Stryker Corporation : Headquartered in Kalamazoo, Michigan, United States, Stryker leverages its Endoscopy and Surgical Visualization portfolio to deliver rigid endoscopes and hysteroscopes. Their focus extends to laparoscopic, urologic, and gynecologic procedures, often integrating visualization towers that enhance the utility of the scopes themselves.
- Olympus Corporation : Operating out of Tokyo, Japan, Olympus provides critical rigid endoscopy solutions including ENDOEYE® and rigid laparoscopes. Their strength lies in endoscopic surgery and minimally invasive procedures, benefiting from a global distribution network and a strong heritage in optical engineering.
- Smith & Nephew plc : With headquarters in London, United Kingdom, Smith & Nephew specializes in orthopedic and sports medicine applications. They offer rigid arthroscopes and 4K optimized scopes, targeting high-precision environments where visual fidelity directly impacts surgical outcomes.
- B. Braun Melsungen AG : Based in Melsungen, Germany, this company produces Aesculap-branded rigid endoscopes. Their focus on laparoscopy and minimally invasive surgery aligns with the broader trend toward standardizing instrument quality across hospital networks.
These companies are not merely selling hardware; they are selling ecosystems. The competition is increasingly shifting toward service models, training, and compatibility with digital operating room infrastructure. Understanding the specific market share percentages and the growth rates of each individual player requires a depth of analysis that goes beyond corporate profiles. Our full report details the competitive positioning, recent strategic moves, and financial health indicators that allow for a granular competitive benchmarking exercise.
Industry Dynamics and Regulatory Pressures
One of the most significant factors influencing cost structures and procurement strategies in 2026 is the regulatory environment surrounding reprocessing and sterilization. The days of simple cleaning protocols are evolving into complex, validated processes that add substantial operational costs to healthcare facilities.
Reprocessing and Compliance Costs
The ANSI/AAMI ST91:2021 standard for flexible and semi-rigid endoscope processing has implications that extend to rigid endoscopes as well. This standard increases the rigor of reprocessing requirements, directly impacting the total cost of ownership for hospitals. Industry analysis suggests that these enhanced reprocessing requirements increase costs to approximately 216 USD per procedure. This figure is a critical input for hospital administrators evaluating the switch between reusable and disposable options, and for manufacturers designing scopes that must withstand more aggressive sterilization cycles.
Furthermore, regulatory bodies continue to issue updated recommendations. In 2024, the FDA recommended that for reusable endoscopes, organizations transition to more robust reprocessing methods. Techniques such as ethylene oxide sterilization or gas plasma are becoming preferred standards to mitigate infection risks. These mandates drive demand for scopes made from materials compatible with harsher sterilization methods, potentially altering the material science roadmap for device manufacturers.
Strategic Implications of Regulation
- Cost Structure Reassessment : Procurement teams must factor in the recurring cost of sterilization per procedure when calculating the lifetime value of reusable rigid endoscopes.
- Product Design Innovation : Manufacturers are incentivized to develop scopes that are durable enough to withstand frequent gas plasma or ethylene oxide exposure without degradation of optical quality.
- Disposable vs. Reusable Debate : As reprocessing costs rise, the economic break-even point between single-use and reusable devices shifts, opening new market segments for disposable rigid endoscopes in specific high-turnover settings.
These dynamics create a complex web of operational constraints that influence market growth. While the regulatory environment poses cost challenges, it also drives standardization and safety, which can fuel long-term adoption confidence. Detailed analysis of how these regulatory costs impact specific regions and hospital types is available within the regional and dynamics sections of our comprehensive study.
Regional Growth Vectors
Geographically, the market exhibits distinct maturity levels and growth potentials. North America continues to represent a substantial revenue base, driven by high procedure volumes and advanced healthcare infrastructure. Europe maintains a steady demand, influenced by public healthcare funding models and regulatory harmonization. Asia Pacific presents a compelling growth story, fueled by expanding surgical capacity and increasing access to minimally invasive techniques in developing economies.
Latin America and the Middle East and Africa regions, while smaller in absolute volume compared to the major three, offer niche opportunities for market penetration. Success in these regions often depends on local partnerships, pricing strategies tailored to diverse economic conditions, and training programs that build surgical competency.
It is important to note that regional revenue splits are sensitive to currency fluctuations, local reimbursement policies, and the pace of technology adoption. A high-level view confirms that the global market is diversifying, but the specific contribution of each region to the total market size varies year over year. For precise regional valuations and forecasts, our full report provides the necessary granularity to support market entry strategies or capacity expansion plans.
Strategic Imperatives for 2026 Decision Makers
As we move deeper into the forecast period, several strategic imperatives emerge for stakeholders operating in the rigid endoscopes market.
1. Portfolio Optimization and Technology Integration
Companies must evaluate whether their product portfolios are aligned with the shifting application demands. The integration of 4K and potentially 3D visualization capabilities is no longer a differentiator but a baseline expectation in many orthopedic and general surgery settings. Investment decisions should focus on platforms that can evolve with software upgrades, extending the lifecycle of hardware assets.
2. Cost Management and Value Proposition
With reprocessing costs becoming a visible line item for healthcare providers, manufacturers have an opportunity to demonstrate value beyond the purchase price. Offering comprehensive service contracts, sterilization compatibility guarantees, and efficiency tools can differentiate a brand in a concentrated market. The ability to prove total cost of ownership savings will be a key sales enabler.
3. Navigating Concentration and Competition
Given the market concentration levels, new entrants or smaller players must identify underserved niches or innovate significantly to capture share from the incumbents. Strategic partnerships, licensing agreements, or acquisitions may be viable paths to accelerate market presence. Understanding the exact market share distribution among the top five players is vital for assessing the feasibility of competitive moves.
4. Regulatory Agility
Proactive engagement with regulatory standards regarding reprocessing and sterilization will mitigate risk. Companies that design for compliance with the latest FDA recommendations and AAMI standards will reduce friction in the procurement process for their customers. This agility can serve as a trust signal in tenders and contract negotiations.
Conclusion: The Value of Deep Intelligence
The rigid endoscopes market in 2026 is defined by a confluence of steady macroeconomic growth, technological maturation, and evolving operational constraints. The projected growth rate of 5.5 percent over the forecast period underscores a healthy demand environment, but realizing success within this environment requires more than just acknowledging the top-line numbers.
Stakeholders need to understand the interplay between segmentation splits, regional nuances, and the specific financial positions of key competitors like KARL STORZ, Stryker, Olympus, Smith & Nephew, and B. Braun. They need to quantify the impact of reprocessing regulations on their specific cost models and identify which application segments offer the highest margin potential.
This article has outlined the strategic landscape, highlighting the critical areas of focus. However, to build a robust business plan or investment thesis, one requires the specific revenue figures, detailed segmentation splits, and precise regional data that underpin these trends. The macro narrative provides direction, but the micro data provides the map.
PW Consulting's full market research report delivers this granular intelligence. It dissects the market size from 2020 through the forecast horizon to 2032, offering detailed breakdowns by type, application, and region. It analyzes the competitive intensity and provides the data necessary to validate strategic assumptions.
For organizations ready to move from general awareness to precise execution, accessing the complete dataset is the logical next step. The depth of insight required to navigate the complexities of the rigid endoscopes market is available in our comprehensive publication.
For detailed analysis of this topic, please visit the official page: Rigid Endoscopes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


