



PW Consulting: Metrology Software Market Hits $770M in 2025, 6.8% CAGR to 2032

Metrology Software Market 2026: Navigating the Digital Thread with Precision Intelligence
A Strategic Briefing by PW Consulting
The metrology software landscape has crossed a decisive inflection point. What was once a niche enablement layer for coordinate measuring machines (CMMs) and optical scanners has matured into a central nervous system for digital manufacturing. Between 2020 and 2025, the global market expanded from approximately 620 million USD to 770 million USD, reflecting a compound annual growth rate of 6.8 percent projected through 2032. This trajectory is not merely a function of incremental hardware adoption; it signals a structural shift toward software-defined quality, where measurement data, compliance workflows, and cross-site collaboration are orchestrated through integrated platforms rather than isolated instruments.
Industrial Flash Memory Chip Market
As enterprises map their 2026 operating plans, the question is no longer whether to invest in metrology software but how to prioritize capabilities that compound value across the digital thread. Our latest market research sits at the intersection of this planning cycle. It is designed to translate macro momentum into decision-grade intelligence, helping procurement leaders, R&D directors, and quality executives separate signal from vendor narrative. This article previews the analytical architecture of the study, outlining the strategic lenses, competitive dynamics, and operational checkpoints that will shape software selection, integration roadmaps, and renewal strategies in the months ahead.
Whole House Customization Service Market
The commercial baseline is unambiguous. Forecasts indicate the market will reach 801.34 million USD in 2026 and continue climbing toward 1.12 billion USD by 2032, with the peak growth corridor concentrated between 2026 and 2029. Several structural forces are compressing the decision window. First, the cost of quality failure is rising as tolerance stacks tighten in high-value assemblies, pushing manufacturers to treat measurement not as a post-production audit but as a design-to-shop-floor feedback loop. Second, shop-floor labor economics are reshaping the software value proposition. Training overhead and license economics weigh disproportionately on small and mid-sized enterprises, making renewal decisions increasingly sensitive to usability, onboarding friction, and the breadth of automated support. Third, regulatory and standards expectations are evolving faster than legacy reporting workflows can absorb, with automated metrology systems and integrated reporting emerging as practical levers to streamline compliance documentation and reduce manual reconciliation.
These dynamics converge on a single strategic imperative: metrology software must be evaluated as an enterprise data asset, not a point solution. The firms that will capture disproportionate value in 2026 are those that can align software architecture with data governance, interoperability, and cross-functional access patterns. Our report frames this evaluation through four interconnected lenses.
Strategic Framework: From Baseline Intelligence to Acquisition Roadmaps
PW Consulting’s Metrology Software Market study is structured to support sequential decision-making rather than one-off benchmarking. The methodology maps historical momentum from 2020 through 2025 against a 2026 to 2032 forecast horizon, allowing readers to test scenario sensitivity around adoption curves, pricing pressure, and deployment models. The research is calibrated for practical use across multiple planning surfaces: capital allocation, vendor shortlists, integration sequencing, and compliance readiness.
Core Analytical Dimensions
- Market Architecture: The study decomposes the market into its functional building blocks, including calibration software, measurement data management software, and compliance and reporting software. Rather than treating these categories in isolation, the analysis traces how each contributes to data flow, decision latency, and audit readiness across the product lifecycle.
- Application Mapping: Software value is assessed against the operational contexts where measurement matters most, from manufacturing and production environments to quality assurance and testing, as well as research and development. The report examines how workload mix, throughput expectations, and tolerance requirements influence feature priorities and deployment complexity.
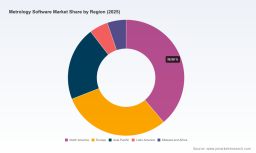
- Geographic and Structural Context: Regional revenue distribution and market concentration metrics are presented to illuminate where adoption is most mature and how vendor influence is distributed. These indicators help readers anticipate pricing behavior, service expectations, and the intensity of competitive rivalry in different operating environments.
- Forecasting Under Uncertainty: The forecast period from 2026 to 2032 is modeled to account for variability in cloud adoption, interoperability requirements, and regulatory pacing. The goal is not to produce a single deterministic number but to give decision-makers a defensible range for planning and stress-testing investment timing.
Practical Outputs for 2026 Planning
Beyond macro sizing, the report delivers operational artifacts that can be used immediately in sourcing and architecture discussions. These include deployment pathway comparisons, integration checkpoint lists, vendor evaluation scorecards, and compliance alignment guidance. The study also addresses the growing tension between on-prem data management and managed cloud options, including the emergence of SaaS models that centralize measurement data while reducing the internal burden of server setup and maintenance. For organizations considering outsourcing data management infrastructure, these pathways carry direct implications for total cost of ownership, security posture, and the speed at which multi-site collaboration can be enabled.
Competitive Dynamics and the 2026 Product Cycle
The market structure remains moderately concentrated, with leading participants holding a meaningful share of revenue while leaving substantial room for specialist differentiation. This fragmentation is strategic: it means procurement teams can choose between broad platforms with multi-device coverage and narrower tools optimized for specific inspection workflows or device ecosystems. The report profiles key participants and their positioning, with particular attention to how recent product cycles are reshaping buyer expectations.
Platform Direction in the Field
Two illustrative trajectories stand out in the current cycle. InnovMetric continues to push its universal 3D metrology software platform as a connective layer for dimensional inspection, point-cloud-based analysis, and multi-device compatibility across industrial manufacturing environments. Its recent march toward cloud-enabled data centralization reflects a broader industry move to make measurement data more portable, searchable, and collaborative across sites. Verisurf Software, meanwhile, has reinforced a model-based metrology approach that ties dimensional inspection, assembly guidance, reverse engineering, and interoperability with CMMs, scanners, and CAD systems into a single workflow. Its emphasis on device compatibility and data interchange points to an increasing buyer demand for standards-based connectivity rather than proprietary silos.
These directions are not merely feature lists. They reveal the market's emerging rules of competition: breadth of device support, the quality of data centralization, the degree of standards alignment, and the ability to reduce the manual effort required to move measurement information from the shop floor into enterprise systems. The report evaluates these competitive signatures against buying criteria that matter in 2026, including integration friction, training load, and the resilience of the digital thread across design, production, and quality functions.
2026 Dynamics: Compliance, Cloud, and the Cost of Doing Nothing
The most consequential shifts in the market are not visible in headline sizing alone. They appear in the day-to-day operational pressures that influence which software shortfalls become acceptable and which become disqualifying. Three dynamics dominate the planning conversation.
Regulation as a Catalyst for Software Maturity
Regulatory and standards expectations are increasingly reshaping metrology software requirements. Manufacturers are encountering situations where automated metrology systems with integrated reporting aligned to regulatory guidelines help streamline compliance processes, reducing the time spent on manual assembly of evidence and traceability records. At the same time, software in metrology for the digital age introduces compliance challenges related to emerging technologies such as AI, IoT, and cloud computing. Buyers must weigh the upside of automation and connectivity against the need to demonstrate data integrity, auditability, and controlled access. The report examines these trade-offs in depth, mapping where software capabilities can accelerate compliance readiness and where they introduce new governance obligations.
The Cloud Debate and Data Centralization
Data management architecture is becoming a competition in its own right. The rise of cloud SaaS models reflects a practical need: manufacturers seeking to outsource their data management server setup and maintenance are looking for secure, centralized repositories that can support multi-site collaboration without expanding internal IT overhead. This is especially relevant for organizations that want measurement data to feed design feedback, production tuning, and quality analytics without constructing and maintaining their own data backbone from scratch. The report compares managed cloud approaches with traditional on-premises models, highlighting where each model reduces friction and where each introduces dependencies that procurement must manage carefully.
SME Economics and Renewal Sensitivity
Price pressure is not uniform across the customer base. It is highest in SME accounts, where training cost and license fees affect software renewal decisions more directly than in large enterprises with broader resourcing flexibility. This sensitivity is reshaping vendor expectations around onboarding, user experience, and the perceived return from automation features. For buyers, the implication is clear: the lowest sticker price may not be the lowest cost over a renewal cycle if the platform creates steep learning curves or forces manual workarounds. The study frames software evaluation around total operating friction rather than initial acquisition cost alone.
What the Report Unlocks for Decision-Makers
PW Consulting’s Metrology Software Market study is built to convert context into action. Readers will find a structured pathway from market sizing to operational selection criteria, with special attention to the practical consequences of feature roadmaps, device interoperability, and data management choices. The analysis is designed to support several recurring 2026 decisions:
- Vendor shortlisting: how to weight standards alignment, device coverage, and integration capability when comparing platforms with different strengths.
- Deployment sequencing: where cloud centralization, managed services, or on-prem arrangements create the best fit for data governance and internal resourcing.
- Compliance readiness: how automated reporting, data traceability, and standards-based exchange can reduce the operational load of regulatory documentation.
- Renewal and expansion planning: how to anticipate training burden, license sensitivity, and feature-dependent productivity gains when forecasting software value over multiple years.
The report also integrates recent product-cycle signals that matter for procurement timing. Recent releases have emphasized standards-based interoperability, expanded device compatibility, and cloud-oriented data centralization, alongside enhancements in inspection tooling and collaboration features. These developments are not isolated product updates; they reflect a competitive field moving toward smoother connectivity with enterprise data systems and more standardized digital thread communication. The study interprets these moves in the context of buyer risk, implementation effort, and long-term data usability.
Where the Hidden Intelligence Lives
Macro momentum tells you the market is expanding; detailed segmentation tells you where to aim. This briefing deliberately keeps the most actionable dimensions in reserve. The full research unpacks regional revenue distribution, segment-level size and growth patterns, application-specific demand profiles, and concentration metrics that reveal how competitive pressure is distributed across the vendor base. Those details are essential for building defensible shortlists and timing decisions, but they are also the parts of the analysis most likely to be misread without the surrounding methodology and scenario context.
In the complete study, readers will find segment-by-segment size and trajectory, regional revenue structures, application weighting, and competitive share indicators that connect directly to sourcing strategy and negotiation posture. More importantly, the report ties those numbers to operating realities: where compliance pressure is greatest, where cloud centralization reduces risk, where training and license economics influence renewal behavior, and where interoperability has become a non-negotiable requirement rather than an optional enhancement.
Why the Full Study Matters in 2026
The metrology software market is entering a phase in which strategic advantage will accrue to organizations that treat measurement as a managed data function. The 2026 planning cycle rewards clarity about integration pathways, compliance alignment, device interoperability, and the economics of ownership across the renewal horizon. A high-level view of market growth is useful; a structured map of segment dynamics, vendor positioning, and deployment trade-offs is what turns that growth into a planning advantage.
PW Consulting’s complete Metrology Software Market research is intended to be that map. It is written for teams that need to justify investment, compare platforms, and anticipate the operational consequences of architectural choices. The full report contains the segmented intelligence, regional context, and competitive detail required to support those decisions with confidence.
For teams preparing acquisition roadmaps, integration plans, or compliance-aligned quality strategies for 2026 and beyond, the next step is to move from industry momentum to decision-ready detail. The complete study, including all segmentation, forecast assumptions, and competitive analysis, is available through our research portal at PW Consulting Metrology Software Market Research .
For detailed analysis of this topic, please visit the official page: Metrology Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


