



PW Consulting: Thermal Management Market Hits $13.8B in 2025, 8.1% CAGR to $23.8B by 2032

The Thermal Management Imperative: Strategic Intelligence for the 2026 Market Landscape
As we navigate the complex technological shifts of the mid-2020s, thermal management has ceased to be merely a supporting engineering function. It has become a critical bottleneck and a primary enabler of innovation across multiple high-growth sectors. From the exponential heat loads generated by artificial intelligence workloads in data centers to the stringent reliability requirements of next-generation automotive systems, controlling temperature is now synonymous with controlling performance. PW Consulting is proud to unveil our latest comprehensive study on the Thermal Management Market, a report designed not just to map the terrain, but to provide the strategic compass necessary for enterprise decision-making in 2026 and beyond.
Water-Washable Resin-Based Ribbon Market
This article serves as an executive preview of the depth and utility embedded within our full research publication. Our objective is to highlight why this intelligence is vital for your strategic planning cycles, investment committees, and operational roadmaps. While we will outline the macro trajectory and the critical dynamics reshaping the industry, the granular segmentation data and proprietary competitive profiles contained in the full report are reserved for our clients. This approach ensures that the strategic advantage derived from deep data remains exclusive to those who invest in comprehensive intelligence.
Worldwide Chemical Resistant Fiber Market
Market Trajectory: A Decade of Accelerated Growth
The thermal management sector is currently riding a wave of demand that shows no signs of abating. Our historical analysis covers the period from 2020 through 2025, establishing a robust baseline of resilience and growth despite global supply chain fluctuations. The market has demonstrated consistent upward momentum, evolving from a valuation of approximately 9.35 billion USD in 2020 to an estimated 13.8 billion USD by 2025. This historical performance sets the stage for a forecast period that extends through 2032, where we project the market valuation to reach nearly 23.8 billion USD.
Worldwide Construction Vehicle Axle Market
Such growth is not linear; it is propelled by structural shifts in how technology is deployed and cooled. The compound annual growth rate observed during our forecast horizon underscores the intensity of this expansion. For stakeholders, this trajectory suggests that thermal management is no longer a mature, stagnant market but a dynamic field ripe with investment opportunities and partnership potential. However, understanding the aggregate numbers is only the first step. The real value lies in dissecting how this growth is distributed across technologies, applications, and geographies, which is where our full report provides unparalleled granularity.
The Shift from Traditional to Advanced Cooling
The historical growth from 2020 to 2025 was largely driven by incremental improvements in existing technologies. However, the forecast period from 2026 to 2032 marks a transition point. We are witnessing a decisive shift away from conventional air-cooling methods toward more sophisticated hybrid and liquid cooling solutions. This is not merely a technological preference but a physical necessity driven by higher power densities. As electronic components become more compact and powerful, the ability to dissipate heat efficiently determines the viability of the entire system.
Regional and Segment Nuances
While the global aggregate figures are impressive, the regional disparities tell a more complex story about where the opportunities lie. North America and Europe have historically held significant shares of the market, driven by established infrastructure and early adoption of high-density computing. Meanwhile, the Asia Pacific region continues to be a critical engine for growth, fueled by manufacturing capacity and rapid technological adoption. In our full report, we break down these regional contributions with specific revenue valuations for each territory, allowing you to assess market entry barriers and localization strategies with precision.
Similarly, the segmentation by type reveals a reshuffling of the portfolio. Convection cooling devices have traditionally held a large portion of the market, but the demand for conduction and hybrid cooling devices is accelerating. The full study quantifies these splits, providing exact revenue figures for each technology type, enabling you to identify which technological bets are likely to yield the highest returns in the coming years.
Key Drivers and Industry Dynamics
To make informed decisions in 2026, one must understand the underlying forces pushing the market. Our report dedicates significant attention to the dynamics section, where we analyze the interplay of regulations, standards, and macro trends. These factors are not background noise; they are active variables that will influence cost structures, compliance requirements, and technology lifecycles.
Regulatory Pressures and Environmental Standards
One of the most critical dynamics identified involves regulatory changes regarding refrigerants. With the EPA governing high global warming potential refrigerants effective January 2027, companies must prepare for a transition in their cooling fluid portfolios. This regulatory shift impacts not only data centers but any industrial application relying on traditional cooling agents. Our analysis details the timeline and the potential market impact of these regulations, helping compliance teams and procurement officers anticipate supply chain adjustments.
Furthermore, the establishment of ISO thermal management standards for data center cooling is bringing a new level of uniformity to the industry. Announced in mid-2025, these standards aim to optimize energy efficiency and interoperability. For enterprises, adhering to these standards may become a prerequisite for partnerships and certifications. The full report contextualizes these standards within the broader competitive landscape, explaining how they might consolidate the market around compliant leaders.
The AI and Liquid Cooling Nexus
A macro trend that cannot be overlooked is the increased demand for liquid cooling in AI data centers. As artificial intelligence models grow in complexity, the power consumption of training and inference hardware has skyrocketed. Air cooling is increasingly reaching its physical limits in high-density environments. This has spurred a surge in demand for direct-to-chip and immersion cooling technologies. Our industry context analysis highlights this shift as a primary growth catalyst for the forecast period. Understanding the specific adoption rates and capacity requirements of this trend is essential for suppliers of liquid cooling components and for data center operators planning capacity expansions.
Competitive Landscape: Consolidation and Innovation
The competitive environment in thermal management is characterized by a mix of specialized innovators and large conglomerates seeking to expand their footprint. Our report provides detailed profiles of key companies, but beyond the profiles, we analyze the recent movements that signal the direction of the market. The last few months of 2025 and early 2026 have been particularly active, with significant mergers and acquisitions reshaping the buyer landscape.
Strategic Acquisitions Defining the Future
In a move completed in March 2026, Eaton finalized the acquisition of the Boyd Thermal business. This integration brings advanced liquid cooling and grid-to-chip solutions under the Eaton umbrella, signaling a strong commitment to electrified thermal solutions. Just prior to this, in February 2026, Johnson Controls signed an agreement to acquire Alloy Enterprises. This deal is focused on strengthening their data center thermal management platform, adding specialized capabilities to their existing YORK chiller and Silent-Aire hyperscale cooling portfolio.
These acquisitions are not isolated events; they represent a broader strategy among market leaders to secure supply chains and integrate complementary technologies. Vertiv, Schneider Electric, Johnson Controls, and other major players are actively positioning themselves to capture the value chain from component manufacturing to system-level integration. By examining these moves in our full report, clients can gauge which partnerships are likely to strengthen and where potential gaps might emerge in the supply market.
Key Players and Their Focus Areas
The market includes a diverse set of players, each dominating specific niches. Vertiv, headquartered in Atlanta, continues to focus on adaptive air, liquid, and hybrid cooling systems specifically tailored for data centers and high-density thermal management. Schneider Electric, based in Paris, is heavily invested in EcoStruxure data center software and modular liquid cooling solutions designed for HPC and AI workloads. Johnson Controls, from Charlotte, leverages its YORK chillers and Silent-Aire solutions to provide integrated thermal management for massive data center operations.
On the component and material side, Boyd Corporation has long been known for advanced liquid cooling plates and extruded heat sinks. CoolIT Systems, from Victoria, focuses on high-performance liquid cooling systems for CPUs and servers. Meanwhile, companies like Calyos in Paris are pushing the boundaries with micro-channel heat pipes and direct-to-chip cooling. In the materials sector, Dow is focusing on thermal gels, fluids, and coolant management, while Gates Corporation provides high-capacity MegaFlex hoses essential for liquid cooling systems. Indium Corporation rounds out this competitive view with a focus on high-performance metal thermal interface materials, crucial for semiconductor packaging.
Our full report not only lists these companies but analyzes their relative market positions, strategic focus areas, and recent developments such as Indium Corporation's featured presence at TestConX 2026. This depth allows you to benchmark your own capabilities or identify potential partners and competitors with accuracy.
Segmentation Deep Dive: Applications and Technologies
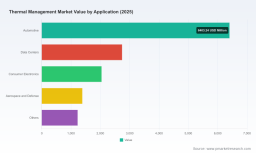
While we have avoided specific percentage breakdowns in this preview, it is important to understand the application diversity driving the market. The automotive sector undoubtedly represents a massive portion of the demand, driven by the electrification of vehicles and the need for battery thermal management. Data centers remain the hotbed of innovation, particularly with the shift to liquid cooling. Consumer electronics, aerospace, and defense also contribute significant shares, each with unique thermal challenges.
The full report provides exact revenue valuations for each application segment. This allows you to answer critical questions: How much revenue is attributable to automotive versus data centers? Which application segment is growing faster? What is the specific market size for aerospace and defense thermal solutions? Having these numbers allows for precise market sizing for your specific product offerings.
Similarly, the technology segmentation is nuanced. Conduction cooling devices, convection cooling devices, hybrid cooling devices, and others each cater to different thermal requirements. The forecast data shows how the balance between these technologies is expected to shift. For instance, as hybrid cooling devices gain traction, the revenue mix will change. Our report provides the exact valuation for each technology type for the base year and forecast years, enabling a detailed technology road mapping exercise.
Strategic Value for 2026 Decision Making
Why should your organization invest in this level of detail? In 2026, the margin for error is narrowing. The combination of regulatory deadlines, rapid technological obsolescence, and intense competition means that decisions must be data-backed. Guessing market size or competitor strength is a strategy that leads to lost market share.
Investment and Capacity Planning
For investors and CAPEX managers, the forecast period through 2032 offers a long-term view of opportunity. Knowing which segments will grow allows for targeted capital allocation. Whether you are expanding a manufacturing line for heat sinks or investing in a startup focused on thermal fluids, the data in this report provides the quantitative backing needed to justify the investment. The high demand for high-performance TIMs in semiconductor packaging, identified as a raw material trend in our analysis, suggests specific supply chain opportunities that might be missed without granular data.
Operational and Compliance Strategy
For operations leaders, the report details the implications of the EPA refrigerant regulations and ISO standards. Understanding the timeline helps in planning for retrofitting or new installations. Ignoring these dynamics could lead to stranded assets or compliance penalties. The competitive analysis also helps in negotiating with suppliers. If you know the market concentration levels—with the top three companies holding a CR3 of 25.5 percent and the top five at 32.8 percent—you can better understand supplier power and negotiate contracts with leverage.
Market Entry and Expansion
For companies looking to enter new geographic markets or application verticals, the regional and application segmentation data is indispensable. You can identify which regions offer the highest revenue potential relative to competition. You can assess whether the automotive sector in a specific region is a viable entry point compared to data centers. The detailed breakdown prevents the costly mistake of entering a saturated segment or overlooking a high-growth niche.
Conclusion: Access the Complete Intelligence
The thermal management market is at a inflection point. The convergence of AI demand, regulatory changes, and technological innovation is creating a landscape where strategic foresight is the primary differentiator. This preview has outlined the macro trends, the competitive movements, and the regulatory pressures that define the environment. However, the true power of this research lies in the data that supports these conclusions.
To make the most informed decisions for 2026 and the forecast period ahead, you need access to the specific revenue figures, segmentation splits, and detailed company profiles that we have reserved for the full report. PW Consulting's Thermal Management Market study is designed to be a cornerstone of your strategic planning. We invite you to visit our source webpage to access the complete intelligence. Equip your team with the data required to navigate the heat of competition and secure a leadership position in the market of tomorrow.
The insights provided here are just the surface. The depth of analysis required to outmaneuver competitors and capitalize on the 8.1 percent growth trajectory awaits you in the full publication. Do not rely on generalities in a market this specialized. Secure the detailed intelligence that will drive your successful strategy.
For detailed analysis of this topic, please visit the official page: Thermal Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


