



PW Consulting: Light Gauge Steel Market to Hit USD 42.7B in 2025, Grow at 5.73% CAGR to USD 63.02B by 2032

Navigating the Light Gauge Steel Market: A Strategic Intelligence Brief for 2026 Decision-Makers
The construction materials landscape is undergoing a structural recalibration. As decarbonization mandates tighten, labor constraints persist, and prefabrication demands accelerate, Light Gauge Steel (LGS) has moved from a niche alternative to a strategic core component in modern building systems. For executives, investors, and procurement leaders operating in 2026, the question is no longer whether LGS will gain traction but how to position portfolios, supply chains, and go-to-market strategies against a rapidly consolidating and innovation-driven market.
Worldwide Constant Temperature Electric Blanket Market
PW Consulting's latest Light Gauge Steel Market research study is engineered to translate macro trajectories into executable intelligence. Rather than offering static snapshots, this report maps the operational, regulatory, and competitive forces that will define market behavior between 2026 and 2032. The brief below outlines the strategic architecture of the study, demonstrates how macro indicators contextualize today's decisions, and highlights the competitive and regulatory signals that are already reshaping the field. Complete segmentation breakdowns, regional deployment matrices, and company-level performance metrics are reserved for the full report, where they can be cross-referenced against your internal benchmarks and growth models.
Worldwide Dry Suit Market
Why 2026 Imposes a Different Decision Rhythm
The post-pandemic construction cycle has matured into a phase defined by cost discipline, material traceability, and engineered efficiencies. Organizations can no longer rely on historical volume growth alone to justify capacity expansion or product development. Instead, they must interpret how demand shifts across building types, how regional procurement ecosystems evolve, and how standard-setting bodies influence specification behavior.
Worldwide Natural Creatine Market
Our research window opens from a 2025 base year that captures the market at a meaningful inflection point. Historical tracking from 2020 through 2025 demonstrates a sustained upward trajectory, with the overall market expanding from approximately 29.0 billion USD in 2020 to 42.71 billion USD in 2025. That progression reflects more than cyclical recovery; it indicates structural adoption across multiple construction verticals, supported by lighter material handling, faster erection timelines, and increasing compatibility with off-site manufacturing workflows.
Looking forward, the forecast horizon through 2032 projects continued expansion at a CAGR of 5.73 percent, with the market advancing from 44.71 billion USD in 2026 toward 63.02 billion USD by 2032. These headline numbers matter because they reframe the scale of opportunity relative to capital allocation cycles. A mid-single-digit compound trajectory in a materials sector typically signals durable demand rather than speculative surges, which means firms that invest early in manufacturing precision, engineering partnerships, and specification capture can compound advantages over multiple budget cycles.
Crucially, the macro path only becomes actionable when tied to segmentation behavior, pricing architecture, and competitive response patterns. That is where the full study adds differentiated value: it disaggregates the trajectory into the operational dimensions that determine which players capture share, which applications become margin leaders, and which geographies transition from emerging interest to sustained deployment.
Decoding the Market Architecture
The LGS market is not a single demand pool. It is a matrix of framing solutions, application requirements, and regional procurement cultures that reward different capabilities. Our research unpacks this matrix through three analytical lenses: type, application, and region. Rather than presenting these as isolated charts, the study evaluates how they interact to shape pricing power, specification risk, and distribution priorities.
Type-Level Dynamics
The framing category encompasses wall-bearing systems, skeleton framing, long-span solutions, and other specialized types. Each carries distinct engineering requirements, installation workflows, and end-user expectations. Wall-bearing systems tend to align with repetitive structural layouts and faster envelope completion. Skeleton framing supports flexible interior configurations and load distribution strategies. Long-span applications address larger clear-height requirements and specialized architectural programs. The report examines how these type segments differ in specification drivers, fabrication tolerances, and competitive positioning, helping manufacturers and distributors decide where to concentrate engineering resources and sales specialization.
Application Pathways
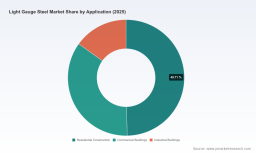
Residential construction, commercial buildings, and industrial buildings represent the principal application pathways. Their demand profiles diverge significantly in procurement cadence, volume consistency, and tolerance for design customization. Residential demand is shaped by housing velocity, build-system standardization, and regional labor availability. Commercial demand responds to tenant improvement cycles, office and hospitality renovation activity, and the push toward modular interiors. Industrial demand is influenced by warehouse expansion, logistics infrastructure, and light-manufacturing facility construction. The report maps how these application segments interact with framing type preferences and regional procurement habits, providing a basis for prioritization in product roadmaps and channel strategy.
Regional Realities
Regional markets operate under different code environments, sourcing expectations, and competitive densities. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct opportunities and constraints. The research avoids superficial regional comparisons and instead evaluates how local specification culture, trade dynamics, and adoption maturity influence market behavior. Decision-makers receive context on where distribution networks need strengthening, where engineering partnerships accelerate specification, and where local manufacturing or assembly capabilities create defensibility.
By weaving type, application, and region together, the study reveals where growth is most concentrated, where substitution risk is highest, and where strategic entry or expansion would yield the strongest return on effort. The complete segmentation analysis in the full report provides the quantified foundation for those decisions without exposing the underlying splits in advance, preserving the integrity of the intelligence for clients who need to benchmark against their own pipeline and capacity assumptions.
Competitive Landscape and Strategic Positioning
One of the strongest features of this research is its structured evaluation of the companies actively defining LGS market behavior. The competitive field spans established framing manufacturers, structural component suppliers, cold-formed steel specialists, and broader steel ecosystems that extend into LGS applications. Rather than treating these players as a simple roster, the study assesses them through the lens of capability depth, geographic reach, and strategic posture.
The market structure reflects meaningful concentration. The top three firms collectively account for approximately 55.0 percent of market share, while the top five reach around 65.0 percent. This concentration pattern signals that scale, specification relationships, and manufacturing consistency are becoming decisive advantages. At the same time, the presence of multiple regional specialists and product-focused innovators indicates that differentiation remains possible for firms that excel in installation precision, engineering support, or targeted application expertise.
The competitive analysis profiles a broad cross-section of organizations, including ClarkDietrich Building Systems LLC, WARE Industries, Inc., CEMCO, Hadley Industries PLC, Genesis Manazil Steel Framing, Scottsdale Construction Systems Ltd, Nucor Building Systems, Studco Building Systems, Tata BlueScope Steel, The Steel Network, Inc., ArcelorMittal S.A., Precision Walls Inc., FRAMECAD Limited, MiTek Industries, Inc., Stratus Steel, EPACK Prefab, MBA Building Supplies, Aegis Metal Framing, Radius Track Corporation, and Steel Frame Solutions Ltd.
Each profile is evaluated for its operating footprint, product system orientation, and relevance to specific application or regional contexts. For example, firms headquartered in the United States and United Kingdom often reflect mature framing ecosystems with strong specification channels, while entities operating in Australia, the Middle East, India, and New Zealand illustrate how LGS is gaining traction in markets seeking faster construction cycles, material consistency, or prefabricated system adoption. The study does not merely list these companies; it situates them within competitive clusters, assesses where they are likely to compete on price versus value, and identifies which organizational profiles are best positioned to benefit from the forecast trajectory.
This competitive layer is essential for 2026 strategy because the market is not expanding in a vacuum. Growth will be allocated according to who can execute on installation reliability, engineering support, supply continuity, and specification influence. The report provides the framework needed to determine whether your organization should compete through scale, specialization, regional depth, system integration, or partnership-led distribution.
Regulatory Signals and Industry Dynamics Reshaping Deployment
Materials markets do not move solely on demand; they move on the standards, certifications, and technical updates that govern specification and liability. In 2026, several developments are already reshaping how engineers, contractors, and manufacturers approach cold-formed steel and light gauge steel systems. The report integrates these dynamics into its forward-looking analysis so that strategic recommendations reflect not just market size but also the rules of engagement.
A notable technical milestone is the publication of CFSEI Tech Note J200-26 on the vibration of cold-formed steel joist framed floors. Updates of this nature matter because they influence floor system design assumptions, acoustic and serviceability considerations, and the confidence with which engineers specify LGS assemblies in multi-unit and commercial projects. When technical guidance evolves, specification behavior evolves with it, and manufacturers that align product documentation, engineering support, and training to the new expectations can strengthen their position in the specification pipeline.
Alongside the technical update, the CFSEI 2026 Expo in Long Beach, California brought together more than 250 engineers to discuss resilience and real-world solutions for cold-formed steel framing. Events of this scale are more than industry gatherings; they are indicators of where professional attention is concentrating, which performance themes are gaining prominence, and how knowledge transfer is shaping adoption. The research interprets these gatherings as signals of specification momentum and workforce readiness, both of which affect the speed at which LGS solutions move from consideration to repeatable deployment.
Innovation in installation precision is another dynamic shaping the market. The Steel Network's introduction of NotchTrak in April 2026 reflects an industry-wide emphasis on improving accuracy and efficiency in LGS framing installation. Products and systems that reduce field variability, shorten assembly time, or improve alignment can influence contractor preference and repeat procurement. The study evaluates how such launches alter competitive differentiation and what they imply for manufacturers seeking to compete on total installed value rather than component price alone.
Talent development is also part of the market's future readiness. CFSEI's announcement of 2026 Student Competition winners and stipend recipients highlights continued investment in the next generation of cold-formed steel design talent. For long-term market planning, this matters because specification ecosystems depend on engineers who understand LGS behavior, design constraints, and system integration. The report frames talent pipelines as an underappreciated but real driver of sustainable demand, especially in markets where engineering capacity can either accelerate or bottleneck adoption.
By embedding these regulatory and industry dynamics into the broader forecast, the research ensures that strategic recommendations are grounded in how the market actually changes, not just how it grows. The complete dynamic analysis in the full report connects these developments to regional specification environments, competitive responses, and application-level implications.
What Decision-Makers Can Expect Inside the Full Study
This market research is built for practical use. It is structured to support capital planning, product strategy, channel expansion, competitive benchmarking, and specification positioning. The full study translates the macro and competitive framework into a detailed operational reference that can be aligned with internal planning cycles.
Inside the report, readers will find:
- A comprehensive market sizing and forecast architecture that links historical performance to forward trajectory across the 2026 to 2032 window.
- Segmentation analysis that evaluates framing types, application pathways, and regional demand behavior in a manner designed for prioritization and resource allocation.
- Competitive profiles that place key companies in context, highlighting operating footprints, product system orientations, and strategic positioning.
- Market concentration analysis that clarifies where scale advantages matter and where differentiation remains viable.
- Industry dynamics coverage that ties technical standards, product launches, exhibition activity, and talent development to specification and deployment behavior.
- Strategic implications tailored for manufacturers, distributors, engineering-focused suppliers, and construction-system integrators seeking to act in 2026 and beyond.
The study does not stop at describing the market. It provides the analytical scaffolding needed to interpret where opportunity is most durable, where competitive pressure will intensify, and how to sequence investments for maximum impact. Detailed quantitative splits, company-level benchmarking, and region-specific deployment insights are presented in full within the report so that they can be used for internal modeling and board-level discussion with complete confidence.
How This Research Supports 2026 Strategy
In a market expanding from 44.71 billion USD in 2026 toward 63.02 billion USD by 2032, the strategic question is not simply how large the opportunity is, but how to capture the right portion of it with the right capabilities. The report is designed to help organizations answer that question with precision.
For manufacturers, the research clarifies where product development and fabrication investments are likely to generate the strongest returns, based on application demand and competitive positioning. For distributors and building-system suppliers, it highlights where regional coverage, specification support, and installation reliability can create durable advantage. For engineering-led organizations and component innovators, it identifies where technical updates and precision-focused product launches are reshaping preference and procurement. For investors and corporate strategists, it provides a structured view of concentration, growth dispersion, and competitive dynamics that can inform entry, expansion, or partnership decisions.
The deliberate emphasis on strategic context over raw data exposure reflects the reality that market intelligence is most valuable when it helps leaders decide, not just when it helps them observe. By integrating macro trajectory, segmentation logic, competitive structure, and regulatory momentum into one coherent framework, the study gives executives a way to stress-test assumptions, prioritize initiatives, and align 2026 actions with the market's longer-term architecture.
Conclusion: Turn Forecast Confidence into Executable Strategy
The Light Gauge Steel market is entering a phase where growth is supported by structural adoption, technical refinement, and competitive consolidation. That combination rewards organizations that act with informed discipline rather than broad speculation. PW Consulting's Light Gauge Steel Market research delivers the depth, structure, and strategic framing needed to make those decisions with confidence.
The full report contains the complete segmentation analysis, detailed company evaluations, concentration data interpretation, and regional deployment insights that turn high-level trajectory into operational direction. For teams preparing capital plans, product roadmaps, channel strategies, or competitive responses for 2026 and beyond, the study offers a rigorous intelligence base to guide execution.
Access the full Light Gauge Steel Market research to retrieve the complete data architecture, segmentation detail, and strategic recommendations designed for immediate decision use.
For detailed analysis of this topic, please visit the official page: Light Gauge Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


