



PW Consulting: In-Building Wireless Market to Hit $49.3M by 2032, 11.8% CAGR

The 2026 In-Building Wireless Market: Strategic Imperatives for Enterprise Decision-Makers
The Connectivity Imperative Driving Next-Generation Infrastructure
The modern enterprise operates on a foundation of seamless, high-capacity connectivity. As organizations continue to digitize operations, deploy dense IoT ecosystems, and expect uninterrupted wireless performance from staff and visitors alike, the physical and operational architecture of in-building wireless (IBW) networks has transitioned from a tactical facility requirement to a core strategic asset. The trajectory of the IBW market through 2026 confirms that institutional attention is well placed. Following a sustained expansion cycle between 2020 and 2025, the sector reached a valuation of approximately 22.58 million USD at the close of the base year. From that starting point, the market is projected to advance through the 2026–2032 forecast horizon, with 2026 opening at an estimated 25.35 million USD and climbing steadily toward 49.3 million USD by 2032. This progression reflects a compound annual growth rate of 11.8 percent, signaling that infrastructure planners and corporate decision-makers must treat IBW investment as a long-term capability rather than a periodic refresh cycle. The acceleration is not merely a reflection of incremental demand. It is driven by structural shifts in how facilities consume wireless spectrum, how operators monetize indoor coverage, and how enterprises balance performance requirements against operational complexity. Understanding the forces shaping this expansion requires moving beyond headline valuations and examining the architecture of demand, the competitive dynamics defining supply, and the regulatory and technical environment that determines deployment feasibility. Our latest In-Building Wireless Market research is designed precisely for that purpose. It translates macroeconomic momentum into actionable positioning, enabling technology buyers, network architects, and commercial strategy teams to align capital allocation with the specific conditions that will govern the next several years of deployment.
Automatic Sealing and Packing Machine Market
Market Trajectory and the Structural Forces Behind the Growth Curve
The expansion recorded between 2020 and 2025 established a clear baseline for understanding today’s demand environment. Over that five-year span, the market moved from 12.93 million USD to 22.58 million USD, demonstrating resilience through shifting macroeconomic conditions and growing comfort with advanced indoor wireless architectures. The current forecast period extends that trend into the late 2020s and early 2030s, with the market expected to reach 28.19 million USD in 2027, 32.51 million USD in 2028, and continued appreciation through 34.5 million USD in 2029, 39.42 million USD in 2030, 44.38 million USD in 2031, and 49.3 million USD in 2032. These figures illustrate a market that is not simply rebounding but compounding, with each forecast interval building on prior capacity gains, technology maturity, and broadened enterprise adoption. The 11.8 percent CAGR embeds several underlying drivers that our research unpacks in detail. First, the shift toward higher-density wireless environments is accelerating across sectors that historically underinvested in indoor coverage optimization. Second, the operational case for distributed wireless architectures is becoming more compelling as facilities seek to support simultaneous high-throughput applications, real-time analytics, and massive device connectivity without degrading performance. Third, the commercial logic of shared and neutral host deployment models is reducing the friction that previously constrained enterprise adoption, particularly in properties where multiple stakeholders or carriers must coexist on a single infrastructure footprint. Our report situates these trends within a rigorous analytical framework. It tracks revenue progression across the historical and forecast windows, isolates the variables that materially influence deployment velocity, and identifies where market participants stand to capture value as architectural preferences evolve. Importantly, the analysis is structured to support decision-making at the procurement, investment, and competitive positioning levels. By understanding how the overall revenue curve behaves and what conditions sustain it, strategic teams can forecast infrastructure spend with greater precision and avoid the common pitfall of reacting to technology hype rather than deploying resources against verified demand patterns.
Electronic Contract Management Market
Core Segmentation Dynamics Reshaping Deployment Architecture
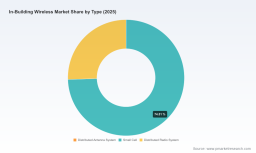
The composition of market growth reveals a landscape in which technology type and application environment interact to create distinct deployment priorities. Our research examines technology segmentation across Distributed Antenna Systems, Small Cell architectures, and Distributed Radio Systems, along with application segmentation spanning Commercial Campuses, Hospitality, Transportation and Logistics, Entertainment and Sports Venues, Industrial Manufacturing, Education, Government, and Healthcare. These categories are not isolated demand pools. They form a set of interdependent considerations that determine which architecture, deployment model, and vendor capability set will deliver the strongest return for a given facility profile. Technology choices increasingly reflect the need to reconcile coverage breadth with capacity granularity. Some environments favor centralized distribution approaches that simplify signal management across large footprints, while others rely on more granular deployment nodes that offer rapid scaling and localized performance control. The report details the circumstances in which each architecture delivers the most favorable balance of capital efficiency, maintenance burden, and performance reliability. On the application side, the demand profile is equally varied. Hospitality and entertainment venues continue to prioritize seamless connectivity as a core guest experience and operational enabler. Transportation and logistics environments demand robust wireless performance in spaces with challenging propagation characteristics and high equipment density. Industrial manufacturing contexts emphasize mission-critical reliability and integration with operational technology ecosystems. Education, government, and healthcare facilities face their own combinations of capacity requirements, regulatory considerations, and multi-stakeholder coordination demands. The commercial campus segment sits at the intersection of multiple use cases, often requiring a flexible architecture that can support both enterprise productivity and visitor-facing service expectations. Our segmentation analysis goes further than descriptive classification. It evaluates how these demand categories map to deployment economics, where architectural choices influence total cost of ownership, and how facility characteristics shape the relative attractiveness of different vendor offerings. Decision-makers who rely on generic wireless assumptions often underestimate the importance of environment-specific design. This research corrects that gap by providing a structured view of how application profiles influence both short-term deployment decisions and longer-term network evolution. By focusing on the practical relationships between segment characteristics and architectural viability, the report enables teams to prioritize investment where it produces the most durable operational outcomes.
Worldwide Milling Automation Market
Competitive Dynamics and the Strategic Positioning of Leading Providers
The IBW market is characterized by a concentration of capability among a defined group of established and emerging providers, and understanding their strategic behavior is essential for procurement planning and competitive assessment. Our research includes detailed profiles of key participants, with particular attention to companies whose recent product and positioning moves signal where the market is heading. Moso Networks, based in the United States, has built a profile around private 5G and neutral host solutions for in-building wireless. Its offering emphasizes plug-and-play indoor and outdoor radios designed to function as rapid DAS replacements, supported by CBRS capability and cloud-based management. This positioning reflects a broader movement toward reducing deployment friction while preserving flexibility in operator and enterprise use cases. In January 2026, Moso Networks advanced this direction by launching the Chorus P5G solution in partnership with Ataya, an initiative intended to simplify private 5G deployment to a 5G radio and secure cloud connection for indoor and outdoor use. The move underscores an emerging expectation that private wireless deployments must be manageable without requiring extensive integration overhead. ANDREW, operating under Amphenol Corporation and also headquartered in the United States, provides a complementary but distinct set of capabilities. Its portfolio spans ERA digital DAS, ONECELL small cells, and in-building wireless solutions oriented toward 5G coverage, multi-operator connectivity, and mission-critical private networking. The company’s focus on multi-operator and neutral host models positions it within the infrastructure layer that serves venues and enterprises seeking shared access arrangements rather than single-operator exclusivity. In January 2026, ANDREW received honors at the Small Cell Forum awards for innovation in indoor and outdoor wireless solutions and neutral host and multi-operator models. The recognition highlighted a world’s first DAS deployment with full direct digital connectivity to three leading RAN vendors in a live stadium, an achievement that illustrates the increasing feasibility of high-performance, multi-vendor indoor environments. SOLiD, based in South Korea, contributes another strategic angle through modular and scalable DAS and in-building wireless solutions designed for venues and enterprises that must deliver 5G coverage and capacity in challenging environments. Its emphasis on modularity aligns with the broader market push toward architectures that can expand incrementally as coverage or capacity requirements change. These company profiles do not exist in isolation. They reflect a competitive environment in which vendors are differentiating through deployment simplicity, multi-operator enablement, modularity, and cloud management maturity. Our report maps these differentiators against the conditions that matter most to buyers, including integration complexity, operational overhead, and the ability to support evolving spectrum and service requirements. In parallel, the analysis tracks wider industry signals that shape competitive dynamics. The Wireless Infrastructure Association highlighted Nextivity Inc. in January 2026 as a key player in in-building wireless networks, with emphasis on ROI measurement and unified network approaches for schools and enterprises. Such visibility indicates that competitive positioning is increasingly tied to measurable outcomes and cross-environment network unification, not solely to hardware capability. The market concentration context further reinforces the importance of strategic supplier evaluation. With a CR3 of 52.6 percent and a CR5 of 67.0 percent, the landscape is concentrated enough that vendor selection has meaningful implications for negotiation leverage, integration risk, and long-term support continuity. Our research supports more disciplined supplier assessment by aligning provider capabilities with the deployment scenarios in which they are most likely to succeed.
Inside the Report: Operational Content Designed for Execution
Strategic Decision Support Across the Investment Lifecycle
A market study earns its place in an enterprise workflow only if it supports concrete actions. This report is built around that expectation. It provides a structured foundation for evaluating where in-building wireless investment should be prioritized, how deployment architecture should be selected, and what vendor and partnership strategies are most likely to deliver value across the forecast horizon. The content is organized so that readers can move from high-level market context to operational considerations without losing analytical discipline. Rather than offering generic technology overviews, the report ties market behavior to procurement and planning decisions that matter in 2026 and beyond.
Detailed Architecture and Deployment Considerations
The report examines the physical and operational realities that determine whether an in-building wireless investment performs as intended. Topics include the integration requirements associated with existing fiber optic networks and signal sources, with emphasis on practical factors such as PIM mitigation and power optimization. These details are not ancillary. They directly affect deployment reliability, long-term maintenance burden, and the feasibility of achieving consistent coverage in environments where signal propagation is constrained by structure, density, or interference. The analysis also addresses how different architectural approaches influence integration effort and operational control, enabling teams to anticipate both the capital and operational implications of design choices before commitments are made.
Application, Technology, and Regional Demand Context
Demand does not distribute evenly across sectors or deployment environments. The report maps how application profiles shape performance expectations, investment urgency, and architectural suitability. At the same time, it provides regional context that helps decision-makers understand where demand intensity, infrastructure readiness, and competitive activity converge. Rather than presenting narrow percentage breakdowns or isolated submarket figures, the research integrates regional and application context into a broader narrative of where growth is accelerating and why. This approach is deliberate. It allows readers to grasp the relative importance of different demand pools and geographic environments without reducing the analysis to a static table of splits. The result is a market map that is useful for strategy formulation, sales targeting, investment prioritization, and competitive positioning.
Regulatory, Spectrum, and Operational Environment Factors
Technology selection cannot be separated from the regulatory and spectrum context in which it operates. The report incorporates the January 2026 FCC action through FCC 26-1, which enabled more flexible operation of low-power indoor unlicensed devices in the 6 GHz band, including building loss considerations within automated frequency coordination. This development matters because it affects how unlicensed and lightly licensed spectrum can be used to complement licensed deployments and how automation tools influence indoor frequency management. The report also addresses broader FCC activity in 2026 related to spectrum abundance in space operations and the modernization of sharing rules for satellite broadband, both of which carry implications for spectrum access and the wider environment in which in-building wireless enhancements are planned. In addition, the analysis notes compliance and procurement realities relevant to public-sector and infrastructure buyers, including alignment with Build America Buy America requirements for certain products as of early 2026. These regulatory and operational inputs are not treated as isolated news items. They are integrated into the practical side of deployment planning, helping readers assess where flexibility is increasing, where constraints remain, and how those conditions influence vendor selection, architecture design, and total project risk.
Why This Research Matters for 2026 Strategy
Translating Market Momentum into Capital and Vendor Strategy
Organizations evaluating in-building wireless investment face a common challenge: market momentum is visible, but the path from growth headline to deployment decision is not. The market’s expansion from 12.93 million USD in 2020 to 22.58 million USD in 2025, and its projected rise through the forecast window toward 49.3 million USD by 2032 at an 11.8 percent CAGR, provides a strong signal that indoor wireless infrastructure is moving up the priority stack. But signal strength alone does not define strategy. Decision-makers still need clarity on which application contexts justify accelerated investment, which technology profiles align with specific facility conditions, and how competitive and regulatory developments alter the risk and reward calculus of different deployment approaches. This report is designed to answer those questions with enough depth to guide action. It helps procurement and network teams compare architectural options against real operating conditions, supports executive teams in communicating why indoor wireless investment deserves sustained attention, and equips strategy functions with the context needed to evaluate vendor promises against market reality. In an environment marked by concentration, rapid product iteration, and evolving spectrum possibilities, disciplined research is not a luxury. It is the mechanism that separates informed planning from reactive purchasing.
What the Report Enables Decision-Makers to Do
The research is structured to support a set of recurring strategic tasks. It helps organizations benchmark current infrastructure assumptions against the market direction reflected in the 2026–2032 forecast. It supports vendor evaluation by connecting provider profiles and recent developments to the operational requirements that buyers are likely to face. It clarifies how application environments differ in their connectivity demands and what that means for architecture, timing, and budget sequencing. It also gives leadership teams a shared analytical baseline for discussions about capital planning, partnership strategy, and long-term network evolution. By focusing on usable intelligence rather than exhaustive disclosure of every submarket figure, the report preserves analytical depth while directing readers to the full dataset and supporting detail where they can refine their own models and internal assumptions.
A Strategic Entry Point for Deeper Intelligence
In-building wireless is no longer a niche infrastructure category. It is a strategically significant layer of enterprise connectivity that intersects with private networking, multi-operator access, venue experience, industrial digitization, and facility modernization. The research presented here is intended for teams that need to understand the market well enough to act with confidence in 2026 and to plan for the changes expected through 2032. The macro trajectory, segmentation dynamics, vendor movements, and regulatory context described in this article establish the foundation. The full report extends that foundation into a more granular analytical environment, providing the detailed data, segmentation detail, and scenario-based interpretation that decision-makers need to convert market insight into execution. For organizations seeking to align infrastructure strategy with where the IBW market is actually heading, this research offers the evidence base and interpretive framework required to move forward with precision.
For detailed analysis of this topic, please visit the official page: In-Building Wireless Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


