



PW Consulting: Automobile Cylinder Sleeve Market Hits USD 6.18 Billion in 2025, Projects 5.2% CAGR to 2032

Navigating the Next Wave: Strategic Intelligence for the Automobile Cylinder Sleeve Market 2026–2032
The global automotive powertrain component landscape is undergoing a structural transformation. For procurement leaders, engineering directors, and corporate strategists, the automobile cylinder sleeve market represents far more than a steady replacement cycle. It is a bellwether for material innovation, regulatory compliance, and the shifting center of gravity in global engine manufacturing. PW Consulting’s latest comprehensive research on this segment delivers the granular intelligence required to navigate the 2026–2032 forecast horizon with precision.
Worldwide Isolated RTD Input Module Market
As the industry transitions toward stricter emission standards, hybridized powertrains, and aggressive lightweighting mandates, cylinder sleeve specification has evolved from a commodity purchasing decision into a strategic engineering lever. Understanding where value will concentrate, which material technologies will gain commercial traction, and how the competitive hierarchy is crystallizing around proprietary casting methods requires a market study built on verified primary research and scenario-driven forecasting. This research preview outlines the analytical architecture of our full report, demonstrates how macroeconomic signals translate into actionable decision frameworks, and highlights the competitive dynamics that will separate market leaders from followers.
Hairdressing Training Heads Market
Readers will encounter a synthesis of historical performance data, forward-looking volume projections, and operational intelligence on the firms actively reshaping the supply base. No isolated percentages or region-by-region revenue tables are disclosed here; those granular breakdowns are preserved for the complete deliverable, where they are cross-referenced with capacity utilization rates, pricing architectures, and distributor network mappings. The objective of this preview is to establish the strategic terrain, clarify why disciplined intelligence consumption matters for 2026 planning cycles, and demonstrate the depth of analysis embedded in our methodology.
Worldwide Smart Grammar Editor Market
Market Trajectory: From Recovery Momentum to Sustained Expansion
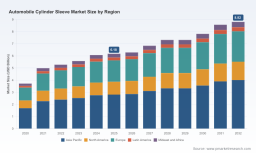
The automobile cylinder sleeve market has demonstrated remarkable resilience through a volatile decade of post-pandemic supply recalibration, fluctuating raw material costs, and divergent regional demand patterns. Historical tracking from 2020 through 2025 reveals a clear upward trajectory, with total market revenue climbing from approximately $3.71 billion to $6.18 billion. That growth arc reflects not only the restoration of global vehicle production volumes but also a structural shift in how engine builders approach cylinder bore durability, thermal management, and lifecycle cost optimization.
Looking toward the forecast window, the trajectory continues upward with measured confidence. Market valuations are projected to reach $6.29 billion in 2026, expanding steadily toward the $8.82 billion mark by 2032. This progression translates to a compound annual growth rate of 5.2 percent, a figure that signals sustainable expansion rather than speculative inflation. Growth of this nature is typically anchored by fundamental demand drivers: rising commercial vehicle utilization in developing economies, sustained passenger car fleet refreshes in mature markets, and the persistent need for upgraded sleeve solutions as internal combustion platforms are refined for efficiency and longevity.
For corporate decision-makers, a 5.2 percent CAGR carries strategic implications beyond top-line projections. It indicates a market where share gains are earned through technical differentiation and supply reliability rather than price compression alone. It also suggests that capacity planning, tooling investment, and material sourcing agreements negotiated in 2026 will have multi-year payoff horizons. Companies that treat the forecast period as a static backdrop risk underinvesting in advanced casting capabilities or misallocating working capital toward segments where margin compression is most acute. The full report decomposes this trajectory by volume-to-value ratios, regional capacity shifts, and application-specific growth vectors, enabling leadership teams to align capital deployment with the most defensible pockets of expansion.
Segmentation Architecture: Where Material, Design, and Application Intersect
Cylinder sleeve demand does not behave uniformly across the automotive ecosystem. The segment is shaped by intersecting technical requirements, cost structures, and manufacturing footprints that determine which product architecture wins in a given application. The research framework dissects the market through three primary segmentation lenses, each carrying distinct strategic implications for suppliers, OEMs, and tier-one integrators.
Material Technology Divergence
Material selection remains the foundational decision point in cylinder sleeve engineering. The historical dominance of traditional cast iron reflects its proven wear resistance, thermal stability, and cost-effectiveness in high-volume applications. Yet the landscape is increasingly textured by the emergence of aluminum alloy formulations and specialized steel variants designed to meet tighter dimensional tolerances and reduced component mass. The interplay between these material categories is not a simple substitution dynamic; rather, it represents a portfolio optimization challenge.
Cast iron continues to anchor a substantial portion of the installed base, particularly where durability under high thermal loads and long service intervals are non-negotiable. Simultaneously, industry trajectory analysis points toward sustained growth in lightweight aluminum and composite alloy architectures, driven by fuel economy targets and the broader regulatory push for vehicle weight reduction. Aluminum-based sleeves, often paired with specialized coatings and surface treatments, enable thermal transfer optimization while contributing to overall engine mass savings. Steel variants occupy a more specialized position, typically deployed where specific load profiles or mating surface requirements demand superior tensile characteristics.
Strategic buyers evaluating material roadmap alignment must look beyond headline performance claims. The research delves into how alloy formulations interact with casting methodologies, how surface finishing tolerances influence runout and friction behavior, and how material supply chains are being restructured to mitigate volatility in metallurgical input pricing. By isolating the value pools within each material category, the report equips engineering and procurement teams with the criteria needed to negotiate supply agreements that balance performance assurance with cost predictability.
Liner Configuration and Application Mapping
Beyond material chemistry, the physical configuration of the sleeve—whether dry, wet, or finned—fundamentally alters the thermal management and assembly architecture of the engine block. Dry liners, seated directly into the cylinder block and relying on the block material for coolant isolation, remain prevalent in applications where structural rigidity and simplified assembly are prioritized. Wet liners, which interface directly with the cooling jacket, offer superior heat extraction but introduce sealing and corrosion management complexities that demand higher precision manufacturing. Finned configurations occupy niche positions where enhanced surface area for thermal dissipation is required under extreme operating conditions.
Application segmentation further differentiates demand intensity and specification requirements. Passenger car platforms account for the largest concentration of sleeve consumption, reflecting the sheer multiplicity of global vehicle platforms and the ongoing refresh cycles required to meet evolving emission norms. Commercial vehicle segments—both light and heavy—present different engineering constraints, with heavy-duty applications emphasizing extended service life, resistance to particulate-induced abrasion, and tolerance for sustained high-load operation. Two-wheeler platforms, while representing a smaller revenue footprint, demand cost-optimized solutions that can be produced at high velocity with minimal tolerance variability.
The full report maps these configuration and application intersections against regional manufacturing footprints, revealing where production localization incentives, logistics cost structures, and OEM sourcing strategies are reshaping supply routes. Rather than presenting static regional shares, the analysis emphasizes the flow of capability: which manufacturing clusters are expanding advanced centrifugal casting capacity, which regions are seeing increased local content requirements, and how tier-one suppliers are repositioning their plant networks to serve emerging platform allocations. This dynamic view allows strategists to anticipate sourcing friction points and identify partnership opportunities before capacity constraints become pricing leverage for incumbents.
Regulatory Pressure and Engineering Imperatives
Regulatory frameworks are no longer peripheral compliance costs; they are primary drivers of material specification and dimensional precision in cylinder sleeve design. The progressive tightening of emission standards across major automotive markets has cascading effects on combustion chamber tolerances, piston ring dynamics, and the thermal fatigue characteristics expected of cylinder liners over extended service intervals.
Standards such as Euro 6d and Bharat Stage VI mandate tighter combustion chamber tolerances and longer service intervals, directly elevating the requirement for cylinder liners that exhibit superior thermal fatigue resistance and dimensional stability under repeated heating and cooling cycles. A sleeve that distorts under thermal load compromises combustion efficiency, increases oil consumption, and accelerates wear across reciprocating components. These pressures push material and coating innovation from optional enhancement to baseline requirement.
Complementing emissions mandates, engineering standards such as SAE J2236 define material specifications for engine cylinder liners, providing a formalized reference for metallurgical composition, casting integrity, and surface performance criteria. Adherence to such standards not only mitigates liability in warranty and quality dispute scenarios but also streamlines the validation process when introducing new sleeve architectures to engine platforms that must satisfy multiple regulatory jurisdictions.
The research integrates these regulatory and standards-driven dynamics into a forward-looking risk matrix. Rather than treating compliance as a static checkpoint, the analysis examines how evolving test protocols, extended durability expectations, and cross-market alignment of emission thresholds are reshaping the acceptable performance envelope for cylinder sleeves. This perspective is critical for organizations that must justify tooling investments or material transitions to internal stakeholders, as it anchors engineering decisions in verifiable regulatory trajectories rather than speculative assumptions.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The automobile cylinder sleeve market exhibits a moderate concentration structure, with leading firms commanding disproportionate influence through proprietary casting technology, long-standing OEM qualifications, and globally distributed production footprints. The competitive hierarchy is not defined solely by scale; it is increasingly shaped by the ability to deliver application-specific liner architectures that satisfy stringent performance criteria while maintaining cost competitiveness across high-volume and specialty segments.
Incumbent Profiles and Capability Positioning
Several established manufacturers anchor the competitive landscape, each leveraging distinct technical strengths and geographic reach. MAHLE GmbH, headquartered in Stuttgart, operates a vertically integrated approach to centrifugal cast cylinder liners, producing in-house solutions for passenger cars, commercial vehicles, and engines extending up to 460 mm piston diameter. Their emphasis on high-strength materials and low-wear running surfaces positions them as a supplier of choice for applications where dimensional consistency and durability under sustained load are critical.
Tenneco Inc., based in Ann Arbor, Michigan, has built its cylinder sleeve portfolio around advanced material optimization, coating engineering, and design precision aimed at enhancing running surfaces, heat transfer efficiency, and friction reduction. Their capability spans light-duty, heavy-duty, and large-bore engines, reflecting a breadth of application expertise that aligns with diverse OEM performance targets.
In the Japanese market, TPR Co., Ltd. has differentiated itself through cast-in liners utilizing patented AsLock® technology delivered via centrifugal casting, alongside thin-wall and wet liner configurations engineered for compatibility with aluminum engine blocks. Their solutions serve Japanese OEMs across gasoline and diesel applications, illustrating how localized technical differentiation can secure long-term supply relationships within concentrated OEM ecosystems.
Kolbenschmidt GmbH, operating from Frankfurt, integrates cylinder liners into broader piston system offerings for passenger cars and commercial vehicles, emphasizing high-quality construction aligned with original equipment specifications. This systems-oriented approach enables coordinated engineering across reciprocating components, reducing interface variability and simplifying validation workflows for engine manufacturers.
The competitive field also includes regionally significant players such as Zhongyuan Cylinder Liner Company Limited in China, which supplies the GKNZ-branded portfolio for automotive and industrial engines, and Aichi Machine Industry Co., Ltd. in Aichi, Japan, whose cylinder liner production supports a range of engine applications. These firms illustrate the importance of regional manufacturing depth and localized engineering responsiveness in markets where supply chain proximity, cost structures, and OEM relationship dynamics diverge from globalized procurement models.
Recent Developments and Industry Reconfiguration
Market structure is not static; it evolves through product introductions, corporate restructuring, and shifts in technology emphasis. Recent industry activity signals ongoing realignment in how cylinder sleeve capabilities are packaged and delivered. In early 2025, Federal-Mogul Powertrain released a new silicon-aluminum alloy composite cylinder liner designed to meet evolving engine demands, reflecting the broader industry exploration of composite formulations that balance thermal performance with weight efficiency.
In parallel, Nippon Piston Ring Co., Ltd. announced plans to merge with Riken, forming NPR-RIKEN Corporation to enhance combined capabilities in piston rings and cylinder liners. This consolidation underscores a recurring theme in component manufacturing: the increasing value of integrated reciprocating system expertise, where liner, ring, and piston dynamics are engineered as a synchronized performance package rather than isolated parts.
The research evaluates these developments not as isolated news items but as structural indicators of where technical investment and M&A activity are concentrating. By examining the interplay between product launches, corporate consolidation, and capability expansion, the report enables strategists to anticipate shifts in supplier bargaining power, identify potential disruptions in established supply routes, and assess which firms are likely to strengthen their qualification positions with major OEMs over the forecast horizon.
What the Full Report Delivers: Analytical Structure and Decision Utility
The complete PW Consulting research deliverable is structured to move from strategic context to operational detail, ensuring that every analytical layer connects to a concrete decision application. The report combines historical reconstruction, multi-variable forecasting, segmentation cross-analysis, and competitive profiling into a cohesive intelligence asset designed for executive planning, engineering roadmap alignment, and procurement strategy refinement.
Core Report Components
- Comprehensive market size reconstruction spanning the 2020–2025 historical window, with methodological transparency on data sourcing, triangulation approaches, and revision history to establish a credible baseline for forecasting.
- Scenario-based projections through 2032 that account for base-case, accelerated, and constrained growth pathways, allowing leadership teams to stress-test capacity planning and sourcing commitments against alternative macroeconomic and industry volume outcomes.
- Detailed segmentation analysis across material type, liner configuration, vehicle type, and geographic production distribution, with volume-to-value mapping that clarifies where revenue intensity diverges from unit volume and how pricing architectures differ across application categories.
- Competitive benchmarking that evaluates firm positioning through technology differentiation, capacity footprint, OEM qualification breadth, and recent strategic moves, providing a comparative lens for partnership evaluation and competitive response planning.
- Regulatory and standards impact assessment that translates emission mandates, material specification frameworks, and durability expectations into actionable engineering and procurement criteria.
- Supply chain and raw material dynamics review that examines casting feedstock availability, alloy pricing volatility, and logistics considerations influencing regional sourcing decisions.
- Identification of high-growth subsegments and emerging application vectors, supported by qualitative indicators that signal where demand intensity is likely to outpace incumbent capacity or where new material architectures may create displacement opportunities.
Intended Audience and Use Cases
This research is designed for multiple functional stakeholders who require synthesized intelligence rather than raw data tables. Corporate strategists can use the segmentation and competitive frameworks to evaluate market entry potential, partnership suitability, and portfolio alignment. Procurement and supply chain leaders can leverage the material and configuration analysis to structure sourcing negotiations that balance performance assurance with cost management across multi-year agreements. Engineering and product development teams benefit from the regulatory and standards mapping, which clarifies which technical thresholds are likely to become baseline requirements and where innovation headroom remains available. Investors and market analysts can utilize the forecast architecture and competitive positioning assessment to evaluate sector attractiveness, margin sustainability, and consolidation probability.
Connecting Intelligence to 2026 Decision Cycles
The strategic value of market intelligence is realized not through passive consumption but through active integration into planning cycles. As organizations finalize 2026 capital allocations, sourcing strategies, and engineering roadmaps, the automobile cylinder sleeve market presents a landscape where disciplined analysis directly informs competitive positioning. The 5.2 percent CAGR trajectory signals a market large enough to support multiple specialized players yet concentrated enough that capability gaps translate quickly into lost qualification opportunities. Material innovation, particularly around lightweight aluminum and composite formulations, is reshaping specification conversations, while regulatory tightening continues to elevate the importance of dimensional stability and thermal fatigue performance.
Companies that embed granular segmentation understanding, competitive capability mapping, and regulatory trajectory awareness into their 2026 decision frameworks will be better positioned to negotiate from a place of informed confidence. They will be able to identify which supplier relationships merit long-term commitment, which material transitions warrant accelerated validation investment, and which regional capacity shifts may alter logistics cost structures or lead-time reliability. The full research report preserves the detailed regional revenue distributions, application-specific growth vectors, and competitive share constructs required to execute these judgments with precision, ensuring that strategic conclusions rest on verified data rather than approximation.
Accessing the Complete Intelligence Asset
This preview has outlined the analytical terrain, demonstrated the interplay between macro trajectory and micro engineering requirements, and highlighted the competitive dynamics that will define the market structure through 2032. The complete PW Consulting Automobile Cylinder Sleeve Market research report builds on this foundation with granular segmentation data, regional capacity and revenue distributions, pricing and margin analysis, detailed company profiles, and forward-looking scenario modeling. All core tables, regional breakdowns, application-level growth vectors, and material segment revenue constructs are presented in the full deliverable to support rigorous strategic review.
For organizations preparing 2026 sourcing strategies, capacity plans, or technology investment roadmaps, the complete report provides the evidentiary depth needed to convert market observation into executable strategy. Readers seeking the full segmentation matrices, regional production and consumption distributions, competitive share constructs, and scenario-based forecast tables are encouraged to access the complete report at the source webpage, where the complete dataset and accompanying analytical commentary are available for download and internal distribution.
For detailed analysis of this topic, please visit the official page: Automobile Cylinder Sleeve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


