



PW Consulting Report: Trans-Resveratrol Market Hits $84M in 2025, Projected 8.9% CAGR to $152M by 2032

Navigating the Trans-Resveratrol Market in 2026: Strategic Imperatives from PW Consulting
The global landscape for trans-resveratrol is undergoing a structural transformation. As consumer preference shifts decisively toward clinically substantiated longevity ingredients and functional wellness solutions, the industry is entering a phase where supply chain agility, ingredient differentiation, and strategic capital allocation will dictate competitive advantage. PW Consulting has released its latest comprehensive research on the trans-resveratrol market, designed specifically to equip executives, product developers, and supply chain strategists with the analytical rigor required to navigate 2026 and the forecast horizon through 2032.
Worldwide Unbleached Parchment Market
This article serves as a strategic preview of that research. It outlines the macroeconomic trajectory, the competitive architecture shaping the market, the operational realities of raw material sourcing, and the disciplined analytical framework that defines our methodology. While we highlight the structural dynamics that demand executive attention, readers seeking precise forecasts, regional granularities, and segment-level growth rates will find the complete intelligence embedded within the full report. This preview is calibrated to demonstrate the analytical depth of our work while directing you to the source for the comprehensive dataset required to inform capital allocation, portfolio strategy, and procurement decisions in the year ahead.
Worldwide Mini CNC Router Market
The Macro Trajectory: Scale, Momentum, and the 2026 Inflection Point
The trans-resveratrol market has demonstrated consistent expansion over the historical observation window, with revenue progression reflecting both sustained demand from established channels and gradual penetration into adjacent applications. From a baseline of approximately 52.1 million USD in 2020, the market advanced through 56.48 million USD in 2021, 63.55 million USD in 2022, and 67.24 million USD in 2023, before reaching 73.97 million USD in 2024 and climbing to 84.0 million USD in 2025. This progression reflects not only volume expansion but also incremental value migration as manufacturers upgrade purity standards, adopt branded delivery systems, and respond to increasingly stringent quality expectations from downstream buyers.
Business Empowerment Support Service Market
Looking forward, the forecast period extending to 2032 projects continued growth at a compound annual growth rate of 8.9 percent. The trajectory indicates a sequential climb from an estimated 88.9 million USD in 2026, through 100.32 million USD in 2027 and 104.9 million USD in 2028, to 120.19 million USD by 2029. The scale reaches 130.43 million USD in 2030, further advancing to 140.4 million USD in 2031 and concluding at 151.9 million USD in 2032. The pace of expansion accelerates notably as the market moves from the early-forecast phase into the late-forecast horizon, signaling that adoption curves are building rather than plateauing. For decision-makers, this pattern suggests that early-mover positioning in capacity planning, supplier qualification, and application innovation will carry compounding returns as the market matures.
It is important to emphasize that the headline trajectory is merely the starting point for strategic analysis. The full report disaggregates these figures across multiple analytical dimensions to reveal where growth concentrates, which sub-segments exhibit the highest margin resilience, and how regional demand profiles diverge in terms of both volume and pricing dynamics. Executives who rely solely on aggregate growth rates risk misallocating resources toward saturated channels or underestimating pockets of structural opportunity. The complete dataset within the research report provides the segmentation-level detail required to translate a market-wide CAGR into actionable, channel-specific investment guidance.
Competitive Architecture: Strategy Profiles of Market Participants
The trans-resveratrol competitive landscape is characterized by a blend of ingredient specialists, vertically integrated manufacturers, and multinational players with strong clinical and regulatory capabilities. The market exhibits a moderate degree of concentration, with the top three participants accounting for roughly 24.6 percent of overall revenue and the top five collectively representing about 26.2 percent. This structure indicates a fragmented yet strategically active field in which differentiation through purity standards, sourcing provenance, delivery technology, and intellectual property positioning has become the primary mechanism for capturing premium value.
Among the multinational layer, dsm-firmenich stands out through its resVida® offering, a high-potency nature-identical trans-resveratrol ingredient marketed at 99 percent purity and positioned for healthy aging and cardiovascular health applications. The company’s positioning reflects a strategy centered on clinical credibility, supply chain resilience, and integrated wellness portfolios. This approach places emphasis not only on ingredient specification but also on formulation compatibility and brand trust within downstream supplement and functional nutrition channels.
Evolva, operating from Switzerland through its Danstar Ferment heritage, has established a differentiated position with Veri-te®, a fermentation-derived trans-resveratrol ingredient achieving purity above 98 percent. Its value proposition spans nutraceutical, cosmetic, and functional food applications, and its fermentation pathway provides a distinct narrative around consistency, scalability, and sustainability compared with botanical extraction routes. In a market where supply reliability and specification reproducibility are increasingly scrutinized, fermentation-derived options carry strategic relevance for buyers seeking to de-risk raw material variability.
Sabinsa Corporation has historically built strong credibility in standardized botanical extracts and nutritional ingredients, and its trans-resveratrol portfolio continues to reflect that positioning. The company’s emphasis on standardized extracts and health-oriented applications aligns with demand from manufacturers prioritizing proven botanical standardization and established supply relationships. Ardent Sciences, headquartered in Indiana, focuses on plant-extracted trans-resveratrol powders and solutions derived from botanical sources, catering primarily to dietary supplement formulations. Maypro Industries contributes branded delivery systems and extracts designed for supplement manufacturers, reflecting a market segment where delivery technology and ingredient branding can influence formulation selection and shelf positioning.
Layn Natural Ingredients and JF Natural continue to expand their respective footprints through botanical trans-resveratrol extracts and natural powders aimed at nutraceutical applications. Their strategies underscore a broader industry theme: a growing bifurcation between natural extraction pathways and alternative production methods, each with distinct cost structures, traceability narratives, and quality assurance requirements. On the international manufacturing side, Chengdu Yazhong Bio-pharmaceutical provides pharmaceutical-grade products and extracts from China, while Laurus Labs, based in Hyderabad, contributes trans-resveratrol derivatives and bulk ingredients relevant to APIs and supplement supply chains. Longevir operates within the European Union, supplying bulk and wholesale trans-resveratrol from Japanese knotweed or grape sources under GMP standards. Collectively, these participants illustrate how geographic specialization, regulatory posture, and production methodology are converging to shape customer selection criteria.
The full report provides detailed competitive profiles, positioning maps, and an assessment of strategic vulnerabilities and opportunities for each profiled company. These profiles are constructed not as static company summaries but as strategic evaluations that examine how each participant’s offering aligns with demand-side priorities, where pricing power is likely to persist, and where substitution risk may intensify as alternative production routes mature. Readers seeking to benchmark their own positioning, assess supplier risk, or identify potential partnership structures will find the complete competitive analysis essential.
Raw Material Dynamics and the 2025-2026 Supply Signal
Trans-resveratrol sourcing sits at the intersection of agricultural output, extraction economics, and manufacturing continuity. Recent reporting underscores that the input environment is not uniformly directional; it is increasingly defined by contrasting signals across raw material streams. In February 2025, USDA NASS reported that California’s 2024 grape crush totaled 2,918,158 tons, falling 25.2 percent below the prior year. Over the same period, the average price of all grape varieties declined 4.5 percent to 992.51 USD per ton. Red wine grapes averaged 1,311.15 USD per ton, down 2.6 percent, while white wine grapes averaged 698.61 USD, down 4.8 percent. For the trans-resveratrol market, this combination produces a nuanced pricing signal: grape-based feedstock prices softened, yet the sharp contraction in crush volume reduces the available flow of grape-skin and pomace streams used in extraction. The result is a market where lower headline feedstock prices may not automatically translate into lower effective ingredient costs if extraction-grade material becomes scarcer or more constrained in quality consistency.
A more localized but strategically relevant update came from El Dorado County in July 2025, which reported that 2024 wine grape production declined 5.1 percent to 5,529 tons from 5,826 tons in 2023. At the same time, the average price per ton increased 3.4 percent, moving from 1,985 USD to 2,053 USD. The report also noted that total crop value declined 16.9 percent and approximately 16.5 percent of tonnage was not sold or utilized. This pattern illustrates the complexity of raw material assessment: regional pricing can rise even as availability tightens, and unsold or unused tonnage may reflect quality sorting, market access constraints, or shift in utilization patterns rather than simple abundance. For procurement teams and ingredient strategists, the strategic lesson is that aggregate price movements can be misleading without context on grade availability, extraction yield, and the continuity of supply from specific growing regions.
On the strategic and financial side, the industry’s larger participants are signaling a focus on capital discipline and supply chain durability. In December 2025, dsm-firmenich completed its 1.08 billion EUR share buyback programme ahead of schedule, with plans to cancel over 12 million shares in early 2026 as part of its broader capital allocation and supply chain resilience measures. While a buyback is a corporate finance action rather than a direct market input, it reflects a strategic environment in which leading players are managing balance sheet structure and long-term operational resilience in parallel. For competitors and customers alike, such actions can influence investment appetite, capacity expansion timing, and the strategic patience required during periods of raw material transition.
The full research report incorporates these developments within a broader synthesis of sourcing risk, input volatility, and supply continuity scenarios. It examines how fluctuations in grape crush volume, regional pricing dispersion, and unused tonnage interact with extraction economics, and it provides the analytical context necessary to differentiate between temporary pricing relief and durable cost advantages. The report also addresses how fermentation-based and plant-extraction pathways may respond differently to agricultural variability, enabling readers to evaluate supplier diversification strategies with greater precision.
Segmentation Framework and Application Realities
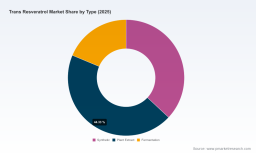
A defining feature of trans-resveratrol market analysis is the divergence between value concentration and volume concentration across application channels. The full report maps these dynamics across product type, application area, and regional demand profiles, with the objective of helping decision-makers understand where value migrates as the market matures. At a high level, the market structure indicates that dietary supplements continue to represent the largest application share, followed by cosmetics, food and beverage, and other applications. In parallel, the type segmentation reflects a market in which plant extract-based and synthetic pathways both maintain relevance, with fermentation-derived solutions occupying a strategically important and growing position.
The strategic importance of this segmentation is not simply descriptive; it is diagnostic. Different application channels exhibit distinct purchasing criteria, regulatory exposure, formulation constraints, and margin architectures. Dietary supplement manufacturers typically prioritize standardization, label credibility, bioavailable delivery narratives, and supplier auditability. Cosmetic and personal care applications often place greater emphasis on purity, stability, and sensory compatibility, while food and beverage formulations introduce additional complexity related to dosage, taste, and processing tolerance. These differences mean that the same headline growth rate can conceal very different commercial realities across channels. A supplier that is well positioned in one application segment may face different competitive pressures, margin dynamics, or adoption hurdles in another.
Similarly, the product type mix is more than a technical distinction. Plant extraction, synthetic production, and fermentation each carry distinct cost curves, scalability profiles, provenance narratives, and regulatory interpretations. Buyers increasingly compare these pathways not just on price per kilogram, but on total cost of qualification, batch-to-batch consistency, sustainability positioning, and the credibility of the ingredient story they can communicate to end consumers. As the forecast period progresses, the relative attractiveness of each pathway is likely to shift as production technology improves, regulatory expectations evolve, and application formats become more demanding. The complete report provides the segmented growth picture and structural interpretation needed to assess which pathways are likely to command premium positioning in specific downstream markets and where substitution pressure may increase.
Regional demand patterns further complicate the segmentation picture. The full report examines regional purchasing behavior, channel maturity, and the pace at which emerging markets adopt trans-resveratrol across different application types. Because regional dynamics often differ sharply in terms of regulatory environment, distribution infrastructure, and consumer trust in active ingredients, aggregate global figures do not adequately guide localization strategy. The report’s regional analysis is designed to support decisions related to market entry prioritization, distributor selection, and product positioning at the level of granularity that operational planning requires.
Strategic Use Cases for the 2026 Decision Cycle
The primary value of this research lies in its orientation toward operational and strategic decision-making rather than descriptive reporting. For executives planning 2026 activity, the report is structured to support several core use cases. First, it enables portfolio strategy by identifying where growth is structurally concentrated and where channel maturity suggests the need for product refinement, repositioning, or selective exit. Second, it supports supplier and sourcing strategy by mapping production pathways, qualification requirements, and the strategic implications of agricultural variability on ingredient continuity. Third, it informs competitive positioning by clarifying how leading participants differentiate through purity, branding, delivery systems, and regulatory readiness, and where gaps may create opportunity for new entrants or existing players seeking to expand share.
A further use case is capital and investment planning. The forecast trajectory through 2032 provides a multi-year lens for evaluating whether to invest in capacity, pursue vertical integration, negotiate long-term supply agreements, or build application-specific partnerships. Because the market’s growth pattern is not linear across all segments, decision-makers need segmentation-level insight to avoid overbuilding in slower-growth channels or underinvesting in applications with stronger structural tailwinds. The report’s framework is intended to reduce the risk of such misallocation by connecting market growth to actionable dimension-specific interpretation.
Finally, the report supports risk management in a market where input dynamics, regulatory expectations, and competitive differentiation are evolving simultaneously. Understanding how grape crush volume shifts, regional pricing dispersion, and unsold tonnage interact with extraction yields, and how fermentation-based supply may compare with botanical pathways under variability, is essential for designing resilient sourcing and formulation strategies. The research integrates these considerations into a broader strategic synthesis that can be used to stress-test supply assumptions and inform contingency planning.
What to Expect in the Full Report
This preview highlights the structural contours of the trans-resveratrol market and the strategic logic underpinning PW Consulting’s research. The full report extends this foundation into a comprehensive, decision-ready intelligence package. It provides the complete market size progression across historical and forecast years, a detailed segmentation analysis across product type, application, and regional demand, and a structured competitive assessment of the companies shaping the market. It also synthesizes the raw material environment, regulatory and capital-allocation signals, and the application-specific purchasing dynamics that determine where value is created and defended.
Because effective strategy depends on precision, the report deliberately avoids overgeneralization. Regional and application-level splits, type-level comparisons, concentration metrics, and scenario-based interpretations are included to enable readers to tailor their decisions to the specific segments and geographies relevant to their businesses. The goal is to provide enough depth to support procurement negotiations, product development planning, market entry evaluation, and competitive benchmarking, while maintaining the analytical discipline required for executive decision-making.
The trans-resveratrol market is moving from a phase defined primarily by ingredient availability to one increasingly shaped by differentiation, resilience, and strategic positioning. In that environment, aggregate growth figures are necessary but insufficient. The complete report provides the segmentation, competitive architecture, sourcing intelligence, and interpretive framework needed to convert market momentum into informed corporate action. For leaders preparing for the 2026 decision cycle and planning beyond it, the full research offers the structured intelligence required to act with confidence rather than inference.
For detailed analysis of this topic, please visit the official page: Trans Resveratrol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


