



PW Consulting: Vinyl Terminated PDMS Market to Hit $904M by 2032, Driven by 4.7% CAGR

Strategic Intelligence for the Vinyl Terminated Polydimethylsiloxane Market Through 2032
Executive Overview: Why This Market Requires Precision Intelligence Now
The global landscape for vinyl terminated polydimethylsiloxane is entering a phase of structural maturation where incremental volume gains will be dictated by formulation precision, supply chain resilience, and regulatory navigation rather than raw capacity expansion. For executives planning capital allocation, sourcing strategies, and product roadmap decisions through the end of the decade, surface-level market summaries are no longer sufficient. This report delivers the analytical rigor required to separate transient cyclical signals from durable secular shifts, providing a decision-ready framework for 2026 and beyond. Over the historical review window, the market has demonstrated steady expansion, moving from a baseline of 500.0 million dollars in 2020 to an estimated 655.0 million dollars in 2025. The trajectory reflects consistent demand absorption across industrial silicone architectures, with the compound annual growth rate projected at 4.7 percent across the 2026 to 2032 forecast horizon. By the close of the forecast period, market revenue is positioned to approach the 904.0 million dollar threshold. These figures establish a clear growth envelope, but the strategic value of this research lies in unpacking what drives variance within that envelope, where margin pressure concentrates, and which operational levers will determine competitive positioning.
Market Trajectory and the 2026 Decision Window
The forecast period begins at an estimated 682.77 million dollars in 2026 and advances through 728.53 million dollars in 2027, 736.08 million dollars in 2028, and 784.5 million dollars in 2029 before reaching 834.76 million dollars in 2030, 861.59 million dollars in 2031, and 904.0 million dollars in 2032. While the headline growth path signals a healthy expanding addressable market, the more consequential insight for corporate planning is the interaction between demand rhythm and input cost volatility. Growth will not be uniformly distributed across periods or segments; instead, it will be shaped by formulation requirements, regional manufacturing footprints, and the ability of participants to manage upstream constraints without sacrificing specification integrity. For decision-makers, the 2026 starting point is particularly important because it coincides with an environment where raw material dynamics and regulatory scrutiny are simultaneously reshaping cost structures. The report uses this inflection point to map future revenue progression against plausible operational scenarios, helping leaders evaluate whether to lock in supply commitments, rebalance product mix, or invest in alternative sourcing pathways. Rather than presenting growth as a single linear line, the analysis frames it as a function of segment responsiveness, regional absorption patterns, and the strategic behavior of incumbents and challengers.
Competitive Architecture and Strategic Posture
The competitive field is characterized by a mix of specialty manufacturers, distributed suppliers, and regional producers, each pursuing distinct positioning within the vinyl terminated polydimethylsiloxane value chain. Market concentration metrics indicate that the three largest firms hold approximately 35.0 percent of total revenue, while the five largest participants account for roughly 45.0 percent. This structure suggests a market that is neither fully consolidated nor highly fragmented, creating an environment where scale advantages matter but do not entirely dictate outcomes. Execution quality, grade specificity, technical support, and supply reliability remain decisive differentiators. Several leading companies define the current competitive baseline. Silsource Inc., based in the United States, operates as a manufacturer and distributor of vinyl terminated polydimethylsiloxane for industrial silicone applications, including the stocking of specific grades such as SILSOURCE VF-65000. Its presence underscores the importance of grade-level availability and responsive inventory management in meeting industrial specification requirements. SiSiB Silicones, headquartered in China, is a leading manufacturer of vinyl silicone fluids and offers products such as SiSiB VF6030 for addition-cure systems, reflecting a strong orientation toward formulation compatibility and process integration. Gelest, Inc., also based in the United States, specializes in supplying vinyl terminated polydimethylsiloxane grades like DMS-V35 and DMS-V42 for both research and industrial use, highlighting the market’s continued reliance on technically differentiated product portfolios. Siwin Silicone, another China-based producer, focuses on vinyl terminated polydimethylsiloxane vinyl silicone oil for HTV silicone rubber and addition-cure applications, indicating steady demand linkages with rubber compounding and elastomer processing. Kemi-Works Chemical Co., Ltd., also in China, positions itself as a supplier of vinyl terminated polydimethylsiloxane as a reactive intermediate for silicone fluids and polymers, reinforcing the role of the material as a building block within broader polymer architectures. Silibase Silicone, also based in China, manufactures vinyl-terminated polydimethylsiloxane for industrial and specialty silicone products, extending the competitive field into specialty-grade applications where specification control carries outsized value. Together, these participants illustrate a competitive landscape in which technical credibility, grade consistency, and application-specific know-how are as important as volume throughput. The report examines how these players are positioned relative to one another, where customer switching costs remain high, and which operational capabilities are likely to determine share dynamics over the forecast period.
Upstream Dynamics: Raw Material Inputs and Cost Architecture
The economics of vinyl terminated polydimethylsiloxane production are tightly linked to the availability and pricing of foundational inputs, most notably octamethylcyclotetrasiloxane, commonly referred to as D4, which serves as a primary building block in the production pathway. Any disruption in D4 supply, or any shift in its regulatory treatment, cascades directly into manufacturing cost structures and grade availability. The report integrates this dependency into the broader supply-chain analysis, showing how upstream constraints can influence margin profiles even when downstream demand remains robust. At the same time, the input cost environment is exhibiting measurable firming. The silicon tetrachloride price index rose 8.09 percent quarter-over-quarter in the first quarter of 2026, driven by constrained availability and elevated energy costs. That upward pressure continued into the second quarter, with silicon tetrachloride prices firming across all regions in May 2026 and sustaining the trajectory established earlier in the year. These movements are significant because they affect the cost base for silicone intermediates and, by extension, the competitive calculus for producers and buyers alike. For procurement leaders and financial planners, the implication is clear: cost assumptions built on static historical averages will underestimate near-term pressure. The analysis uses these raw material signals to frame sensitivity around production economics, regional sourcing trade-offs, and inventory strategy. It also explores how different participants may respond through pricing adjustments, grade substitution, contract structuring, or vertical integration decisions. By embedding raw material dynamics within the market narrative rather than treating them as isolated background noise, the report provides a more realistic foundation for 2026 planning.
Regulatory Context and the Risk of Overcorrection
Regulatory developments are becoming an increasingly material factor in market interpretation, particularly where chemical intermediates intersect with public policy scrutiny. D4 is currently facing potential overregulation scrutiny under the U.S. EPA Manufacturer Requested Risk Evaluation process, with advocacy efforts underway to avoid unbalanced policy impacts on silicone supply chains. This dynamic introduces a layer of uncertainty that goes beyond ordinary cost fluctuation: regulatory outcomes can reshape permissible use conditions, alter downstream adoption patterns, and influence the relative attractiveness of certain formulation pathways. The strategic importance of this issue lies not in predicting any single regulatory outcome, but in preparing for a range of plausible scenarios. Markets that depend on well-established intermediates can experience disproportionate disruption if policy interventions are applied without full consideration of substitution feasibility, performance requirements, and supply continuity. The report addresses this by mapping the regulatory conversation into the broader market dynamics section, evaluating how different interpretations of risk could affect sourcing decisions, product development priorities, and regional manufacturing preferences. For executives, the key takeaway is that compliance strategy and commercial strategy can no longer be treated as separate workstreams. A supplier’s ability to navigate regulatory exposure, maintain documentation rigor, and communicate risk management credibly may become a differentiator in bids and long-term agreements. The analysis therefore examines how regulatory anticipation is influencing behavior across the value chain, even before final determinations are made.
Report Architecture and Operational Applicability
This market research is designed as a working intelligence asset rather than a high-level summary. It provides a structured, decision-oriented breakdown of the vinyl terminated polydimethylsiloxane market across multiple analytical dimensions, each tied to practical corporate use cases. The report includes:
- A historical review and forecast model that traces revenue progression from 2020 through 2032, with the forecast window anchored in 2026 to support near-term planning and longer-range capital decisions.
- A segmentation analysis that examines how demand distributes across product viscosity categories and application domains, helping leaders identify where growth intensity and specification requirements diverge.
- A regional assessment that compares market absorption across major geographies, enabling more precise choices about distribution focus, supply hub placement, and market-entry prioritization.
- A competitive profiling section that evaluates key participants by operating model, grade coverage, and strategic orientation, supporting benchmarking, partnership evaluation, and threat assessment.
- A supply-chain and input-cost review that connects raw material behavior, including D4 dependency and silicon tetrachloride pricing movements, to production economics and procurement strategy.
- A regulatory and risk-dynamics discussion that places emerging policy scrutiny in context and outlines how companies can prepare for uncertainty without overcommitting to any single scenario.
Each section is built to be referenced directly in commercial planning, sourcing reviews, and product strategy sessions. The goal is to reduce the gap between market intelligence and operational action, giving teams a shared evidence base for evaluating trade-offs.
Segmentation Insight: Matching Growth to Specification
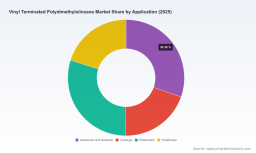
While aggregate market size provides the strategic backdrop, the more actionable intelligence lies in understanding how demand is distributed across type and application categories. In the type dimension, the market reflects a clear hierarchy of viscosity-based demand, with low viscosity and medium viscosity categories representing the larger shares of revenue and high viscosity occupying a smaller but still material position. This structure matters because viscosity selection is often tied directly to end-use performance requirements, processing conditions, and compatibility with cure systems. As a result, volume distribution across viscosity categories is not merely a statistical breakdown; it is a signal of where formulation intensity, technical service, and inventory granularity will create the most value. In the application dimension, the market is similarly diversified. Adhesives and sealants, elastomers, coatings, and healthcare applications each contribute distinct demand profiles, with different sensitivity to specification control, regulatory framing, and raw material cost pass-through. Some application areas are more volume-driven, while others depend more heavily on grade reliability and documentation support. The report analyzes these differences to help managers anticipate where demand will be more elastic, where customers will prioritize supply continuity, and where premium positioning may be more sustainable. By linking segmentation patterns to operational implications, the research enables more precise resource allocation. Rather than treating the market as a single pool of opportunity, the report shows how to prioritize by the intersection of volume potential, margin behavior, and strategic fit.
Regional Structure and Sourcing Strategy
Revenue distribution across regions further shapes sourcing and expansion decisions. North America, Europe, and Asia Pacific represent the largest regional pools of demand, while Latin America and the Middle East and Africa form smaller but strategically relevant markets. The relative size of each region influences not only sales potential but also logistics design, inventory positioning, and exposure to local input-cost and regulatory conditions. The report treats regional analysis as a decision tool rather than a static ranking. It examines how regional demand concentration interacts with shipping complexity, local manufacturing presence, and differing regulatory environments. For companies evaluating where to deepen customer engagement or where to place supply buffer stock, this regional framing helps identify which markets warrant closer integration and which can be served through more flexible distribution models. This regional perspective is especially relevant in a period when input costs are firming and regulatory attention is intensifying. Different regions may respond differently to the same cost pressure or policy signal, which means that a uniform global strategy may underperform relative to a regionally calibrated approach. The analysis supports that calibration by mapping where demand resilience and supply vulnerability are most likely to diverge.
Strategic Recommendations for 2026 Planning
The combined evidence points to several practical priorities for organizations operating in or adjacent to this market.
- Align sourcing commitments with grade-level demand realities rather than relying solely on aggregate volume forecasts, since viscosity and application requirements can shift the effective opportunity set.
- Build cost models that explicitly incorporate upstream input volatility, especially around D4 dependency and silicon tetrachloride price behavior, so that margin planning reflects current conditions instead of outdated baselines.
- Prepare regulatory response playbooks that consider multiple outcomes for D4 scrutiny, preserving optionality in formulation, sourcing, and customer communication.
- Use competitive profiling to identify where incumbents are strongest in grade availability and technical support, and where gaps may create entry or expansion opportunities.
- Evaluate regional exposure in the context of both demand size and supply-chain resilience, ensuring that distribution and inventory decisions match the risk profile of each geography.
- Treat market concentration data as a guide to competitive intensity rather than a fixed ceiling, since the field remains open enough for differentiated execution to alter share outcomes over time.
These recommendations are designed to translate market structure into operating choices. The report provides the underlying analysis needed to prioritize them in a way that matches each organization’s product footprint, customer base, and risk tolerance.
Conclusion: From Market Visibility to Decision Advantage
The vinyl terminated polydimethylsiloxane market is expanding within a definable growth corridor, but the real strategic challenge lies in navigating the forces that determine how that growth is distributed, priced, and secured. Between raw material firming, regulatory uncertainty, segmentation complexity, and a competitive field that rewards specification leadership, the decisions made in 2026 will shape competitiveness well into the late 2020s and early 2030s. This research is built to support those decisions with depth, structure, and operational relevance. It establishes the macro trajectory, including the progression from a 2025 base of 655.0 million dollars toward a 2032 estimate of 904.0 million dollars at a 4.7 percent compound annual growth rate, while deliberately leaving the most sensitive segmentation, regional, and company-level data for the full report. That design reflects a simple principle: executive confidence comes not from seeing every number in advance, but from knowing that the complete analytical framework is available when it is needed most. For teams that require detailed revenue splits, segment-level magnitudes, regional breakdowns, and company-specific competitive intelligence, the full report provides the comprehensive dataset and interpretive analysis necessary to act with precision. The summary presented here is intended to demonstrate the scope and rigor of the research while preserving the core quantitative intelligence for direct access through the source page, where the complete market model and supporting analysis can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Vinyl Terminated Polydimethylsiloxane Market
Collectibles Auction Services Market
Worldwide Automatic Setup Tent Market
Bike Spare Part Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


