



PW Consulting: Anti-Fog Coatings Market to Surpass $272.92M by 2032 at 3.5% CAGR

Anti-Fog Coatings Market 2026–2032: Strategic Intelligence for Capital Allocation and Product Roadmapping
The global anti-fog coatings market has entered a phase of structural maturation, where incremental volume growth is increasingly decided by formulation chemistry, substrate compatibility, regulatory shifts, and downstream OEM integration rather than broad-based demand expansion. For executives planning capital deployment, R&D prioritization, and regional sourcing strategies through the remainder of the decade, the difference between reactive positioning and proactive market leadership will hinge on how precisely they can read the interplay between hydrophilic performance requirements, sustainability mandates, and appliance-specific optical clarity thresholds. This introduction frames why a rigorously constructed market study is no longer a passive reference document but a decision-grade asset for 2026 strategy cycles.
Worldwide Respiratory Collector Market
From Volume Recovery to Value Discipline
Over the 2020–2025 historical window, the market demonstrated a clear trajectory of recovery and consolidation. Revenue climbed from approximately 163.15 million USD in 2020 to 215.0 million USD by 2025, reflecting not only post-pandemic normalization across optical, safety, and automotive supply chains but also the embedding of anti-fog functionality as a baseline expectation rather than a premium add-on. Moving into 2026, the forecast period signals a more measured pace of expansion. The overarching compound annual growth rate is tracked at 3.5 percent, with revenue projected to reach 217.29 million USD in 2026 and gradually advance toward 272.92 million USD by 2032. This growth profile is deliberately moderate, underscoring that top-line expansion will be earned through product endurance, regulatory alignment, and premiumized performance tiers rather than through aggressive volume plays alone.
Powder Tablet Press Mold Market
For strategists, the implication is clear. Budgeting and forecasting models that assume linear ramp-up will overstate short-term upside and underappreciate the segment-level divergence that defines the market. Some applications and substrates will see faster payback cycles because of embedded OEM validation and repeat procurement, while others will experience margin compression as formulation costs, compliance overhead, and processing complexity rise. A disciplined research baseline separates these trajectories, enabling leadership to allocate engineering resources, inventory positioning, and partnership investments where the probability-adjusted return is strongest.
Ceramic Watertight Concrete Market
What the Study Delivers Beyond Top-Line Estimates
A commercially useful market study must go past aggregate revenue and CAGR figures. It needs to translate market structure into operational levers that product managers, procurement leads, and corporate development teams can act upon. The full report is built around that operational logic. It maps how hydrophilic and permanent anti-fog chemistries are distributed across substrate families, where water-washable and abrasion-resistant systems create application-fit advantages, and which product types hold structural cost or performance advantages under specific manufacturing conditions. Rather than presenting segmentation as a static snapshot, the study connects each segment to real-world adoption drivers, process constraints, and switching costs that influence procurement behavior.
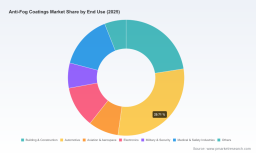
Equally important is the treatment of end-use demand. The analysis dissects how building and construction, automotive, aviation and aerospace, electronics, military and security, medical and safety industries, and ancillary sectors each approach fog control with different performance thresholds, certification burdens, and durability expectations. Readers gain a clarified view of where optical clarity, heat stability, UV resistance, and long-term hydrophilic retention matter most, and where cost-efficiency and ease of application dominate purchasing decisions. By layering substrate suitability, product chemistry, regional procurement patterns, and end-use specifications into a single analytical framework, the report equips teams to evaluate not only where demand is forming, but how it is likely to be served and monetized.
The study also incorporates competitive intelligence that is practical rather than ceremonial. It examines the positioning of leading participants such as FSI Coating Technologies, Momentive Performance Materials, Hydromer Inc., NSG Group, and WeeTect Material Limited, alongside recent market activity from firms including Cosmo Films, Solabs Nanotechnology GmbH, PPG Industries, Hanwha Chemical, and 3M. The intent is not to catalog announcements, but to interpret what they reveal about formulation priorities, OEM alignment, sustainability direction, and technology differentiation. Recent activity—such as updated premium coating highlights, transparent BOPET lidding film introductions for food packaging, the emergence of passive thermal anti-fog solutions, water-based eco-friendly formulations for automotive windshields, capacity expansion for waterborne coatings with green chemistry incentives, and the integration of embedded anti-microbial properties in next-generation AR headset coatings—collectively signals where the industry is pushing its technical frontier.
Why 2026 Decisions Require Segmented Precision
The strategic urgency of 2026 lies in the widening gap between broad market growth and segment-level opportunity. Companies that treat the market as a single demand pool risk misallocating resources to applications where regulatory friction, raw material cost structures, or processing complexity erode profitability. At the same time, firms that understand where glycerol esters remain the practical workhorse chemistry due to low raw material cost and established food-contact acceptability, and where proprietary in-house anti-fog technologies are being adopted to reduce supply chain expenses, can structure sourcing and formulation strategies with greater leverage.
This is particularly relevant for organizations navigating sustainability and compliance transitions. Demand for eco-friendly, water-based, and otherwise compliant coatings is reshaping both automotive windshield applications and high-end optical and automotive markets, supported in some regions by government incentives for green chemistry. At the same time, expert lens treatments and coatings can elevate production costs, making supply chain improvements and proprietary processing capabilities a meaningful source of margin protection. The market study provides the evidentiary backdrop required to decide when to invest in formulation upgrades, when to secure OEM-approved product lines, and when to prioritize geographic or substrate exposure that offers faster route-to-market clearance.
Competitive Structure and the Reality of Market Share
A frequently underestimated strategic input is market concentration. With CR3 at 24.6 percent and CR5 at 26.2 percent, the industry is fragmented enough to preserve innovation entry points and customer-specific formulation opportunities, yet consolidated enough that established players command meaningful technical credibility, certification track records, and OEM relationships. This structure matters for both incumbents and entrants. For incumbents, it rewards continued differentiation through permanent performance-based systems, abrasion resistance, optical clarity, and application-specific approvals. For challengers, it suggests that broad commodity positioning is unlikely to outperform targeted, performance-validated solutions in high-specification segments.
The profiled companies illustrate how differentiation is being built. One global leader emphasizes permanent performance-based, water-washable anti-fog coating systems and abrasion-resistant coatings across polyester film, plastics, glass, mirrors, and metal substrates, with product lines approved for demanding OEM environments. Another major supplier focuses on silicone-based anti-fog coatings that deliver long-term hydrophilic performance, high transparency, and optical clarity for automotive lighting, sensors, ADAS, safety glasses, visors, ophthalmics, and electric vehicle front-end modules. A third manufacturer builds its identity around premium hydrophilic anti-fog and condensation control coatings with heat- and UV-stable options for medical and safety devices, eyewear, sensors, LEDs, automotive windshields, and industrial substrates. A fourth provider contributes high-performance sol-gel hybrid anti-fogging coatings designed for automotive cameras, ADAS, surveillance cameras, optical filters, lenses, and plastic substrates. A fifth developer targets hydrophilic anti-fog coatings applied through spraying or dipping for plastic sheets, films, and injection-molded visors, with emphasis on permanent anti-fog and anti-scratch performance for helmet visors, face shields, goggles, mirrors, and freezer displays.
Read together, these profiles show that competitive advantage is not simply a matter of price, but of performance durability, substrate fit, application approval, and increasingly, environmental and safety compliance. Strategic planning should therefore evaluate partnerships, acquisitions, and internal development not only through the lens of market size, but through the lens of specification capture and OEM trust.
How to Use This Research in 2026 Planning Cycles
The study is designed to support multiple decision pathways at once. Product leaders can use the segmentation mapping to identify which substrate and product-type combinations warrant deeper formulation investment. Procurement and supply chain teams can use the demand patterns to anticipate where repeat buying, certification cycles, and durability requirements will pressure lead times and inventory planning. Corporate development teams can use the competitive and regulatory context to assess where green chemistry momentum, capacity expansion, and next-generation thermal or embedded-property coatings are likely to reshape supplier options. And executives overseeing regional exposure can use the geographic distribution of demand to weigh where concentration offers efficiency against where diversification reduces dependency risk.
Because the report is structured to preserve segment-level distinctions without flattening them into headline numbers, it allows leadership to conduct scenario planning with greater confidence. Teams can compare a strategy centered on automotive-adjacent optical performance against one emphasizing medical and safety device compatibility, and they can evaluate whether premium permanent coatings or more cost-efficient hydrophilic systems align better with their target customer base. The value of the research lies in making those trade-offs explicit rather than speculative.
What Remains in the Full Study
To preserve analytical integrity while still driving action, this introduction deliberately omits the detailed regional and application breakdowns, segment-specific revenue figures, and granular product-type proportions that constitute the core intelligence of the full report. Those figures are not ornamental. They are the decision scaffolding that enables precise market entry timing, budget sizing, and competitive positioning. Access to the complete dataset is necessary for teams that need to compare specific regional demand intensity, segment revenue shares, and end-use prioritization without relying on approximations.
The full study also expands the competitive landscape beyond the most visible leaders, providing a wider view of supplier positioning, application-specific strengths, and recent product and partnership activity that shapes near-term buyer behavior. For organizations preparing 2026 budgets, roadmap approvals, and regional sourcing reviews, that expanded view is where the difference between good strategy and implementable strategy is usually found.
Final Strategic Takeaway
The anti-fog coatings market is not defined by dramatic volatility, but by the cumulative effect of formulation performance, regulatory direction, OEM specification capture, and substrate-level manufacturing realities. With moderate overall growth and a fragmented-but-concentrated competitive structure, the winners in 2026 will be those who act on segment-level clarity rather than aggregate momentum. The full market study provides that clarity, pairing macro trajectory with operational segmentation, competitive interpretation, and recent industry signals that matter for product, procurement, and corporate strategy. For decision-makers who need to convert market visibility into concrete investment and partnership choices, the complete report is the necessary next step.
For detailed analysis of this topic, please visit the official page: Anti-Fog Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


