



PW Consulting Projects Construction Chemicals Market to Hit $101.5B by 2032 at 6.5% CAGR

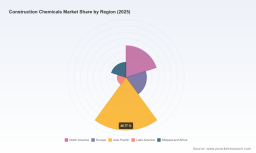
Navigating the Next Wave: Strategic Intelligence for the Construction Chemicals Market (2026-2032)
The global construction chemicals industry stands at a critical inflection point. As infrastructure aging, urbanization trends, and sustainability mandates converge, the sector is transitioning from a commoditized materials space into a technology-driven, performance-oriented ecosystem. For executives, investors, and strategic planners operating in 2026, understanding this transition is no longer optional. It is a prerequisite for capital allocation, portfolio positioning, and competitive resilience.
Worldwide Automatic Transport Robot Market
This market research report delivers a comprehensive, data-anchored blueprint of the construction chemicals landscape, covering historical performance from 2020 through 2025 and extending forward-looking projections across the 2026-2032 forecast horizon. The analysis is designed to cut through market noise, quantify structural drivers, and map the competitive architecture that will define industry winners in the coming years.
Worldwide Building ETFE (ethylene-tetrafluoroethylene copolymer) Membrane Market
Executive Market Trajectory and Structural Growth Context
The industry has demonstrated consistent expansion over the past half-decade, supported by steady construction activity, regulatory upgrades in building performance, and incremental adoption of advanced chemical formulations. Historical revenue progression from 2020 to 2025 reflects a sector that has navigated supply chain volatility, raw material price fluctuations, and shifting project pipelines while maintaining a clear upward trajectory. Building on this foundation, the forecast period is projected to sustain a compound annual growth rate of 6.5 percent, with market valuation advancing toward the 100 billion dollar threshold by the close of the forecast window.
Worldwide Rad-hard Semiconductor Market
This growth profile is not uniform across time or geography. The acceleration curve reflects the interplay of infrastructure stimulus programs, commercial and residential construction cycles, and the increasing specification of high-performance chemical solutions that extend asset life, reduce maintenance burdens, and improve structural reliability. For decision-makers, the strategic implication is clear: the market is large enough to absorb new entrants and product innovations, yet fragmented and regionally nuanced enough that generic strategies will underperform without localized execution and technical differentiation.
The report quantifies these macro trends while deliberately reserving granular regional and application-level breakdowns for the full dataset. This allows leadership teams to validate directional assumptions before diving into the specific splits that will inform country-level entry plans, channel strategies, and segment prioritization.
Industry Dynamics: Raw Material Pressures, Regulatory Shifts, and the Sustainability Imperative
The operating environment for construction chemical manufacturers and suppliers is being reshaped by simultaneous pressures on the cost side and the compliance side. Raw material dynamics have become a recurring strategic variable rather than an occasional disruption. In early 2026, pricing for MDI products in North America moved upward by 22 to 35 cents per pound, driven by supply constraints and broader raw material shortages. At the same time, dimethyldichlorosilane prices climbed 28 percent year-on-year in the first quarter of 2026, reflecting outages at Chinese chlor-alkali units and elevated tariffs on silicon metal. In Northeast Asia, upstream benzene and ethylene costs contributed to a 15.3 percent upward movement in styrene pricing during the same period.
These input cost movements matter because construction chemicals sit at the intersection of petrochemical feedstocks, specialty intermediates, and performance additives. Margin structures are sensitive to feedstock volatility, and procurement agility is increasingly a competitive differentiator. The report examines how leading players are responding through formulation optimization, supplier diversification, inventory strategies, and selective pass-through mechanisms, without exposing the proprietary margin models and cost-ecosystem assessments contained in the full analysis.
On the regulatory front, the landscape is tightening in ways that directly affect product development, testing, and market access. The new Construction Products Regulation in the European Union has entered into force, imposing stricter compliance requirements for construction chemical products. This shift raises the bar for documentation, performance verification, and lifecycle transparency. For multinational suppliers, the EU framework often becomes a de facto benchmark that influences product design and regulatory strategies in other regions as well.
Layering onto compliance is the accelerating emphasis on sustainability. Manufacturers are expanding eco-friendly waterproofing solutions and low-impact formulations to align with green building certifications, public procurement requirements, and customer expectations around embodied carbon and environmental footprint. The industry is moving beyond marketing claims toward measurable performance attributes, which means that R&D roadmaps, patent positioning, and product certification pipelines are becoming strategic assets in their own right.
The report integrates these dynamics into a cohesive market forces framework, helping readers distinguish between transient price shocks and structural cost shifts, and between regulatory compliance burdens and competitive opportunities created by early movers in sustainable product portfolios.
Competitive Architecture: Consolidation, Capability Build-Out, and Regional Re-positioning
The construction chemicals sector is characterized by a concentrated tier of global specialists operating alongside strong regional players and niche technology providers. The report profiles the core companies that are shaping competitive outcomes, including Sika AG, BASF SE through its Master Builders Solutions brand, MAPEI S.p.A., Dow Inc., Saint-Gobain, Arkema S.A., RPM International Inc., GCP Applied Technologies, Fosroc International, Pidilite Industries Limited, Wacker Chemie AG, Nouryon Holding B.V., and Chryso Group.
Rather than treating these firms as static corporate listings, the analysis maps their strategic positioning across concrete admixtures, waterproofing and roofing systems, flooring chemicals, sealants and adhesives, and repair and restoration solutions. The focus is on where each organization is building capability, where it is exposed to input cost risk, and how it is leveraging distribution networks, technical service teams, and application expertise to defend or expand share.
Recent corporate activity underscores a clear consolidation and capability-acquisition rhythm. In 2025, Saint-Gobain acquired the business assets of Interstar Materials, Inc., strengthening its Construction Chemicals activities in the United States and Canada. That move was followed by the completion of Saint-Gobain's acquisition of Fosroc, a leading player in construction chemicals across Asia and emerging markets, consolidating a broader international footprint and expanding access to high-growth regions. In parallel, Master Builders Solutions expanded its U.S. manufacturing footprint with two new admixture sites, signaling a commitment to capacity and proximity to key customer segments. Master Builders Solutions also inaugurated a new state-of-the-art manufacturing facility in Taloja, Navi Mumbai, India, reinforcing its presence in a market where infrastructure demand and urbanization continue to drive volume growth.
Trade presence and solution integration are equally indicative of strategic intent. Saint-Gobain showcased its unified construction chemicals solutions at World of Concrete 2026, highlighting the industry's broader move toward bundled performance offerings rather than isolated product sales. These developments matter because they reveal how incumbents are preparing for the next cycle: through capacity investment in priority markets, acquisition of specialized portfolios, and stronger integration across admixture, waterproofing, and repair ecosystems.
The report translates these moves into a competitive intensity assessment, including concentration patterns that illustrate how value is distributed across the top players. The top three firms collectively account for 52 percent of market revenue, while the top five reach 61 percent. This concentration profile signals that scale, technical portfolio breadth, and global service infrastructure remain powerful advantages, but it also leaves meaningful room for specialized challengers, regional leaders, and innovation-led entrants in adjacent segments. The full analysis provides a more detailed mapping of share dynamics and strategic group behavior, while preserving the granular splits for the complete report.
Product and Application Architecture: Where Value Is Created and Captured
Construction chemicals are no longer a supporting category. They are increasingly central to specification decisions because they influence durability, speed of construction, lifecycle cost, and overall building performance. The product landscape analyzed in the report spans concrete admixtures, waterproofing and roofing systems, flooring chemicals, sealants and adhesives, and a set of specialized repair and restoration solutions. Each category carries distinct demand drivers, formulation complexity, and margin characteristics, and each responds differently to regional construction practices and project types.
Concrete admixtures remain a cornerstone of the sector because they directly affect workability, strength development, durability, and construction efficiency. As projects demand faster cycle times, more resilient structures, and lower water-cement ratios in certain applications, admixture technology continues to evolve. Waterproofing and roofing solutions are gaining strategic importance as asset owners prioritize moisture management, energy efficiency, and long-term protection against environmental exposure. Flooring chemicals serve both aesthetic and functional requirements in commercial, industrial, and residential settings, while sealants and adhesives underpin envelope integrity, joint performance, and assembly reliability across multiple construction systems. Repair and restoration chemicals address the growing need to extend the service life of existing assets, a theme that becomes more prominent as infrastructure ages and renovation activity increases.
On the application side, demand is distributed across residential, non-residential, infrastructure, and repair segments. The balance among these segments varies by region, economic cycle, and public investment pipeline. Residential construction tends to be more cyclical and sensitive to housing market conditions, while non-residential projects reflect commercial development, institutional spending, and workplace transformation trends. Infrastructure demand is shaped by public capital programs, transit expansion, utilities modernization, and resilience-focused rebuilds. Repair and maintenance applications represent a smaller but strategically important pool, often linked to lifecycle management and the macroeconomic value of asset preservation.
The report structures these product and application dimensions around their strategic implications: where formulation leadership creates pricing power, where service and technical support influence specification, and where regional construction norms shape adoption curves. This framing allows readers to identify the segments most aligned with their capabilities before accessing the detailed breakdowns that support precise segment planning.
What the Report Delivers: Commercial Intelligence for 2026 Decision-Making
This market research is built for execution, not just observation. It is intended to support strategic planning, investment prioritization, competitive positioning, and market-entry evaluation in a sector where technical credibility and regional execution often determine outcomes more than broad market narratives.
The report includes the following operational content:
- Historical market sizing from 2020 to 2025, establishing a verified baseline for growth analysis and scenario calibration
- Forecast projections from 2026 to 2032, anchored to the 6.5 percent CAGR trajectory and extending to the projected 2032 valuation threshold
- Segment-level evaluation across product types and application categories, with guidance on where demand is structurally strengthening and where competitive intensity is rising
- Regional demand context that distinguishes between mature, stable markets and faster-growing regions without prematurely disclosing the full regional splits
- Competitive profiling of leading global and regional players, including capabilities, strategic moves, and positioning across core product families
- Recent corporate developments such as capacity expansions, acquisitions, facility inaugurations, and trade-show integrations that signal forward strategy
- Input cost and regulatory dynamics, including MDI pricing movements, silane and styrene cost pressures, and the impact of the new EU Construction Products Regulation
- Sustainability and compliance themes that affect product development, certification, and customer specification behavior
- Strategic implications for manufacturers, distributors, specifiers, and investors seeking to align portfolio choices with market reality
By combining macro growth context with company-level activity and sector-specific cost and regulatory signals, the report creates a decision-ready environment. Readers can test assumptions about demand durability, assess exposure to feedstock volatility, anticipate compliance-driven product changes, and evaluate where consolidation or capability investment is likely to reshape competitive access.
How to Use This Intelligence in 2026
For senior leadership teams, the immediate value of this research lies in its ability to convert a complex market into an actionable strategic map. The 2026 decision environment is shaped by three overlapping questions: where growth is most durable, where cost and compliance pressures will reshape economics, and where competitive positioning will be won through technology, service, or scale.
The report helps answer these questions by separating long-term structural demand from short-term project cyclicality, by clarifying which product families are most exposed to input cost volatility, and by highlighting the corporate moves that indicate where incumbents are placing their bets. It also provides a basis for scenario planning, whether the objective is to evaluate new geographic entry, prioritize R&D investment, refine channel strategy, or assess acquisition targets and partnership opportunities.
Because the construction chemicals market rewards specificity, the report intentionally preserves detailed regional and application-level data for the full edition. This ensures that decision-makers can first align on direction and strategic logic, then access the precise figures needed for country-level planning, segment targeting, and commercial modeling.
Strategic Conclusion: Positioning for the 2026-2032 Cycle
The construction chemicals market is entering a phase in which growth, regulation, sustainability, and consolidation will interact more intensely than in previous cycles. Historical momentum from 2020 to 2025 has set a solid foundation, and the forecast trajectory through 2032 points to continued expansion at a meaningful pace. Yet the operational reality for companies is more nuanced: input cost swings, evolving compliance requirements, regional demand differences, and concentrated competition all demand a disciplined strategic Response.
This report is designed to give executives that discipline. It combines validated market sizing, forward-looking growth analysis, competitive profiling, and recent industry developments into a single integrated view. It also respects the complexity of the sector by keeping the most granular splits and proprietary breakdowns within the full research package, where they can be used for detailed planning without diluting the strategic narrative.
For organizations seeking to act with confidence in 2026, the next step is to translate this market-level perspective into segment-specific strategy. The complete report provides the deeper data architecture required to do that, enabling more precise prioritization of regions, product families, application segments, and competitive responses as the market moves through the rest of the decade.
For detailed analysis of this topic, please visit the official page: Construction Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


