



PW Consulting: Desktop IP Phone Market Hits $385M in 2025, Projected 4.25% CAGR to 2032

Desktop IP Phone Market 2026: A Strategic Roadmap for Enterprise Communications Buyers
The enterprise communications landscape is undergoing a quiet but profound recalibration. As organizations navigate hybrid work mandates, cloud migration backlogs, and tightening security postures, the humble desktop IP phone has reemerged not as a legacy relic but as a strategically placed endpoint that bridges unified communications, physical workspace design, and operational resilience. For executives, procurement leaders, and IT architects, the decisions made in 2026 around desktop IP telephony will echo across operational budgets, compliance postures, and employee experience metrics for years to come. Our newly published Desktop IP Phone Market research study is designed precisely for that moment of decision-making. Rather than offering a superficial snapshot, the report delivers a structured, forward-looking intelligence framework that helps leadership teams separate transient vendor narratives from structural market shifts.
Europium Acetate Market
The strategic value of this study lies in its ability to translate complex market trajectories into actionable procurement, deployment, and partnership choices. Base-year data anchored in 2025 reflects a market that has already absorbed years of infrastructure modernization, while the forecast window stretching from 2026 to 2032 captures the next wave of adoption curves, technology refinements, and competitive repositioning. Total market revenue, measured in millions of USD, moved from approximately 301.48 in 2020 to 385.02 in 2025, signaling a sustained climb that outpaces many adjacent endpoint categories. The projected trajectory through 2032 points toward continued expansion, with the 2026 forecast reading 409.53 and the 2032 horizon reaching 517.92. These figures are not merely arithmetic; they represent cumulative capital allocation, refresh-cycle timing, and competitive intensity across regions and verticals.
Worldwide Screw and Barrel Market
Crucially, the study captures a forecast period CAGR of 4.25 percent, a rate that reflects deliberate, enterprise-led growth rather than speculative hype. That percentage matters to decision-makers because it frames expectations for budget planning, inventory forecasting, and vendor negotiation leverage. A mid-single-digit growth environment rewards disciplined total cost of ownership modeling and penalizes reactive purchasing. The historical runway from 2020 through 2025 demonstrates how the market absorbed pandemic-era demand shocks, supply constraints, and accelerated digital transformation, while the forward window highlights where growth compounds through product innovation, integration depth, and regional maturation rather than through one-off order spikes.
Hoof Care Spray Market
Why 2026 Is a Pivotal Year for Desktop IP Phone Strategy
The 2026 decision environment is shaped by a convergence of forces that make endpoint selection more consequential than in prior refresh cycles. On the regulatory front, compliance and procurement scrutiny are intensifying. Recent developments have placed new constraints on the authorization and sale of certain equipment categories, and expanded covered-list rules effective in March 2026 have added complexity to sourcing decisions for IT teams that must now weigh supply continuity against geopolitical and regulatory exposure. Complementing these shifts, broader telecommunications equipment restrictions—including the placement of select vendors' devices on covered lists—have prompted enterprises to reassess vendor consolidation strategies and to prioritize interoperability, firmware lifecycle commitments, and transparent sourcing models.
Supply chain realities further sharpen the focus on endpoint strategy. Component shortages and disruptions affecting specialized electronic parts continue to extend lead times and elevate costs, which means that procurement timelines, inventory buffers, and vendor delivery reliability are now first-order planning variables rather than secondary considerations. For enterprises evaluating desktop IP phones in 2026, these dynamics elevate the importance of product roadmaps that emphasize longevity, modular firmware support, and ecosystem compatibility. The organizations that will navigate this period most effectively are those treating desktop IP phones as integrated components of a broader communications architecture—one where voice, video, presence, security, and network policy converge.
Against this backdrop, the desktop IP phone is no longer a commoditized accessory. It is an endpoint that must demonstrate compatibility with unified communications platforms, support enterprise-grade security expectations, and deliver a user experience that justifies physical deployment even in environments where soft clients and mobile devices are prevalent. The market research study examines these pressures through the lens of real procurement and deployment scenarios, ensuring that the analysis remains grounded in operational reality rather than abstract technology trends.
What the Research Delivers: An Operational Intelligence Framework
The Desktop IP Phone Market study is structured to support multi-stakeholder decision-making. It moves beyond top-line sizing to provide the analytical scaffolding necessary for segmentation, competitive benchmarking, and scenario planning. The report covers a detailed segmentation architecture that disentangles how market value is distributed across type, application, and geography without reducing the analysis to static snapshots. By examining the Video Desktop IP Phone category alongside Common Desktop IP Phone and other product variants, the study illuminates how form factor, display capability, and feature packaging influence buying behavior across different organizational contexts. Rather than treating all desktop endpoints as interchangeable, the segmentation analysis maps functional differentiation to procurement intent, helping teams align product selection with use-case requirements such as executive conferencing, frontline office deployment, or specialized departmental workflows.
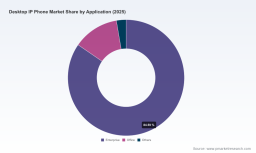
The application-side segmentation further clarifies where demand is concentrated and why. Enterprise deployments continue to anchor the market's core, reflecting the centrality of desk-based voice and video endpoints in structured organizational environments. Office-centric demand and other application segments add nuance to rollout planning, particularly for organizations managing mixed environments that span corporate headquarters, satellite locations, and shared operational spaces. By situating these application patterns within the broader market trajectory, the report enables planners to prioritize deployment sequencing, lifecycle refresh timing, and support-model design with greater precision.
Geographic analysis is presented with the same analytical discipline. The report examines regional market structures across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing context on how regional maturity, regulatory environments, procurement norms, and deployment densities shape demand. Rather than isolating regions as disconnected markets, the study frames them as interconnected nodes within global enterprise strategies, where vendor presence, channel depth, and localization requirements influence both purchasing decisions and total cost of ownership. This regional framing is especially valuable for multinational organizations coordinating standardized endpoint policies while accommodating local compliance, language, and infrastructure realities.
Beyond segmentation, the research incorporates a rigorous competitive landscape assessment. It profiles the organizations that define product direction, set interoperability expectations, and shape procurement negotiations across the market. Cisco Systems maintains a prominent position through its 8800 Series and 6800/7800 series desk phones, which support full-featured VoIP with HD voice, video, and MPP firmware—an ecosystem-aligned approach that resonates with enterprises already invested in broader Cisco communications and networking architectures. Yealink, operating from Suzhou, Jiangsu, has built a strong desktop presence through its T-Series and W-Series desktop IP phones, which integrate Wi-Fi, Bluetooth, and support for up to 16 lines, positioning the brand as a flexible option for enterprise VoIP systems that demand mobility features and multi-line handling. Poly, now part of HP Inc., offers the VVX and Edge Series desk phones with color displays, support for up to 32 lines, and NoiseBlockAI technology, emphasizing audio clarity and high-density line management in professional environments.
The competitive field extends well beyond these headline names. Mitel Networks contributes the 6900 Series desktop IP phones, which combine Wi-Fi and Bluetooth support with PCLink for PC collaboration, appealing to organizations that value tighter integration between endpoints and desktop productivity workflows. Grandstream Networks, based in Belmont, Massachusetts, advances the GRP-Series of wired and Wi-Fi desktop IP phones designed around open SIP standards and enterprise integration, a posture that attracts deployments seeking interoperability and flexible system design. Fanvil focuses on professional IP desktop phones with rich functionality and high-quality builds for enterprise use, reinforcing the value proposition of durability and feature depth in demanding office environments. snom's UC Edition desktop IP phones, with Microsoft Lync and Teams qualification, address organizations that prioritize platform certification and unified communications compatibility as procurement prerequisites. Gigaset rounds out the competitive picture with a professional IP desktop phone portfolio developed for European markets, reflecting the importance of regional product strategy and localized go-to-market execution.
This competitive analysis is not a static company directory. It is constructed to reveal how product portfolios, firmware strategies, platform certifications, and regional focus intersect with procurement priorities. The study also incorporates recent market movements that illustrate how vendors are actively reshaping their positions. Gigaset expanded its professional category with a new IP desktop phone portfolio of three models and launched availability across all European markets in 2025, a sequence that signals deliberate regional emphasis and portfolio refinement. In parallel, snom's 370 UC Edition Desktop IP Phone achieved Microsoft Lync qualification in 2025, a milestone that underscores the persistent importance of platform certification in enterprise buying criteria. These developments are interpreted within the report as indicators of competitive momentum, product-directional shifts, and the evolving expectations placed on desktop IP endpoints.
Market Concentration and the Strategic Implications of an Oligopolistic Structure
One of the study's most decision-relevant contributions is its analysis of market concentration. The market exhibits a CR3 of 63.1 percent and a CR5 of 73.4 percent, indicating that a relatively small group of leading vendors commands a substantial share of revenue. For enterprise buyers, this concentration carries both benefits and risks. On one side, it suggests mature product portfolios, established interoperability ecosystems, and predictable support frameworks from the largest players. On the other side, it raises questions about pricing leverage, vendor lock-in, and the resilience of supply and firmware roadmaps if competitive intensity shifts.
The report contextualizes concentration not as a reason to default to incumbents, but as a parameter for disciplined evaluation. Enterprises are encouraged to weigh ecosystem alignment against openness, platform certification against long-term flexibility, and brand presence against total cost of ownership across multiple refresh cycles. In a concentrated market, negotiation strategy, lifecycle planning, and integration requirements become the true differentiators of procurement success. The research provides the comparative structure needed to evaluate those trade-offs systematically rather than reactively.
Translating Market Data Into Procurement and Deployment Decisions
The practical value of the study lies in its ability to connect macro trajectory with operational execution. When decision-makers understand how the market has grown from 2020 through 2025 and how the forecast extends toward 2032, they can better judge whether current procurement timing aligns with broader adoption momentum or risks buying into a slowing segment. When they examine how video-centric desktop IP offerings compare with common desktop variants, they can align hardware selection with actual usage patterns instead of defaulting to uniform endpoint standardization. When they assess application-side demand structures, they can sequence deployments to prioritize high-impact environments while managing budget phasing more effectively.
The study also supports vendor evaluation beyond feature lists. By mapping product characteristics to enterprise requirements such as HD voice quality, video readiness, multi-line capacity, wireless integration, noise suppression, platform certification, and open SIP compatibility, the report helps procurement teams build scoring frameworks that reflect operational priorities. This is particularly important in 2026, when regulatory and supply chain pressures make vendor selection a multi-dimensional exercise. A phone that satisfies a feature checklist may still underdeliver if firmware support timelines, regional availability, or certification status do not align with enterprise deployment schedules. The research's competitive and segmentation analyses are designed to expose those dependencies before purchase commitments are made.
How to Use This Study Within Your 2026 Planning Cycle
The Desktop IP Phone Market research is built to integrate with existing planning processes rather than interrupt them. It can inform budget forecasting by anchoring expectations in observed historical progression and forecast-period momentum. It can support vendor shortlisting by providing a structured basis for comparing portfolio breadth, platform alignment, and regional execution. It can guide rollout planning by showing how application and regional patterns interact with deployment density and support-model design. It can also strengthen negotiation positions by situating procurement decisions within a market where concentration, product differentiation, and regulatory dynamics all influence value creation.
For organizations managingmixed endpoint environments, the report's segmentation detail helps clarify where standardization adds value and where context-specific selection is warranted. For multinational teams, the regional framing supports coordination between global policy and local execution. For IT and procurement leaders managing risk, the regulatory and supply chain context embedded in the analysis reinforces the importance of sourcing discipline and lifecycle planning. In each case, the study is intended to reduce uncertainty without oversimplifying the decision space.
A Clear View of Where the Market Is Heading
The Desktop IP Phone Market will continue to be shaped by the interplay of enterprise adoption discipline, product differentiation, platform integration, and external pressures from regulation and supply chain conditions. The upward revenue trajectory reflected in the 2026 forecast and extending into 2032 indicates that demand is not collapsing into mobility-only paradigms; instead, it is being redefined around endpoints that deliver reliability, integration, and user experience in environments where voice and video remain mission-critical. At the same time, the mid-single-digit CAGR reminds planners that growth is methodical, which means timing, selection, and negotiation strategy matter as much as the technology itself.
This research study is designed to give decision-makers a credible, structured view of that reality. It offers the historical context to understand where the market has been, the segmentation depth to understand how value is distributed, the competitive analysis to understand who is shaping the landscape, and the forward-looking framework to anticipate where procurement conditions are heading. By combining these elements into a single intelligence asset, the report helps enterprises move from reactive endpoint purchasing to strategic communications infrastructure planning.
The full study contains the detailed data sets, segmentation splits, competitive profiles, and recent-market developments that support rigorous internal review and external negotiation. To access the complete analysis and the underlying intelligence that informs these strategic observations, visit the source page for the Desktop IP Phone Market research. There, you will find the full segmentation framework, company assessments, and market-trajectory detail needed to turn 2026 uncertainty into a defensible, data-informed action plan.
For detailed analysis of this topic, please visit the official page: Desktop IP Phone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


