



PW Consulting: PC System Utilities Market Hits $17.125 Billion in 2025, Expands at 4.11% CAGR Through 2032

Navigating the PC System Utilities Software Market: Strategic Imperatives for 2026 and Beyond
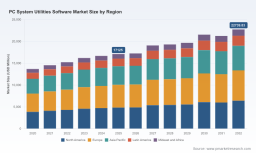
The PC System Utilities Software Market has entered a phase of structured evolution. Over the historical period from 2020 to 2025, the sector demonstrated consistent upward momentum, with global revenue climbing from approximately 13,682 million USD to around 17,125 million USD. As organizations plan their technology roadmaps for 2026, the strategic value of this market lies not merely in incremental growth, but in the convergence of operational efficiency demands, heightened data-security expectations, and an increasingly fragmented competitive landscape. This research provides executive decision-makers with a rigorous, forward-looking framework to navigate market entry, portfolio expansion, and partnership strategies through the 2032 horizon.
Worldwide Drawer Air Fryer Market
Market Architecture and the Trajectory to 2032
Understanding the macroeconomic footprint of the market is the first step toward informed capital allocation. The baseline year of 2025 established a clear inflection, and the forecast window from 2026 to 2032 reveals a compound annual growth rate of 4.11 percent. While the headline figure signals stability, the underlying trajectory exposes a more nuanced reality: growth is not linear, and it is punctuated by structural shifts in how users and organizations interact with system maintenance tools. By 2032, the market is projected to reach approximately 22,739 million USD, representing a meaningful expansion from the 2025 baseline. This progression is shaped by several interlocking forces. First, the maturation of operating-system ecosystems has increased the baseline demand for third-party optimization and maintenance utilities, even as native OS capabilities have improved. Second, the proliferation of digital workflows across both individual and commercial environments has elevated the cost of downtime, driving users toward tools that promise faster system responsiveness and cleaner resource allocation. Third, infrastructure modernization has made it possible for software providers to scale update delivery, telemetry, and secure data-handling pipelines more efficiently, though not without introducing new cost dimensions that must be managed carefully.
CTC and CTB Batteries for EV Market
Strategic readers will note that the forecast period is not a straight extrapolation. The growth path reflects recalibrations tied to product innovation cycles, competitive repositioning, and macroeconomic conditions that influence consumer and enterprise spending on maintenance software. A measured CAGR in this environment does not imply stagnation; it indicates a market that rewards disciplined execution, differentiated feature sets, and clear value propositions. Organizations that approach the market with a clear sense of where growth concentrates, what constitutes defensible differentiation, and how regulatory expectations are reshaping product design will be better positioned to capture share without overextending resources.
Refrigerated Container Adhesive Market
The Strategic Value of This Research for 2026 Decision-Making
Market intelligence becomes actionable only when it connects data to decision. This report is designed to do exactly that: it translates a broad market trajectory into operational guidance for executives, product leaders, and investment teams evaluating the PC system utilities space in 2026. The analysis is structured around the questions that matter most in this stage of the market lifecycle. Where is demand most resilient? Which product categories are gaining or losing momentum relative to user expectations? How do competitors structure their market presence, and where do gaps remain for new entrants or incumbents seeking to pivot? What external pressures—regulatory, infrastructural, and labor-related—are reshaping cost structures and speed-to-market? The answers are not superficial. They are embedded in a research architecture that ties historical performance to forward-looking scenarios, allowing decision-makers to test assumptions rather than rely on static narratives.
For companies planning product roadmaps, the research provides a lens on where utility features intersect with user behavior. For investors and strategic partners, it clarifies the boundaries of market concentration and the practical implications of operating in a space where a small group of players commands a substantial portion of total revenue. For organizations evaluating expansion into adjacent maintenance, optimization, or data-protection segments, the report frames the operational realities that define margin potential and execution risk. The report is not intended as a retrospective summary. It is a decision-support instrument built to help leadership teams convert market signals into prioritized actions, whether those actions involve feature prioritization, channel strategy, pricing architecture, or geographic sequencing.
Inside the Report: Frameworks, Dimensions, and Actionable Intelligence
The research is organized to support both high-level strategy and granular execution. It opens with a comprehensive market sizing exercise that anchors the narrative in verified historical data and extends into forecast modeling for the 2026 to 2032 window. From there, the analysis decomposes the market along multiple dimensions so that leadership can evaluate where value is created and how it flows through the ecosystem. Rather than presenting a single aggregated number and stopping, the report examines how different product categories, user segments, and regional dynamics interact to produce the overall trajectory. This layered approach matters because aggregate growth can obscure divergent sub-trends, and executives need to see beneath the surface to allocate resources intelligently.
A core feature of the research is its focus on product-category dynamics. System optimization remains a central pillar of the market, reflecting sustained demand for tools that improve responsiveness, clear unnecessary files, and streamline routine maintenance. Disk cleanup and data recovery also represent significant components of the landscape, while file management and other utility functions occupy more specialized but still relevant positions. The report evaluates how these categories differ in terms of user adoption patterns, feature expectations, and competitive intensity. It also addresses application-level segmentation, distinguishing between individual users, small and medium enterprises, and large enterprises. Each of these user groups presents distinct purchasing drivers, sensitivity to pricing, and requirements for integration and support. Individual users often prioritize ease of use and immediate perceived performance gains, while smaller enterprises look for cost-effective bundles and manageable deployment. Large enterprises, by contrast, tend to emphasize reliability, compliance alignment, and centralized management considerations. The report maps these differences without reducing them to oversimplified generalizations, enabling readers to identify which segments align with their strategic objectives.
Geographic coverage is equally deliberate. The market is analyzed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with attention to how regional conditions influence adoption, pricing tolerance, and competitive presence. Each region carries its own mix of user behavior, infrastructure maturity, and regulatory environment, and the report uses these distinctions to inform market-access strategies. Rather than treating geography as a static backdrop, the research examines how regional demand patterns evolve in response to product updates, ecosystem changes, and broader technology adoption trends. Executives can use this framing to evaluate where to prioritize go-to-market efforts, where localization matters most, and where the balance between opportunity and operational complexity tilts one way or the other.
Beyond segmentation, the report incorporates operational and structural considerations that directly affect competitiveness. It addresses the cost environment that software providers face, including the labor intensity of specialized development and ongoing maintenance work, as well as the infrastructure burden associated with cloud hosting for update servers and secure data storage. These factors are not peripheral; they shape margin envelopes, product-update cadence, and the ability to scale without compromising reliability. The research also discusses the evolving impact of data privacy and compliance expectations on product design and operational practice. As utilities increasingly interact with system files, user data, and scanning routines, the standards for secure handling and regulatory alignment become central to both reputation and market access. ISO 27001 and related data-protection frameworks are treated as practical reference points that influence how providers structure their workflows and customer commitments. The report weaves these elements into the broader market narrative so that decision-makers can evaluate opportunity in the context of the operational realities that determine long-term viability.
Competitive Dynamics and the Shifting Battleground
No market assessment is complete without a rigorous competitive read. The PC system utilities space is characterized by a concentration of players that have built recognizable brands around system cleaning, optimization, and maintenance. The analysis profiles the firms that define much of the current competitive tension, including iolo Technologies with System Mechanic, Glarysoft Ltd with Glary Utilities, IObit with Advanced SystemCare, Ashampoo GmbH with WinOptimizer Pro, WiseCleaner Technology Co., Ltd. with Wise Disk Cleaner and Wise Care 365, Piriform Software Ltd with CCleaner, and Avanquest Software with its PC tune-up and optimization offerings. These companies do not occupy identical positions in the market. Their product philosophies, feature scopes, and positioning strategies differ in ways that matter for both incumbents and new entrants. Some emphasize comprehensive optimization suites, while others lean into cleaner-focused experiences or integrate security-minded functions alongside maintenance tasks. The report examines these distinctions as strategic signals, showing how each player’s approach shapes customer perception, feature competition, and the boundaries of market share.
The Microsoft trajectory adds an important layer to the competitive picture. Recent update activity underscores how a platform-level player can influence expectations across the broader utilities ecosystem. In late 2025, a new version of Microsoft PC Manager was released with enhancements to storage cleanup and PC performance monitoring. A subsequent update in mid-2026 continued the rollout with improvements aimed at broader global deployment. This cadence matters because it signals renewed attention to native or platform-adjacent maintenance tools, which can shift user baselines and raise the bar for third-party offerings. The presence of an established platform player in this space does not automatically compress the market for independent utilities, but it does change the competitive context. Third-party providers must articulate clear and credible reasons for users to adopt their solutions beyond what is already available through default system tools. The research addresses this dynamic directly, focusing on how differentiation, trust, and functional depth become more important when baseline expectations rise.
Market concentration further sharpens the competitive read. The sector is not evenly distributed across all participants. A meaningful share of total revenue is accounted for by a small group of leading firms, and the cumulative footprint of the top players remains substantial. This concentration has strategic implications. It suggests that established positions are not easily displaced, that brand trust and installed-base momentum carry weight, and that differentiation must be both credible and sustained. At the same time, concentration does not imply stagnation. It often signals where innovation pressure is highest, because leaders must continuously defend their positions while challengers search for underserved needs or alternative bundling strategies. The report helps executives interpret these concentration patterns not as barriers alone, but as indicators of where value capture is occurring and where competitive openings may still exist for focused execution.
Structural Forces Reshaping the Market
Beyond competition and segmentation, the market is being shaped by operational realities that influence how utilities are built, delivered, and trusted. Data privacy and compliance requirements have become embedded in product design considerations rather than treated as afterthoughts. Utilities that perform system scans, handle user files, or interact with sensitive system areas must navigate expectations around secure handling and transparent data practices. This dynamic raises the stakes for product architecture and customer communication. Providers that treat compliance as integral to their offering can turn it into a trust advantage, while those that underestimate it may face friction in adoption or reputational exposure.
The labor dimension is equally important. Specialized software development and maintenance represent a core operational expense, and the talent required to build and sustain reliable optimization tools is not commoditized. This cost pressure influences release cycles, feature ambition, and the pace at which providers can respond to user feedback. In a market where perceived performance improvements and stability are central purchase drivers, development discipline matters as much as marketing reach. Infrastructure cost has a parallel effect. Cloud hosting for update servers and secure storage for user data adds another layer to the expense profile, particularly as providers scale and seek to maintain consistent delivery across regions. The report integrates these cost drivers into the analysis so that growth estimates are evaluated alongside the operational commitments required to support them. This makes the forecast more than a projection of revenue movement; it becomes a practical assessment of what it takes to sustain position in a competitive environment.
How to Use This Research in 2026 Planning
The most valuable research is the kind that changes how a team thinks before it changes what the team does. In 2026, leadership teams can use this report to test several strategic hypotheses at once. It can support decisions about whether to enter the market, deepen an existing presence, or reposition an existing offering against evolving user expectations. It can help product leaders identify which categories and user segments offer the best alignment with current capabilities and where the opportunity cost of broadening too quickly may be highest. It can guide commercial teams in evaluating pricing, bundling, and channel strategies against a competitive backdrop in which trust, clarity, and reliability are increasingly important purchase drivers. It can also support investor and partnership conversations by providing a structured view of market size, trajectory, concentration, and the operational pressures that influence margin and execution speed.
Crucially, the report is built to be referenced, not just read. Its segmentation detail, competitive profiles, and structural analysis are designed to feed directly into planning cycles, scenario testing, and investment prioritization. Executives do not need every underlying data point presented as a static table to benefit from the analysis. What matters is that the research preserves enough depth to support real decisions while remaining clear about where additional intelligence is needed. That is why this overview is deliberately framed as an entry point rather than a full disclosure. The complete dataset, scenario pathways, and granular segment readings are available in the full report, where teams can examine the numbers that matter most to their specific strategies.
What the Full Report Unlocks
This introduction provides the strategic context, the competitive logic, and the structural forces that define the PC System Utilities Software Market in 2026 and beyond. It establishes that the market is growing with discipline, that concentration shapes the competitive battleground, and that operational realities around compliance, development labor, and infrastructure are central to sustainable positioning. It also makes clear that the deeper the decision stakes, the more valuable the underlying detail becomes. The full research release goes further by offering target-segment readings, detailed category-level assessments, regional deployment considerations, and the specific competitive intelligence needed to move from directional confidence to precise execution. For organizations that intend to act on this market with seriousness, the complete report is where the analysis converts into operational advantage.
The PC system utilities market is no longer a space where generic features or broad promises are sufficient. It rewards clarity of purpose, credible differentiation, and disciplined execution. For decision-makers in 2026, the strategic task is to understand not only how large the market is or how fast it is likely to grow, but where value concentrates, how competitors defend their positions, and what operational commitments are required to compete effectively. This research is designed to help leaders answer those questions with confidence, and to lay the groundwork for decisions that are grounded in evidence rather than assumption.
For detailed analysis of this topic, please visit the official page: PC System Utilities Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


