



PW Consulting: Automatic Lubrication Systems Market to Hit $1.34B by 2032, 4.95% CAGR Forecast

Strategic Intelligence for the Automatic Lubrication Systems Market: Navigating Growth Trajectories Through 2032
In an industrial landscape where uptime directly dictates profitability, the automatic lubrication systems sector has transitioned from a supporting operational function to a strategic investment priority. PW Consulting’s comprehensive market research for this domain delivers a granular, data-backed assessment of the sector’s performance, competitive architecture, and forward-looking drivers. This analytical introduction outlines the structural forces shaping the market, the competitive dynamics that define investment and procurement decisions, and the specific analytical dimensions our report unpacks. The objective is not to replicate the full intelligence deliverable, but to demonstrate how decision makers can extract executable advantage from the complete dataset as they position for the 2026–2032 horizon.
Modular Temperature Control Systems Market
Establishing the Macro Trajectory: Why the Numbers Matter Strategically
The market has demonstrated consistent, compounding expansion over the past half-decade, reflecting a structural shift rather than a cyclical rebound. From a baseline of approximately 751.62 million USD in 2020, revenue advanced to 952.32 million USD by 2025, underscoring a practical recovery and growth inflection after the volatility of earlier years. The forward trajectory projects the sector to surpass the 1 billion USD threshold in 2026, reaching 1,008.16 million USD, before stepping to 1,132.41 million USD by 2028 and 1,173.72 million USD by 2029. The terminal forecast stands at 1,335.61 million USD in 2032, a magnitude that signals sustained capital allocation, OEM engineering focus, and end-user procurement confidence.
Metal Water Truck Pumps Market
Underlying this progression is a compound annual growth rate of 4.95 percent across the 2026–2032 forecast window. For senior leadership, that rate is not merely a statistical projection; it is a calibration benchmark for capacity planning, supply chain hedging, and R&D prioritization. A sub-5 percent CAGR in a mature industrial hardware category indicates steady, predictable demand rather than speculative hype. It suggests that growth is being driven by operational necessities—reduced unplanned downtime, labor optimization, and regulatory pressures—rather than discretionary capex. Consequently, organizations that treat this category as a steady-state procurement line risk missing the embedded strategic levers: deployment standardization, total cost of ownership reduction, and integration into broader predictive maintenance architectures.
Nano Sponge Market
Another strategic layer emerges from market concentration. The combined share of the top three participants reaches 58.0 percent, while the top five account for 72.5 percent. This tiered concentration reveals a market with recognizable incumbents and defensible technical positioning, yet still open enough to reward focused innovators and regional specialists who can differentiate on reliability, digital connectivity, or application-specific engineering. Understanding where concentration is high and where fragmentation persists directly informs partnership strategies, channel design, and competitive response planning.
Structural Segmentation: Reading the Demand Architecture Without Losing Sight of the Whole
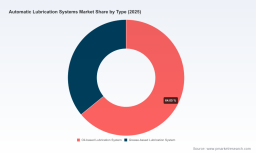
Segmentation analysis in this domain rarely exists for its own sake. It functions as a diagnostic framework for identifying value pools, deployment roadblocks, and technology adoption cycles. The market bifurcates fundamentally between oil-based and grease-based lubrication systems. The oil-based segment holds a clear volume advantage, reflecting its broader compatibility with continuous-flow industrial machinery, centralized distribution architectures, and applications demanding higher thermal stability or longer service intervals. Grease-based systems, while smaller in aggregate value, address distinct operational requirements—sealed bearings, high-load points, and environments where viscosity retention and contamination resistance are paramount. The coexistence of these two technology families means that procurement strategies cannot be generic; they must align with machine OEM specifications, environmental exposure profiles, and maintenance cadence objectives.
Application-side segmentation further illustrates how demand is distributed across industrial verticals. Steel, manufacturing, cement, paper and printing, transportation, and construction each present different lubrication pain points and adoption thresholds. High-speed manufacturing environments prioritize precision dosing and minimal intervention windows, whereas heavy industrial sectors such as steel and cement demand systems engineered for thermal extremes, particulate contamination, and structural vibration. Transportation and construction applications introduce additional complexity: mobile deployment, variable operating cycles, and the need for modular, ruggedized architectures. Rather than viewing these application splits as isolated revenue buckets, strategic planners should read them as proxies for implementation readiness. Verticals with higher automation maturity and tighter maintenance budgets tend to adopt centralized and digitally monitored systems more rapidly, while operations still reliant on manual or semi-automated workflows represent the near-term conversion opportunity.
Regional demand concentration tells a complementary story. Industrial activity, capital expenditure cycles, and supply chain localization all shape where deployments scale fastest. The geography of demand influences not only end-user sourcing patterns but also manufacturer footprint decisions, service network density, and pricing architectures. Companies evaluating expansion, localization, or distributor partnerships need a clear view of regional readiness, not a narrow snapshot of nominal size. That is why the complete report prioritizes regional dynamics in conjunction with industrial base indicators and procurement seasonality, rather than presenting static regional splits in isolation.
Competitive Architecture: Incumbent Strength, Differentiation Vectors, and Recent Moves
The competitive field is anchored by manufacturers with established engineering heritage, global distribution reach, and deep application-specific portfolios. Groeneveld-BEKA, headquartered in Gorinchem, Netherlands, operates as the second-largest manufacturer globally, extending across transportation, construction, mining, agriculture, and industrial applications. Its breadth signals a strategy rooted in cross-sector applicability and fluid management integration. SKF Lincoln, based in Decatur, Illinois, provides a complete portfolio of automatic lubrication systems and components for industrial and mobile equipment, spanning oil- and grease-based centralized architectures. Its positioning within a larger bearing and reliability ecosystem reinforces the market’s trend toward integrated maintenance solutions rather than isolated component sales.
perma, located in Euerdorf, Germany, distinguishes itself as a global leader in single-point and multi-point automatic lubrication systems, increasingly paired with connected digital solutions designed to improve industrial reliability and reduce maintenance burden. This pivot toward connectivity is a defining competitive vector: lubrication delivery is becoming a data-generating node within broader asset management platforms. Bijur Delimon International, headquartered in Morrisville, North Carolina, maintains a global leadership stance in the design and manufacturing of automatic lubrication systems, pumps, and lubrication equipment for industrial machinery, emphasizing precision engineering and broad equipment compatibility. Dropsa, based in Italy, manufactures centralized automatic lubrication systems encompassing single-line, dual-line, progressive, oil, grease, and air/oil configurations, reflecting deep expertise in diversified delivery architectures for industrial production.
Graco, headquartered in Minneapolis, Minnesota, provides automatic lubrication systems for in-plant and mobile applications, complemented by pumps, meters, controllers, and accessories aimed at equipment optimization. A.T.S. Electro-Lube, based in Canada, manufactures self-contained automatic lubrication systems, including single-point, multi-point, and refillable units engineered for demanding industrial environments. Oil-Rite Corporation, located in Manitowoc, Wisconsin, specializes in designing and manufacturing high-quality lubrication systems and components focused on industrial machinery efficiency and longevity. LSP Industries, Inc., headquartered in South Windsor, Connecticut, delivers comprehensive lubrication system solutions tailored to modern industries, combining design, manufacturing, and support capabilities. Together, these firms form an ecosystem where scale, specialization, and service integration determine market positioning.
Recent corporate activity reinforces the strategic themes visible across the sector. In January 2026, A.T.S. Electro-Lube prepared to exhibit at POWERGEN 2026 in San Antonio, Texas, showcasing next-generation automatic lubrication systems for industrial equipment performance and reliability. This trade presence reflects the ongoing importance of face-to-face demonstration, application engineering dialogue, and live reliability proofing in a category where equipment downtime carries tangible financial consequences. In October 2025, perma held a groundbreaking ceremony for a new production and dispatch facility aimed at supporting expanded manufacturing capacity. That move signals confidence in demand sustainability and a willingness to invest in throughput, lead-time performance, and regional fulfillment capability. Around the same period, Lubecore participated in TKD Technical Contact Days in the Netherlands with automated greasing systems for earthmoving and recycling equipment, while Applied Lubrication Technology Inc. exhibited automatic lubricators and lubrication solutions for heavy-duty applications at the Lubricant Expo & The Bearing Show North America in Detroit. These events collectively indicate that innovation showcases, capacity expansion, and application-specific demonstrations are compounding as competitive levers.
Market Dynamics and Structural Forces Shaping Deployment
Regulatory and safety imperatives are increasingly re 아키텍팅 the economics of manual lubrication. Growing regulatory pressure concerning workplace safety and environmental protection is compelling industries to adopt automated lubrication solutions. When compliance burdens rise, organizations look for repeatable, controlled application methods that reduce operator exposure, minimize spill risk, and standardize maintenance procedures. Automated delivery systems answer that need by reducing variability in quantity, frequency, and point coverage. At the same time, stricter regulations related to worker safety and machine performance support adoption while influencing material and labor cost structures. The result is a dual compression: end users seek reliability and safety, while suppliers must manage input cost volatility and labor intensity across design, assembly, and service delivery.
A broader macro trend reinforces this direction. The global trajectory toward automation is accelerating demand for automatic lubrication systems in industrial machinery. As plants and fleets integrate more sensors, controllers, and programmable logic into their operations, lubrication delivery is increasingly viewed as a process that should be synchronized with equipment state rather than treated as a standalone maintenance task. This mindset shift expands the addressable use case beyond traditional heavy equipment into continuous-process environments and high-cycle production lines where precision and repeatability yield measurable efficiency gains.
Cost and geopolitical variables add further complexity. United States tariffs implemented in 2025 are influencing the cost structure for single-line centralized lubrication equipment. Tariff exposure alters sourcing decisions, prompts supply chain reevaluation, and can shift competitive advantage toward manufacturers with localized assembly, diversified component sourcing, or flexible distribution models. For procurement teams and channel partners, this means that quotation framing, inventory positioning, and contract timing are no longer administrative details; they are strategic variables that affect landed cost and service continuity. Organizations that map tariff exposure against regional demand and product architecture can better anticipate pricing shifts and negotiate with a clearer understanding of structural cost drivers.
What the Full Research Deliverable Supplies: Operational Intelligence, Not Just Forecasts
A market research report is only as valuable as its ability to translate macro direction into actionable planning parameters. The complete PW Consulting study is structured to support budget justification, technology roadmapping, competitive benchmarking, and market-entry evaluation. It opens with an executive synthesis that connects historical performance, forecast direction, and the strategic implications for capital allocation and procurement planning. The methodology and scope section clarifies data construction, analytical boundaries, and modeling assumptions so that readers can assess forecast reliability and apply the findings appropriately to their own scenarios.
The core market analysis quantifies revenue progression, forecast inflection points, and concentration dynamics while framing the market in terms of what is driving adoption and what may constrain it. Industry dynamics are mapped across regulatory pressure, automation momentum, cost-structure influences, and tariff-related cost effects, giving planners a multi-variable lens rather than a single-line growth narrative. Segmentation is examined by type and application with attention to technical fit, deployment requirements, and demand timing, allowing readers to identify which product families and verticals align with their capabilities or procurement priorities. Regional dynamics are discussed in the context of industrial activity, supply chain considerations, and competitive density, helping stakeholders evaluate where to prioritize sales effort, service investment, or sourcing adjustments.
Competitive profiling forms a central pillar of the report. Each key participant is assessed for positioning, portfolio coverage, geographic footprint, and strategic direction. Beyond descriptive profiles, the analysis links corporate moves—facility expansion, trade show demonstrations, product emphasis, and capacity investments—to broader market implications. This enables readers to interpret competitor behavior as signals about capacity confidence, segment focus, and technology priorities. Recent developments are incorporated as real-time indicators of where attention and resources are flowing, giving decision makers a forward-looking pulse on the competitive field.
The deliverable is also designed for practical application by multiple internal audiences. Finance and procurement teams can use the revenue framework and concentration patterns to benchmark pricing expectations, evaluate supplier concentration risk, and plan contract timing. Engineering and maintenance leaders can use segmentation and dynamics insights to justify standardization, compare technology families, and align lubrication strategy with reliability programs. Commercial and strategy teams can use the competitive architecture and regional context to assess positioning, identify underserved application pockets, and shape channel or partnership decisions. By presenting these layers in an integrated format, the report supports cross-functional alignment rather than siloed reading.
Guidance for Decision Makers Entering 2026
As organizations set their plans for 2026, the strategic question is not whether automatic lubrication systems matter, but how to allocate attention and capital in a market that is consolidating around reliable incumbents while still rewarding targeted innovation and application-focused execution. Several priorities emerge from the structural evidence. First, treat lubrication delivery as a reliability and compliance investment rather than a commodity line item. Where automated systems reduce variability, limit operator exposure, and extend service intervals, the value case extends beyond the unit price into maintenance cost avoidance and operational continuity.
Second, align technology selection with application reality. Oil-based and grease-based systems serve different operating conditions and maintenance philosophies, while centralized architectures vary in complexity, routing requirements, and controllability. Procurement specifications should be built around machine profiles, environmental exposure, maintenance staffing models, and the organization’s appetite for monitoring and integration. In practice, that means evaluating not only the delivery mechanism but also the surrounding controls, refill logistics, and serviceability.
Third, factor supply-side cost dynamics into sourcing strategy. Tariff exposure, material cost sensitivity, and regional fulfillment capability can materially affect landed cost and lead time. Where possible, buyers should compare total cost of ownership across suppliers with different manufacturing footprints and distributor networks, and suppliers should assess where localized capacity or diversified sourcing can protect margin and service reliability. Fourth, watch competitor capacity and showcase behavior as leading indicators. Facility expansions and trade show demonstrations are not cosmetic; they communicate where manufacturers expect demand to concentrate and which applications they believe represent the highest value opportunities.
Finally, integrate lubrication systems into the broader automation and data strategy wherever feasible. As connected monitoring and digital service tools mature, lubrication points can become part of a more responsive maintenance ecosystem. Organizations that plan for this integration early—by specifying compatible architectures, training maintenance teams, and defining data usage protocols—will be better positioned to convert equipment reliability into measurable operational advantage.
Proceeding with Full-Market Intelligence
The automatic lubrication systems market is expanding along a measured, structurally supported trajectory, with a forecast CAGR of 4.95 percent carrying the sector past 1.3 billion USD by 2032. Concentration patterns, technology bifurcation, application diversity, and cost-dynamic pressures all point to a market where informed positioning matters more than blanket exposure. PW Consulting’s full report provides the detailed segmentation breakdowns, regional evaluation, competitive mapping, and scenario-ready analysis required to move from awareness to execution.
For executives and commercial leaders who need to justify investment timing, evaluate supplier landscapes, or identify the highest-value deployment opportunities, the complete deliverable supplies the granularity and context necessary to make confident decisions. The macro direction is clear; the strategic edge lies in understanding where value concentrates, which competitive signals to watch, and how to align product, sourcing, and service choices with operational reality. Access to the full intelligence package converts the market’s broad trajectory into a usable roadmap for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Automatic Lubrication Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


