



PW Consulting: Plastic Bearings Market to Reach $15.78 Billion by 2032 at 4% CAGR

The Strategic Pivot: Why the Plastic Bearings Market Demands Attention in 2026
Introduction: The Quiet Revolution in Motion Control
In the complex machinery of global industry, few components work as quietly yet as critically as plastic bearings. Once relegated to low-load, low-cost applications, engineered polymer bearings have evolved into high-performance solutions capable of replacing metals in some of the most demanding environments known to manufacturing. From the sterile precision of medical devices to the high-load cycles of automotive automation, the shift toward maintenance-free, corrosion-resistant, and lightweight bearing solutions is no longer a trend—it is a structural transformation of the supply chain.
Worldwide KLT BOX Market
As we navigate the mid-2020s, the market for plastic bearings stands at a pivotal inflection point. The convergence of material science advancements, shifting regulatory landscapes, and the relentless drive for industrial efficiency has created a landscape where legacy assumptions no longer hold true. For strategic decision-makers, this environment demands more than cursory market scanning; it requires a deep, forensic understanding of where value is being created, where margins are under pressure, and which competitors are positioning themselves for the next decade.
Worldwide VCSEL Lidar Chip Market
This article serves as an executive preview of our latest comprehensive study: the Plastic Bearings Market Research Report. Designed for C-suite executives, procurement leaders, and strategic planners, this piece outlines the macro foundations of the industry, highlights the competitive architecture, and underscores the immediate strategic value of the full intelligence contained within our research.
Worldwide Ketoprofen Lysine Salt Market
Macro Foundations: Tracking the Trajectory of Growth
Understanding the scale and velocity of the plastic bearings market is the first step in calibrating strategic response. The data tells a story of consistent, resilient expansion, even amid broader economic volatility. Based on historical analysis from 2020 through 2025, the market has demonstrated a steady compound annual growth trajectory that underscores the durability of demand for polymer-based motion solutions.
The overall market revenue, measured in millions of USD, has grown from approximately 9.8 billion in 2020 to a projected valuation reaching beyond 15.7 billion by the end of the forecast window in 2032. This growth is not merely a reflection of inflation or currency shifts; it represents a genuine expansion in the addressable market as industries replace legacy metal components with advanced polymers. The base year analysis for 2025 sets a robust platform, with revenues stabilizing at a level that supports aggressive R&D and capacity expansion initiatives among key players.
Central to this outlook is the compound annual growth rate (CAGR), which our analysis pegs at approximately 4.0 percent over the forecast period extending from 2026 through 2032. While this growth rate might appear moderate in isolation, it is significant given the maturity of certain segments within the bearing industry. A 4.0 percent CAGR in a specialized component market signals sustained adoption curves, particularly in sectors where plastic bearings are still displacing traditional solutions. This steady pace allows for calculated investment rather than speculative gambling, provided decision-makers have access to the granular trend lines that our full report provides.
However, macro aggregates only tell part of the story. The real strategic insights lie in the subtle shifts within type segmentation, application uptake, and regional performance. Without diving into the specific percentages that could compromise the exclusivity of our data, it is sufficient to note that the market is not monolithic. Certain polymer types are seeing accelerated adoption due to performance breakthroughs, while specific application verticals are driving the bulk of incremental revenue. The divergence between high-growth niches and stable legacy segments creates both opportunity and risk, necessitating a nuanced go-to-market strategy that our research unpacks in detail.
Currents Shaping the Landscape: Raw Materials and Regulation
No market strategy can be formulated in a vacuum. The plastic bearings industry is deeply sensitive to upstream commodity dynamics and downstream regulatory frameworks. Two emerging themes in the first half of 2026 illustrate the complexity that manufacturers and buyers must navigate.
On the supply side, the cost and availability of polymer resins remain critical variables. Recent data from the US Bureau of Labor Statistics indicates that plastic resins and materials saw increases in the index for processed goods as of April 2026. This uptick contributes to broader upward pressure on polymer availability and costs. For producers of plastic bearings, this translates into margin management challenges and potential pricing power negotiations with downstream customers. For buyers, it signals the need for long-term supply agreements or strategic inventory positioning to mitigate cost volatility. Our report dissects how these raw material fluctuations are being absorbed by different tiers of the supply chain and which regions are most exposed.
On the regulatory front, compliance requirements are tightening in key manufacturing hubs. In a notable development, the Indian government notified the Bearing (Quality Control) Order, 2025, mandating BIS certification and compliance for bearings, including plastic types. This regulation, highlighted in industry updates from May 2026, introduces new barriers to entry and compliance costs for companies looking to serve the Indian market. Such regulatory shifts often serve as precursors to similar quality control mandates in other emerging economies. Navigating these requirements requires not just legal diligence but also an understanding of how certification timelines and standards will affect market access and competitive positioning. Our research provides a regulatory mapping that goes beyond headlines, offering actionable insights for market entry and compliance strategy.
Strategic Segmentation: Beyond the Aggregates
While the headline numbers provide the scope of the opportunity, the true strategic leverage comes from understanding the architecture of the market. The plastic bearings sector is defined by distinct segmentation dimensions—by type, by application, and by region—each of which carries its own driver set, competitive intensity, and growth profile.
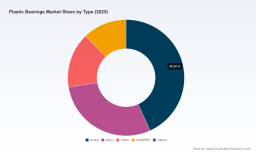
When examining the market by type, the landscape is dominated by a hierarchy of polymer technologies. Acetal and Nylon variants continue to hold substantial share, reflecting their established performance profiles and cost-effectiveness in standard industrial applications. However, the dynamics are shifting. Teflon and UHMWPE-based bearings are carving out specialized roles in environments where chemical resistance, low friction, or extreme wear tolerance are non-negotiable. The interplay between these material types is not static; it is influenced by resin pricing, processing technology maturity, and the specific technical requirements of end-use industries. Strategic planners must understand which material segments are commoditizing and which are moving up the value chain to command premium positioning.
The application segmentation reveals where the demand pressure is originating. Automotive represents a massive anchor for plastic bearing consumption, driven by the need for lightweighting, corrosion resistance, and maintenance-free operation in under-hood and chassis applications. Yet, the automotive sector is not a monolith; it spans passenger vehicles, heavy-duty commercial transport, and the rapidly evolving electric vehicle landscape, each with distinct bearing requirements. Equally important are sectors such as packaging, medical, food processing, and industrial machinery. The medical and food processing verticals, while smaller in aggregate volume compared to automotive, often present higher margin opportunities and stricter regulatory hurdles, creating a different risk-reward calculus for suppliers. Packaging and industrial machinery provide volume stability and broad application breadth. Our report provides a deep dive into how these application verticals are evolving, including sub-segment trends that are not visible in top-line data.
Regionally, the market exhibits distinct maturity curves and growth drivers. North America and Europe remain strongholds with established manufacturing bases and high adoption rates of advanced polymer solutions. Asia Pacific, however, continues to be a focal point for volume growth, driven by industrial expansion and increasing localization of supply chains. Latin America and the Middle East and Africa represent emerging opportunity zones where infrastructure development and industrial modernization are creating new demand pockets. Understanding the relative attractiveness of each region, including trade dynamics, local content requirements, and competitive intensity, is essential for allocating resources effectively.
Competitive Architecture: Navigating a Consolidated Field
The competitive landscape of the plastic bearings market is characterized by a blend of specialized innovators and diversified industrial players. Market concentration metrics indicate that a significant portion of revenue is captured by a core group of leading firms. With a CR3 of approximately 55 percent and a CR5 extending to 68 percent, the top-tier competitors wield substantial influence over pricing norms, technology standards, and supply chain expectations. This concentration suggests that new entrants face high barriers to scale, while existing players must constantly innovate to defend share and margin.
Among the key companies shaping this landscape, Igus, headquartered in Köln, Germany, stands out as a specialist in motion plastics. The company focuses on injection-molded iglidur polymer bearings designed for high-load, maintenance-free industrial applications, particularly in automation and robotics. Their strategy emphasizes material innovation and direct-to-engineer engagement, allowing them to capture value in high-performance niches where reliability is paramount.
GGB, based in Torrington, Connecticut, USA, is another major force, specializing in metal-polymer and thermoplastic composite plain bearings. Their portfolio addresses automotive, industrial, and heavy-duty environments, leveraging a hybrid approach that combines the strength of metals with the benefits of polymers. GGB's positioning highlights the ongoing relevance of composite solutions in applications where pure polymer bearings may face load or thermal limitations.
Trelleborg AB, a producer based in Trelleborg, Sweden, brings a broad polymer and composite expertise to the bearing space, with products serving extreme environments in aerospace, marine, and industrial sectors. Their ability to operate in harsh conditions underscores the expanding envelope of where plastic bearings can be deployed, particularly as industries push for components that withstand corrosive, high-temperature, or high-vibration settings.
In the North American market, players such as BNL and Hartford Technologies demonstrate the diverse strategies within the sector. BNL is an active supplier of advanced plastic bearing solutions, maintaining visibility through trade show participation and industry engagement. Their recent showcase of advanced plastic bearing solutions at The Bearing Show North America in Detroit in March 2026 illustrates the importance of customer engagement and technology demonstration in a market where application-specific fit is critical. Hartford Technologies, on the other hand, focuses on custom manufacturing of plastic bearings and assemblies, serving niches such as pool and spa, recreational equipment, and industrial drop-in replacements. Their model highlights the value of customization and rapid prototyping in serving fragmented application markets where standard catalog parts may not suffice.
The competitive dynamics are not static. As raw material costs fluctuate and regulatory requirements tighten, competitive advantages will shift toward companies that can secure stable resin supply, navigate certification landscapes efficiently, and offer differentiated technical value rather than competing solely on price. Our report includes detailed competitor profiling, evaluating capabilities, market footprints, and strategic moves that are reshaping the hierarchy.
Contents of the Full Study: A Toolkit for Decision-Making
This article has outlined the macro contours and the competitive stakes. But for a strategy to be executable, it must be built on granular intelligence. Our full Plastic Bearings Market Research Report is designed as a practical toolkit for the demands of 2026 and beyond. It goes far beyond the aggregates and themes discussed here, providing a structured, data-rich foundation for planning.
Core Deliverables Include:
- Historical and Forecast Revenue Analysis: Detailed time-series data covering the historical period from 2020 through 2025, with a comprehensive forecast extending through 2032. This includes base year calibration and segment-level projections that allow for scenario modeling.
- Segmentation Deep Dives: Complete breakdowns by bearing type, application vertical, and geographic region. These splits reveal the relative contribution of each segment, growth rates, and shifting share dynamics that are critical for portfolio prioritization.
- Competitive Benchmarking: In-depth profiles of leading companies, including Igus, GGB, Trelleborg AB, BNL, Hartford Technologies, and other key market participants. The analysis covers product portfolios, technological focus, market presence, and recent strategic moves.
- Supply Chain and Cost Dynamics: Examination of raw material influences, including resin pricing trends and availability pressures, with implications for manufacturing economics and pricing strategies.
- Regulatory and Standards Mapping: Tracking of quality control orders, certification mandates, and compliance requirements across major markets, helping companies anticipate barriers and plan market access.
- Strategic Recommendations: Actionable guidance for manufacturers, suppliers, and buyers on positioning, investment, risk mitigation, and opportunity capture in a market defined by both steady growth and structural change.
The report is structured to serve multiple functions within an organization. For product development teams, it provides market pull insights that can guide material selection and feature prioritization. For sales and marketing, it offers segmentation clarity to target high-value applications and geographies. For finance and strategy, it supplies the quantitative backbone for CAPEX planning, M&A screening, and market entry decisions. For procurement, it illuminates supply chain vulnerabilities and pricing trends that affect cost management.
Why 2026 Is the Critical Year for Strategic Clarity
The year 2026 represents more than a midpoint in a forecast period; it is a moment of convergence. The market has absorbed years of incremental growth and technological maturation, reaching a size and complexity where legacy planning tools are insufficient. The 4.0 percent CAGR signals that growth is real and sustained, but it also means that the market is large enough that small percentage shifts translate into significant absolute value movements. Companies that continue to operate with broad-brush assumptions risk misallocating resources, missing high-margin niches, or underestimating competitive threats from specialized players.
Furthermore, the external environment is adding layers of complexity. Raw material cost pressures are testing the resilience of pricing models. Regulatory initiatives, such as the BIS certification mandates in India, are signaling a global trend toward tighter quality control that could reshape market access in emerging economies. Trade show activity and industry engagement, exemplified by recent events like The Bearing Show North America, highlight the importance of staying connected to the application community and tracking technological showcases that signal where innovation is heading.
For leaders, the question is no longer whether plastic bearings are relevant—they are indispensable in an increasing array of applications—but how to position for the next phase of the market's evolution. Do you have visibility into which type segments are gaining momentum? Do you understand the regional risk-reward profiles for expansion? Are you aware of the competitive moves that could alter your share position? These are the questions that our research is built to answer.
Conclusion: Accessing the Full Intelligence
The plastic bearings market is undergoing a period of sustained transformation, driven by material innovation, application expansion, and a competitive landscape that rewards technical differentiation. The macro data confirms the scale and trajectory of the opportunity, but the real value for strategic decision-making lies in the details—the segmentation nuances, the competitive profiles, the supply chain sensitivities, and the regulatory horizon.
This article has provided a strategic preview, highlighting the market's growth path, the forces shaping its dynamics, and the structure of the competitive field. It has intentionally avoided the granular splits and specific figures that form the core of our analytical depth. To access the complete segmentation data, detailed competitor assessments, regulatory mappings, and forecast models that will enable precise decision-making in 2026, we invite you to consult the full Plastic Bearings Market Research Report.
In a market where a 4.0 percent CAGR compounds into significant value over the forecast horizon, and where raw material and regulatory shifts can rapidly alter the economics of supply and demand, information is not just an asset—it is a strategic imperative. Equip your organization with the intelligence needed to navigate the complexities of the plastic bearings market with confidence and precision.
For detailed analysis of this topic, please visit the official page: Plastic Bearings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


