



PW Consulting: Stainless Steel Cookware Market to Hit $12.1B by 2032, 5.6% CAGR

Navigating the Future of Kitchen Durability: Strategic Insights into the Stainless Steel Cookware Market 2026–2032
In the landscape of consumer durables, few categories embody the intersection of tradition, material science, and shifting health consciousness quite like stainless steel cookware. As we move deeper into 2026, industry stakeholders are confronted with a market that is not merely growing but evolving in complexity. The recent market research released by PW Consulting offers a comprehensive lens into this evolution, providing critical intelligence for executives, investors, and supply chain strategists who aim to secure a competitive advantage in the coming decade.
Worldwide 4-hydroxybutyl Acrylate Solution Market
This analysis serves as a strategic preview of our full report, highlighting the macroeconomic trajectories, regulatory undercurrents, and competitive dynamics that define the current landscape. For decision-makers, the imperative is clear: understanding the surface-level revenue figures is insufficient. Success in the 2026 market requires a granular understanding of compliance risks, material cost volatility, and the shifting preferences of both residential and commercial buyers.
Worldwide T-R Modules Market
The Macroeconomic Trajectory: Growth Amidst Uncertainty
The global stainless steel cookware market has demonstrated resilient growth over the past half-decade, recovering from pandemic-era disruptions and adapting to post-pandemic consumer behaviors. Our historical analysis tracks revenue movements from 2020 through 2025, laying a robust foundation for forecasting the period through 2032. The data indicates a steady upward trajectory, suggesting that despite inflationary pressures and raw material fluctuations, demand for durable, high-performance cookware remains inelastic among core consumer segments.
Worldwide Anticoagulation Tube Market
Entering 2026, the market valuation reflects this sustained momentum. The forecast period projecting out to 2032 suggests a compound annual growth rate that underscores the category's stability. This growth is not uniform; it is propelled by specific drivers that vary by geography and application, though the aggregate trend points toward a significant expansion of total addressable market value. For strategic planners, this implies that market entry or expansion strategies relying on static assumptions are likely to underperform. Instead, dynamic modeling that accounts for the varying velocity of growth across different horizons is essential.
The revenue projections for the late 2020s and early 2030s indicate a market that continues to mature. As the base year data transitions into the forecast period, the incremental value added each year highlights the cumulative effect of population growth, urbanization in emerging economies, and the persistent preference for stainless steel as a non-reactive, long-lasting material. However, the rate of expansion invites scrutiny regarding market saturation in developed regions versus the untapped potential in others.
Regulatory Headwinds and Material Dynamics: The 2026 Compliance Landscape
One of the most critical dimensions of our research focuses on the regulatory environment, which has become increasingly stringent regarding material safety. The narrative around cookware safety has shifted significantly following recent announcements from federal and state bodies. In August 2025, the FDA issued a safety alert warning about imported cookware potentially leaching lead into food. This was not an isolated incident; by December 2025, the FDA expanded this warning to include two additional cookware products on its lead-leaching list.
For manufacturers and retailers, these regulatory updates are not merely compliance checkboxes but strategic risk factors. The implication for the stainless steel sector is nuanced. While stainless steel itself is generally excluded from certain lead restrictions applicable to aluminum or brass, the broader consumer sentiment regarding "safe cookware" is shifting. Washington State, for instance, implemented a law effective January 1, 2026, prohibiting aluminum or brass cookware containing more than 90 ppm lead, with further tightening to 10 ppm by 2028. Although this specific regulation excludes stainless steel, it raises the overall bar for product safety marketing and supply chain transparency across all categories.
Furthermore, trade policy remains a volatile variable. U.S. reciprocal tariffs under Executive Order 14257, effective from April 2025, impose an additional ad valorem duty on most imports. For an industry where a significant portion of manufacturing capacity is located overseas, particularly in China and Brazil, these tariffs directly impact landed costs and margin structures. Our report dissects how these trade measures interact with regional price sensitivities and whether they accelerate near-shoring trends among key players.
Raw material cost volatility also plays a pivotal role in profitability. Price data from mid-2025 indicated significant variance between grades, with grade 304 stainless steel ranging notably higher than grade 430. This spread influences product tiering strategies. Companies must decide whether to absorb these costs to maintain market share or pass them through to consumers, risking price elasticity thresholds. The research provides a detailed breakdown of how these input cost fluctuations correlate with retail pricing strategies across different tiers of the market.
Competitive Dynamics: A Fragmented Yet Concentrated Arena
The competitive landscape of the stainless steel cookware market is characterized by a mix of established legacy brands, specialized artisanal manufacturers, and large-scale contract producers. Our analysis of key companies reveals a ecosystem where differentiation is driven by construction technology, origin of manufacture, and brand heritage.
On one end of the spectrum, premium brands such as All-Clad and Made In focus heavily on multi-ply construction and domestic or European manufacturing origins. All-Clad, based in Pennsylvania, specializes in bonded sets with a reputation for even heating and durability, commanding a price premium based on performance heritage. Similarly, Made In offers five-ply constructions produced in the USA or Italy, leveraging origin as a key value proposition. Hestan Culinary, another high-end player from San Francisco, pushes the boundary with professional-grade lines like ProBond and NanoBond, targeting enthusiasts who seek commercial performance in residential settings.
In the mass-premium and accessible segments, companies like Cuisinart and Calphalon maintain strong market presence. Cuisinart's Chef's Classic and Multiclad lines offer high-performance construction at more accessible price points, while Calphalon emphasizes nontoxic 18/10 stainless steel lines with a focus on even heat distribution. These brands bridge the gap between professional aspirations and everyday utility.
The market also features significant players from emerging manufacturing hubs. Tramontina, headquartered in Brazil, produces tri-ply clad sets widely available for both home and commercial use, offering a competitive value proposition that has captured substantial market share in North America. From the Middle East, El-Zenouki Group produces premium cookware under the Zinox brand, with a recent strategic target to raise output to 1 million pieces by 2026, signaling aggressive capacity expansion amidst sales growth. In China, manufacturers like AXA Cookware and Jiangmen Xinhui Jincui Metalware focus on varying ply constructions, catering to medium to premium markets with an emphasis on precision manufacturing and food-safe encapsulation. Wholesale and contract manufacturing dynamics are further represented by entities like Solamex Home and West Bend Company, the latter providing custom contract manufacturing within the USA.
Market concentration metrics suggest that while there are dominant players, the market remains relatively fragmented. The top three and top five companies hold specific shares of the overall revenue, indicating room for niche players and private label expansion. However, consolidation trends and the high cost of compliance with new safety standards may favor larger entities with deeper regulatory affairs resources. The full report details the strategic positioning of these key companies, analyzing their recent developments, product launches, and how they navigate the tariff and regulatory environment.
Segmentation Nuances: Type, Application, and Regional Variance
A superficial view of the market hides the critical nuances of segmentation. While aggregate data provides the macro picture, the strategic value lies in understanding how revenue is distributed across product types, applications, and regions. Our research delineates the market into core product categories, primarily pots and pans, alongside other specialized items. The balance between these categories shifts based on consumer cooking habits and professional kitchen requirements.
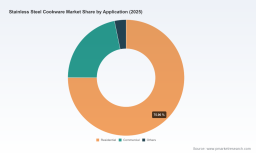
Similarly, the application split between residential and commercial use presents distinct growth drivers. The residential segment remains the volume driver, influenced by home cooking trends and gifting behaviors. However, the commercial segment offers higher stickiness and volume consistency, driven by restaurant turnover and institutional procurement standards. The interplay between these segments is vital for companies deciding where to allocate marketing spend and R&D resources.
Geographically, the market displays varying levels of maturity. North America and Europe represent established markets with high brand loyalty and sensitivity to premium features. Asia Pacific represents a vast growth engine, driven by urbanization and a growing middle class, though price sensitivity remains higher. Latin America and the Middle East and Africa constitute smaller but strategically significant niches, often influenced by import dynamics and local manufacturing capabilities. The report avoids simplistic regional generalizations, instead offering a nuanced view of how global trends manifest locally. It is crucial for strategists to understand that a strategy winning in North America may not translate directly to Asia Pacific without significant adaptation to local material preferences and purchasing power.
Strategic Imperatives for 2026 Decision Makers
As we navigate the remainder of 2026 and look toward 2032, several strategic imperatives emerge for stakeholders in the stainless steel cookware market.
-
Regulatory Agility: With lead safety warnings expanding and state-level regulations tightening, companies must invest in robust supply chain auditing. Ensuring that all components, even those not directly covered by stainless steel exclusions, meet heightened consumer safety expectations is vital for brand reputation.
-
Tariff Mitigation Strategies: In light of new import duties, sourcing strategies need re-evaluation. Companies may need to consider diversifying manufacturing bases or adjusting pricing architectures to maintain margins without sacrificing volume.
-
Material Innovation vs. Cost Management: The fluctuation in raw material prices between different steel grades requires careful product portfolio management. Balancing the use of high-grade stainless steel for premium lines against cost-effective grades for mass market offerings is a key lever for profitability.
-
Competitive Differentiation: In a market where construction technology (ply count, bonding methods) is a major differentiator, brands must clearly communicate performance benefits. Whether through multi-ply setups like those from Made In or professional-grade options from Vollrath, clarity of value proposition is essential.
-
Commercial Segment Expansion: Given the stability of the commercial sector, manufacturers might find growth opportunities by deepening penetration in professional kitchens, leveraging induction-ready options and durability claims that resonate with commercial buyers.
The data indicates that the market is on a growth path, but the path is fraught with regulatory and economic variables. The companies that will thrive are those that treat this research not just as a benchmark for size, but as a toolkit for navigating complexity.
Conclusion: Accessing the Full Intelligence
This overview provides a snapshot of the strategic landscape defining the stainless steel cookware market in 2026. It highlights the revenue growth trends, the critical regulatory shifts regarding lead and tariffs, the competitive maneuvers of key players like All-Clad, Tramontina, and Zinox, and the segmentation dynamics that drive revenue. However, this surface-level insight is merely the prelude to a much deeper body of work.
The full market research report from PW Consulting offers a granular level of detail that is indispensable for precise planning. It contains specific quantitative data across regions, detailed competitive profiling, comprehensive regulatory timelines, and deep dives into raw material cost histories that are essential for financial modeling and risk assessment. For executives who need to justify investment decisions, set pricing strategies, or evaluate market entry opportunities, the complete dataset provides the confidence required to act decisively.
To secure the complete strategic intelligence necessary to navigate the 2026–2032 forecast period, we invite you to access the full report. The detailed segmentation data, exclusive company profiles, and nuanced analysis of market dynamics await.
For detailed analysis of this topic, please visit the official page: Stainless Steel Cookware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


