



PW Consulting: Nanoimprint Lithography Market Valued at USD 114.01 Million in 2025, Projected 9.55% CAGR to 2032

Strategic Imperative in a Decarbonizing Lithography Landscape: Why the Nanoimprint Lithography System Market Study Defines 2026 Decision-Making
The semiconductor and advanced manufacturing industries are standing at a structural inflection point. For over a decade, extreme ultraviolet lithography has dictated the pace of miniaturization, but its capital intensity, energy footprint, and mask complexity are forcing manufacturers to reconsider the economics of patterning at scale. Nanoimprint lithography has moved from a niche prototyping curiosity to a credible production alternative, particularly where throughput, energy efficiency, and large-area uniformity matter more than absolute node leadership. Our latest Nanoimprint Lithography System Market report translates this transition into an execution-ready intelligence framework, engineered specifically for the strategic decisions that will shape 2026 and the forecast horizon through 2032.
Threads for Hand Embroidery Market
This article does not attempt to replace the full study. Instead, it functions as a precision preview: it explains why the analysis matters now, what decision-makers will find inside, and how the competitive and operational landscape is evolving. Core segmentation values, regional revenue splits, and application-level financial breakdowns are intentionally withheld here. Those figures are embedded in the complete dataset and interactive modules, because durable strategy requires the precision that only the full report can deliver.
Data Center Environment Monitoring Host Market
Why 2026 Is a Defining Year for NIL Investment and Adoption
The macro trajectory is clear. The nanoimprint lithography system market has expanded from approximately 79.0 million USD in 2020 to an estimated 114.01 million USD in 2025, and the forecast extends that momentum to 214.9 million USD by 2032, supported by a compound annual growth rate of 9.55 percent. These are not just numbers. They express a market that has passed the early-adopter phase and is entering a period where procurement cycles, capacity planning, and supplier selection have real balance-sheet consequences.
Worldwide 100% Cotton Sanitary Napkin Market
Several forces converge in 2026 to make disciplined analysis essential. First, industrial adoption is being reinforced by standardization activity. The NIL Industrial Day 2026 conference in Berlin highlighted ongoing efforts to align process control, metadata exchange, and qualification pathways for photonics and advanced manufacturing. Standardization reduces integration risk, which in turn accelerates the willingness of engineering leaders to commit to NIL lines. Second, the energy argument is becoming operational rather than theoretical. By eliminating the need for complex EUV light sources and high-energy masks, nanoimprint systems can reduce overall process energy consumption by up to one-tenth relative to traditional photolithography in applicable use cases. In an environment where sustainability metrics increasingly influence site selection, equipment financing, and customer qualification, that efficiency delta is strategically meaningful.
Third, the supply side is maturing. Hard quartz molds and fused silica stamps remain the reference standard for high-resolution NIL patterning, offering extended service life compared with softer alternatives. That durability matters because throughput, defect density, and stencil longevity directly shape total cost of ownership. At the same time, recent commercial milestones show that semiconductor-grade step-and-repeat systems are moving from demonstration to delivery, and foundry-style service models are becoming a repeatable pathway for optical and photonic component makers. These are the kinds of developments that shift NIL from a laboratory conversation to a plant-floor decision.
What the Report Delivers: An Action-Oriented Intelligence Architecture
The study is built around decision utility rather than data volume. It connects market sizing to the operational questions that vice presidents of technology, procurement, advanced packaging, and R&D actually face when evaluating nanoimprint lithography systems. The report structure is designed to support four core activities: market entry timing, platform selection, competitive positioning, and supply-chain risk management.
The foundation is a rigorously constructed revenue model covering the historical window from 2020 through 2025 and the forecast period from 2026 through 2032. The model is anchored in disclosed system shipments, technology adoption curves, end-market demand signals, and the shifting economics of patterning across semiconductors, consumer electronics, and adjacent fields. Rather than presenting a single line forecast, the analysis separates trend logic from point estimates so that leadership teams can test assumptions against their own product roadmaps and capacity plans.
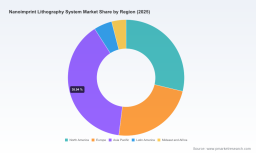
Beyond top-line sizing, the report provides a layered segmentation architecture that clarifies where growth is structurally strongest and why. The type dimension distinguishes UV-based nanoimprint lithography, hot embossing, and other approaches, helping buyers understand which process class aligns with throughput targets, thermal budgets, and pattern fidelity requirements. The application dimension maps demand across semiconductors, consumer electronics, and other end-use areas, enabling managers to prioritize development partnerships and pilot lines where adoption curves are steepest. The regional dimension situates demand and supply concentration across major geographic markets, giving executives a grounded view of where capacity is expanding, where integration support is maturing, and where procurement risk may be rising.
Crucially, the report does not stop at segmentation. It translates those splits into operational interpretation. For each major category, the analysis addresses the practical implications for tooling selection, mold and stamp strategy, process control, and integration with existing fab or panel-line workflows. The goal is to help teams convert market structure into procurement criteria and pilot-design choices, not merely to read growth rates in isolation.
Competitive Landscape: From Market Leaders to Emerging Contenders
The competitive field in nanoimprint lithography is both internationally diverse and technologically specialized. The report profiles the companies that are actively shaping system architecture, service models, and adoption pathways, and it situates each player within the broader market structure. Concentration is meaningful but not absolute: the combined share of the top three firms stands at roughly 34.5 percent, while the top five reach about 42.0 percent. That distribution signals a market where leadership positions exist, yet meaningful room remains for differentiated tools, specialty services, and regional execution advantages.
EVG remains a market-leading supplier of UV-NIL and SmartNIL systems, with a clear orientation toward volume production of 300 mm wafers and large-area panels for electronics and semiconductors. Its footprint matters because it ties nanoimprint tooling to established production formats, reducing adoption friction for organizations that want to build on familiar wafer and panel workflows. Canon continues to advance step-and-repeat NIL for semiconductor R and D and prototype production, with a publicly articulated roadmap toward 10 nm features. Canon’s relevance lies not only in hardware but in the credibility it brings to NIL as a path that can support advanced research while moving toward tighter patterning targets.
NIL Technology ApS occupies a specialized but strategically important position in meta-optics, metalenses, and nano-optics devices, offering both systems and mass-production services. As optical architectures become more complex and form factors more demanding, that combination of tooling and production expertise is increasingly valuable. Obducat AB operates as a world-leading supplier of micro- and nano-lithography solutions, including NIL systems and foundry services for photonics and advanced patterning. Its recent three-year foundry service agreement, valued at at least 115 million SEK, underscores how NIL-enabled optical manufacturing is becoming a contracted, recurring revenue model rather than a one-off pilot.
Nanonex Corporation is recognized as a pioneer of versatile NIL tools spanning UV and thermal approaches, with applications in 3D nanostructures, large-area patterning, and semiconductor workflows. That versatility is strategically relevant for organizations that need flexibility across pattern geometry and substrate types. In China, Prinano Technology has emerged as a developer and supplier of semiconductor-grade step-and-repeat NIL systems using quartz molds for chip production, and it delivered its first domestically developed PL-SR series system to a specialty-process customer in August 2025. GermanLitho complements this landscape as a manufacturer of fully automatic 200 mm and 300 mm NIL mass-production systems and supporting equipment for high-resolution nanostructures. Together, these players indicate a widening base of production-oriented capability, not just research-grade instrumentation.
The report also captures the operational signals that matter more than press releases. The July 2025 expansion of NIL line capabilities by Tekscend Photomask Japan, the May 2026 Obducat foundry agreement for defense-adjacent optical component manufacturing, and NIL Technology ApS’s role as a key speaker on NIL strategy for nano-optics at NIL Industrial Day 2026 all point to the same conclusion: the ecosystem is building the practical scaffolding needed for broader industrial use. Standardization discussions, service-model innovation, and mask and stamp infrastructure are advancing in parallel with system hardware.
Market Dynamics: Standardization, Energy, and Supply-Chain Realities
Beneath the headline growth numbers lies a set of dynamics that will determine which organizations capture value and which merely follow. Standardization is one of the most underappreciated enablers. When industry events and working groups begin aligning on process Qualification, data handling, and acceptance criteria, the perceived risk of committing to a new patterning modality declines. The NIL Industrial Day 2026 program in Berlin made that point explicitly, especially for photonics and advanced manufacturing, where repeatability and interface compatibility often matter more than chasing the absolute finest feature sizes.
Energy and process simplicity form a second dynamic. The potential to reduce process energy consumption to about one-tenth of traditional photolithography in applicable workflows is not just a sustainability talking point; it influences utility planning, thermal management, facility design, and long-term operating cost. As manufacturers weigh total cost of ownership more carefully, the absence of complex EUV light sources and high-energy masks becomes a tangible economic advantage for suitable pattern classes.
Supply-chain continuity is the third dynamic, and it is increasingly visible in commercial commitments. The three-year foundry service agreement signed in May 2026 for photonic components illustrates how NIL-enabled manufacturing is being embedded into multi-year delivery contracts. That kind of commitment stabilizes demand visibility for suppliers and gives buyers confidence that capacity and service support are not ephemeral. It also reflects a broader trend in which NIL is moving into foundry and service-based models, allowing end users to access nanoimprinted components without owning the full equipment stack.
Material and tooling durability round out the operational picture. The continued reliance on quartz molds and fused silica stamps for high-resolution patterning reinforces the importance of mold lifecycle management, inspection, and replacement planning in any deployment economics. Hard molds extend service life relative to softer alternatives, but they also place a premium on precision tooling, handling protocols, and defect control. In other words, the market is not only about who sells the system; it is also about who can sustainably support the tooling and process ecosystem around it.
How to Use the Study for 2026 Strategic Decisions
The report is designed to be used, not merely read. For executives evaluating whether and where to invest in nanoimprint lithography, the study provides a structured way to translate adoption signals into procurement timing, pilot scope, and partnership strategy. For suppliers and technology developers, it offers a clear map of where demand resonance is strongest and where differentiation is still available. For investors and advisors, it connects market structure to concentration, regional dynamics, and the evolving balance between system vendors and service-oriented models.
A few practical applications stand out. First, the historical-to-forecast revenue bridge supports capacity planning and scenario testing. Teams can compare internal product-roadmap assumptions against the study’s adoption logic and demand trajectory, then adjust pilot scale, pilot duration, and qualification milestones accordingly. Second, the segmentation architecture helps prioritize where to concentrate engineering effort and commercial resources. Rather than treating NIL as a single opportunity, organizations can align platform choices with the process classes, end-use areas, and geographies that best match their capabilities and risk tolerance. Third, the company profiles and recent developments give decision-makers a current view of who is shipping production-oriented systems, who is expanding service models, and who is shaping standardization and integration support.
The report’s concentration data also matters for strategy. A top-three share near 34.5 percent and a top-five share near 42.0 percent indicate that incumbents hold meaningful positions, but the market still permits competitive entry through specialized tooling, regional execution, or service-based delivery. That has direct implications for supplier selection, negotiation posture, and partnership design. Organizations that understand where concentration is real and where fragmentation remains can structure procurement and collaboration strategies more effectively than those that assume either a monopoly or a fully commoditized market.
Why This Preview Cannot Replace the Full Report
A responsible preview must draw a clear line between context and precision. The narrative above establishes the strategic backdrop: a market that has grown from 79.0 million USD in 2020 to 114.01 million USD in 2025, a forecast trajectory toward 214.9 million USD by 2032, a CAGR of 9.55 percent, and a competitive landscape shaped by internationally diverse players, evolving service models, and active standardization efforts. It also explains why those trends matter for 2026 decisions. What it does not do is expose the detailed numbers that turn context into execution.
The full study contains the segment-level revenue values, regional demand distribution, type-level and application-level breakdowns, and the accompanying interpretive analysis that connects each split to operational decision-making. Those details are deliberately withheld here because their value is highest when viewed in full context, alongside the forecast logic, supply-side dynamics, and competitive profiles that support them. Releasing selective sub-values in a preview would reduce the integrity of the dataset and undercut the decision quality the report is designed to enable.
This is the intended design. The preview builds trust by demonstrating analytical rigor and market familiarity; the complete report delivers the granularity required to act. For teams planning procurement cycles, pilot investments, capacity additions, or competitive positioning in 2026, the difference between direction and detail is the difference between a plausible hypothesis and a defensible plan.
Conclusion: Turning Market Structure Into 2026 Advantage
Nanoimprint lithography is no longer an alternative that can be deferred indefinitely. The combination of energy efficiency, tooling versatility, foundry-style service expansion, and standardization momentum is making NIL a practical consideration for a widening set of production scenarios. At the same time, the market’s structure—steady double-digit growth, meaningful but not absolute concentration, and a widening field of international participants—means that success will depend on precise segmentation insight, current competitive awareness, and disciplined scenario planning.
The full Nanoimprint Lithography System Market report is built for exactly that purpose. It converts a complex and fast-moving landscape into a structured intelligence base that supports 2026 decisions on platform choice, investment timing, supplier strategy, and regional prioritization. The macro path is visible here; the segment-level precision, interpretive depth, and decision frameworks are delivered in the complete study. For organizations that need to move from awareness to action, that is the intelligence worth securing now.
For detailed analysis of this topic, please visit the official page: Nanoimprint Lithography System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


