



PW Consulting Report: Automated Biochemical Analyzers Market Hits $3,145.49M in 2025, Projects 5.51% CAGR to 2032

Navigating the Future of Diagnostics: Strategic Insights into the Automated Biochemical Analyzers Market
The global healthcare landscape is undergoing a profound transformation, driven by the relentless demand for faster, more accurate, and cost-effective diagnostic solutions. At the heart of this evolution lies the automated biochemical analyzer, a cornerstone technology in clinical laboratories, pharmaceutical research, and healthcare institutions worldwide. As we move deeper into 2026, organizations operating within this sector face a complex matrix of opportunities and challenges that require more than just intuition—they demand rigorous, data-backed strategic intelligence. PW Consulting's latest market research report on Automated Biochemical Analyzers is designed to provide precisely that clarity, offering a comprehensive roadmap for stakeholders aiming to capitalize on the next phase of industry growth.
This analysis serves as a strategic prelude to our full-length market study. While the following insights highlight the macro-level trajectories and critical dynamics shaping the landscape, the complete report delves into granular segmentation, competitive benchmarking, and actionable forecasts that are essential for precise decision-making. For executives, investors, and industry leaders, understanding the overarching narrative is the first step toward securing a competitive advantage in a market defined by rapid technological iteration and shifting regulatory frameworks.
Macro Market Trajectory: Growth Drivers and Historical Context
The market for automated biochemical analyzers has demonstrated resilient expansion over the past half-decade, reflecting broader trends in healthcare infrastructure development and the increasing adoption of high-throughput diagnostic systems. Based on comprehensive historical analysis from 2020 through 2025, the global market has evolved from a valuation of approximately $2,426.75 million in 2020 to an estimated $3,145.49 million by the base year of 2025. This steady upward trajectory underscores the critical role these instruments play in modern medical diagnostics and research workflows.
Looking forward, the forecast period extending from 2026 to 2032 projects continued momentum, with the market expected to reach $4,525.81 million by the end of the forecast horizon. This growth is underpinned by a compound annual growth rate (CAGR) of 5.51%, signaling a mature yet steadily expanding ecosystem. Such figures are not merely abstract statistics; they represent the collective investment of healthcare providers, research institutions, and pharmaceutical companies in automating complex biochemical processes. The sustained growth rate indicates that despite economic fluctuations and supply chain complexities, the fundamental demand for reliable, automated analysis remains robust.
Key drivers propelling this expansion include the rising prevalence of chronic diseases necessitating regular monitoring, the integration of advanced automation technologies to reduce human error, and the expanding footprint of diagnostic laboratories in emerging economies. Furthermore, the pharmaceutical sector's aggressive pursuit of novel therapeutics continues to fuel demand for high-precision analyzers in drug discovery and development pipelines. However, realizing the full value of this growth requires a nuanced understanding of how different market segments interact and where specific opportunities lie, details of which are exhaustively covered in our full report.
Structural Dynamics and Technological Segmentation
The market architecture is defined by distinct technological classifications and application verticals, each presenting unique value propositions and adoption challenges. The division between fully automated and semi-automated systems remains a critical strategic consideration for procurement managers and laboratory directors. Fully automated solutions offer unparalleled throughput and operational efficiency, making them ideal for large-scale clinical settings, while semi-automated variants provide flexibility and cost-effectiveness for smaller facilities or specialized research applications. The balance between these two categories shapes procurement strategies and capital expenditure planning across the industry.
Application-wise, the demand is diversified across clinical diagnostics, drug discovery, research, and other specialized uses. Clinical diagnostics continues to represent the largest share of consumption, driven by routine patient testing and preventive healthcare initiatives. Simultaneously, the drug discovery sector leverages these analyzers for metabolic profiling and biomarker validation, highlighting the technology's versatility beyond traditional hospital settings. Research institutions also contribute significantly, utilizing automated platforms for experimental consistency and data reliability. Each application segment carries its own regulatory requirements, reimbursement landscapes, and performance expectations, necessitating a tailored approach to market entry or expansion.
Our detailed study dissects these segments with precision, offering insights into volume trends, pricing dynamics, and adoption rates that are not visible in high-level summaries. Understanding the interplay between type and application is essential for companies looking to position their products effectively or for investors seeking to identify high-potential niches within the broader ecosystem.
Competitive Landscape: Key Players and Recent Developments
The competitive environment is characterized by a mix of established multinational giants and emerging regional players, all vying for market share through innovation, strategic partnerships, and regulatory approvals. Major corporations such as Roche Diagnostics, Abbott Laboratories, and Siemens Healthineers continue to dominate the high-end segment with integrated solutions that combine clinical chemistry and immunoassay capabilities. Roche's cobas series, Abbott's Alinity systems, and Siemens' Atellica platforms exemplify the industry's push toward consolidated, high-throughput workflows that maximize laboratory efficiency.
In parallel, companies like Beckman Coulter, QuidelOrtho, and Mindray are expanding their footprints with scalable solutions tailored to diverse laboratory sizes and budgets. Beckman Coulter's recent FDA clearance for the DxC 500i integrated analyzer in March 2025 highlights the ongoing commitment to enhancing integrated testing capabilities. Similarly, QuidelOrtho's launch of the Certified Analyzer Program for VITROS systems in August 2025 demonstrates a strategic focus on expanding access in rural and community hospitals, addressing a critical gap in healthcare equity. Meanwhile, YHLO Biotech's introduction of the iBC 2000 fully automated analyzer at the CACLP trade show in March 2025 signals the rising competitiveness of manufacturers based in key growth regions.
Electrolyte Analyzers Market
Roche Diagnostics further reinforced its market position in March 2026 with FDA 510(k) clearance for the cobas c 703 and ISE neo analytical units, integrated into the cobas pro solutions. Such regulatory milestones are critical indicators of market momentum and product viability. Other notable participants, including YSI Life Sciences, Agappe Diagnostics, Eurolyser Diagnostica, Meril Diagnostics, and YHLO Biotech, contribute to a dynamic ecosystem where innovation is constant and geographic diversification is key. The presence of regional specialists often brings localized support and cost advantages that global players must account for in their strategic planning.
Regulatory and Operational Dynamics
Navigating the regulatory environment is as crucial as technological innovation for sustained success in this market. Automated biochemistry analyzers are classified as Class II medical devices, requiring 510(k) premarket notification or FDA clearance for market entry in the United States. This regulatory framework ensures safety and efficacy but also imposes timeline and cost considerations that can influence product launch strategies. Recent events, such as the Class 2 Device Recall for the Beckman Coulter DxC 500 AU Clinical Chemistry Analyzer in February 2025 due to software design issues, serve as reminders of the operational risks associated with complex instrumentation and the importance of robust quality management systems.
Automated Biochemical Analyzers Market
Reimbursement policies and procurement frameworks also play a pivotal role in market accessibility. Clinical chemistry testing utilizing instrumented chemistry analyzers is covered under CPT code 80306, which directly impacts the financial viability of laboratory tests for providers and patients. Additionally, clinical laboratory analyzer service contracts fall under the VA Federal Supply Schedule 66 III, encompassing immunochemistry, chemistry, coagulation, hematology, microbiology, and urinalysis analyzers. These contractual mechanisms influence public sector procurement and set benchmarks for pricing and service levels across the industry. Stakeholders must stay abreast of these evolving regulations and reimbursement codes to optimize their market strategies and ensure compliance.
Strategic Value of Comprehensive Market Intelligence
In an industry where capital investments are significant and technological lifecycles are accelerating, relying on surface-level data is insufficient. The true value of PW Consulting's Automated Biochemical Analyzers Market report lies in its ability to translate macro trends into actionable strategies. By analyzing market concentration metrics, where the top three players hold a combined share of 25.6% and the top five account for 34.2%, organizations can better assess competitive intensity and identify whitespace opportunities. Such concentration levels indicate a market that is moderately fragmented, allowing room for both consolidation and niche disruption.
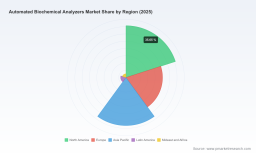
The report provides deep dives into regional performance, type-specific adoption curves, and application-based revenue streams, enabling clients to benchmark their position against peers and identify high-growth corridors. For manufacturers, this means refining product development roadmaps to align with emerging needs. For investors, it means pinpointing companies with sustainable competitive advantages. For healthcare administrators, it means optimizing procurement decisions to balance cost, quality, and future scalability.
To access the full spectrum of data, including detailed segmentation analysis, competitive profiling, and forward-looking forecasts that will drive your 2026 decisions, we invite you to explore the complete report. The macro insights presented here are merely the beginning of a comprehensive intelligence framework designed to empower your organization in a rapidly evolving diagnostic landscape. Secure your competitive edge by leveraging the depth and precision of our latest research.
For detailed analysis of this topic, please visit the official page: Automated Biochemical Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


