



PW Consulting: Home Security Market Hits $67M in 2025, Projects 8.92% CAGR Growth Through 2032

Strategic Intelligence for the Modern Defender: Inside the 2026 Home Security Market
The residential security landscape has fundamentally shifted. Where once the market was defined by simple alarm panels and reactive monitoring, it is now a complex ecosystem of AI-driven surveillance, interconnected smart home automation, and nuanced consumer preferences between professional installation and do-it-yourself flexibility. For executives, investors, and strategic planners, navigating this evolution requires more than surface-level observation. It demands rigorous, data-backed intelligence that connects historical momentum with forward-looking forecasting. Our newly released Home Security Market research report provides exactly that blueprint, offering a comprehensive lens into the forces shaping the industry from 2026 through 2032.
This analysis is not merely a collection of figures. It is a strategic decision-making framework designed to help organizations anticipate demand shifts, evaluate competitive positioning, and allocate capital with precision. By synthesizing historical performance data with projected growth trajectories, the report equips stakeholders with the contextual depth required to operate confidently in an increasingly automated and regulation-sensitive market.
A Market in Structured Expansion
Over the past five years, the home security sector has demonstrated consistent, compounding growth. Historical revenue data from 2020 through 2025 reveals a steady upward trajectory, with the market expanding from a baseline of 42.36 million USD to a projected 67.32 million USD by the close of 2025. This growth reflects sustained consumer investment in residential protection, driven by rising urbanization, increased connectivity, and a broader cultural shift toward proactive home management.
Looking ahead, the forecast period from 2026 to 2032 indicates that this momentum will not only continue but accelerate in strategic pockets. The market is projected to reach 73.17 million USD in 2026, with annual figures climbing steadily toward a projected 122.8 million USD by 2032. Underlying this expansion is a compound annual growth rate of 8.92%, a metric that signals durable, long-term demand rather than cyclical volatility. For corporate strategists, this growth curve translates into clear implications: sustained product development cycles, expanding go-to-market opportunities, and the necessity of agile infrastructure planning to accommodate scaling consumer adoption.
Structural Composition and Application Realities
Beneath the aggregate growth figures lies a layered segmentation structure that defines how value is distributed across the market. Hardware-centric categories continue to anchor the industry, with cameras and monitoring systems representing the largest share of market activity. This dominance is logical, as visual verification remains the cornerstone of modern threat detection and consumer confidence. Alarms and sensors form the second major pillar, providing the foundational layer of intrusion detection and environmental monitoring that complements camera networks. A smaller but strategically significant segment is occupied by locks and access control, a category whose relevance is expanding as smart entry solutions integrate seamlessly with broader residential automation ecosystems.
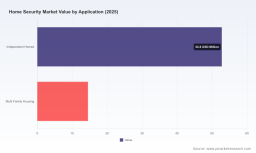
On the application side, the market reflects distinct residential deployment patterns. Independent homes continue to represent the primary adoption channel, capturing the majority of system installations and upgrade cycles. Multi-family housing constitutes a meaningful secondary segment, driven by property management requirements, centralized monitoring demands, and the growing emphasis on tenant safety in dense urban environments. Understanding how these application dynamics interact with regional deployment realities and pricing sensitivities is essential for any organization designing targeted product bundles or channel strategies.
While the structural outline is clear, the precise allocation of market share across regions, product types, and end-use applications contains critical nuance that can only be fully leveraged through the complete dataset. The report's detailed segmentation breakdowns reveal the exact magnitude of regional performance, the proportional weight of each product category, and the application-level demand patterns that inform inventory planning, pricing architecture, and geographic expansion priorities. These granular insights are deliberately reserved for the full publication, ensuring that stakeholders who require actionable precision have a direct pathway to the complete intelligence.
Competitive Architecture and Strategic Positioning
The home security market is characterized by a concentrated competitive landscape, with the top three firms accounting for approximately 62 percent of total market share and the top five firms collectively commanding roughly 72 percent. This concentration underscores the strategic importance of differentiation, technological innovation, and service integration in maintaining or expanding market position. The leading participants operate across a spectrum of business models, ranging from professionally installed, fully monitored residential systems to flexible, consumer-centric DIY platforms that emphasize no-contract flexibility and wireless deployment.
ADT, headquartered in Florham Park, New Jersey, continues to lean into professional monitoring, professional installation, and AI-powered smart home security systems. Its market approach emphasizes end-to-end service delivery and continuous enhancement of intelligent detection capabilities. Vivint, based in Lehi, Utah, competes through professionally installed, fully integrated smart home security and automation systems paired with ongoing monitoring, positioning itself at the intersection of security and holistic home automation. Ring LLC, operating from San Jose, California, has carved a distinct niche with video doorbells, cameras, and AI-powered alarm systems that serve both DIY users and customers seeking professional monitoring options.
SimpliSafe, headquartered in Boston, Massachusetts, has built its identity around DIY wireless security systems with professional monitoring options and no-contract plans, appealing directly to consumers who prioritize flexibility and uncomplicated deployment. Alarm.com, based in Reston, Virginia, operates as a platform and software backbone for professional monitoring, video security, and integrated alarm systems, enabling a broad ecosystem of service providers and residential deployments. Brinks Home Security, located in Scottsdale, Arizona, delivers professional home security systems with monitoring and smart home integrations, reinforcing the traditional service-led model with modern connectivity features.
Further down the competitive field, Abode Systems in San Francisco focuses on wireless DIY smart home security systems with Apple Home integration, catering to users embedded in specific smart ecosystem environments. Eufy Security, based in San Diego, California, emphasizes battery-powered AI cameras, doorbells, and all-in-one security kits, targeting consumers who value portability, low-maintenance hardware, and integrated detection intelligence. Johnson Controls, headquartered in San Antonio, Texas, brings institutional-grade engineering to the residential space through upgraded security panels and integrated residential systems with monitoring, bridging commercial-grade reliability with home-use scalability.
Recent Developments Shaping Market Trajectory
The strategic posture of these market participants is actively evolving, and several high-impact developments from early 2026 illustrate how quickly the competitive battlefield is shifting. In February 2026, ADT acquired Origin AI to expand its smart home capabilities, leveraging AI-based Wi-Fi sensing technology that detects motion without cameras or wearables. This move signals a clear strategic intent to diversify detection modalities, reduce hardware dependency, and embed intelligence into the ambient environment of the home.
Home Security Market
Alarm.com executed a series of platform-level enhancements in the first quarter of 2026. In March, the company expanded its video security portfolio with new AI capabilities and flexible camera solutions, broadening its addressable use cases for professional installers and end users alike. Earlier in April, Alarm.com modernized legacy security systems by introducing an enhanced Universal Communicator designed to improve interoperability across heterogeneous device ecosystems. These initiatives reflect a broader industry theme: the transition from isolated, single-point installations toward unified, interoperable platforms that simplify monitoring, reduce integration friction, and increase system lifespan.
Johnson Controls reinforced its residential and small business security positioning in March 2026 by launching upgrades to its DSC PowerSeries Neo 5 and IQ Panel 5 systems, demonstrating continued investment in panel modernization and user interface refinement. Meanwhile, Ring LLC expanded its consumer hardware lineup in March with a new battery-powered smart doorbell series featuring 2K and 4K video models, highlighting the ongoing demand for high-resolution, wire-free entry-point monitoring. Collectively, these actions reveal a market in which incumbents and specialists alike are racing to enhance detection sophistication, improve deployment flexibility, and extend the functional boundaries of residential security.
Infrastructure, Regulation, and the Broader Operating Environment
Strategic planning in home security cannot occur in isolation from the external conditions that shape deployment economics and regulatory compliance. Infrastructure dynamics are exerting measurable pressure on expansion models. Recent assessments indicate that deployment costs for fiber-to-the-home networks have increased by more than 10 percent, driven by rising materials and labor expenses. With operation and maintenance averaging around 53 USD annually per home passed, connectivity-dependent security solutions must account for escalating back-end cost structures when evaluating service scalability, monitoring reliability, and long-term pricing assumptions.
Regulatory context adds another layer of strategic complexity. Recent judicial and administrative developments have reshaped the broadband classification debate, with a 2025 appellate ruling holding that the FCC lacks authority to classify broadband as a telecommunications service under Title II. This legal landscape intersects with earlier regulatory actions, including the April 2024 FCC vote on service reclassification, and carries implications for how connectivity-dependent security products, cloud-based monitoring, and video transmission services are governed, priced, and delivered. In parallel, global data transmission realities remain heavily reliant on subsea fiber-optic infrastructure, which carries an overwhelming share of intercontinental and transoceanic digital communications. These structural dependencies remind market participants that residential security is increasingly intertwined with the resilience, latency, and regulatory status of broader communication networks.
These environmental factors do not simply represent background noise. They influence vendor selection, monitoring architecture, consumer adoption thresholds, and the cost profile of networked security solutions. The full report integrates these dynamics into actionable scenarios, helping decision-makers model how infrastructure cost shifts and regulatory uncertainty could affect product roadmaps, channel economics, and service-level commitments over the forecast horizon.
What the Full Report Delivers for Enterprise Decision-Makers
This market study is structured to move beyond high-level trends and into the operational detail that executives, product leaders, and investment teams require. The complete report delivers a multi-dimensional view of the home security market, combining quantitative forecasting with qualitative competitive assessment and environmental context. It provides the analytical foundation needed to answer pressing strategic questions: which deployment models are gaining traction, how intelligent detection capabilities are reshaping consumer expectations, where regional demand intensity is concentrated, and how leading players are positioning their portfolios against one another.
The publication includes detailed segmentation analysis, historical and projected revenue trajectories, competitive profiling, recent corporate and product developments, and a structured examination of the regulatory and infrastructure variables that influence market execution. Each section is designed to support specific decision functions, from product roadmap prioritization and channel strategy refinement to M&A screening and market entry evaluation. By connecting macro-level growth signals with micro-level competitive intelligence, the report offers a single, coherent reference point for organizations operating across the residential security value chain.
For strategists who need precise regional performance figures, exact product-type valuations, and granular application-level breakdowns to inform investment committees or executive briefings, the full dataset is essential. These detailed splits are compiled within the complete report and are intended to provide the specificity required for scenario modeling, pricing strategy, and targeted geographic expansion planning.
Strategic Next Steps
The home security market is entering a phase in which growth, technology integration, and external operating conditions will increasingly determine which organizations capture durable share and which are left reacting to market shifts. With a projected compound annual growth rate of 8.92 percent and a clear trajectory toward sustained expansion through 2032, the opportunity landscape is substantial, but it will be captured by those who plan with precision.
Smart Home Security System Market
Our full Home Security Market research report is now available for leaders who require complete intelligence rather than summary-level conclusions. It provides the detailed segmentation, competitive profiling, and environmental analysis needed to convert market momentum into executable strategy. For decision-makers ready to move from observation to action, the complete report offers the depth, clarity, and strategic framing necessary to navigate one of the most dynamic residential technology sectors in the current market environment.
For detailed analysis of this topic, please visit the official page: Home Security Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


