



PW Consulting: LGF-PP Market Hits $7.67B in 2025, Projects 6.8% CAGR to $11.12B by 2032

Navigating the Long Glass Fiber Reinforced Polypropylene Landscape: Strategic Intelligence for 2026 and Beyond
Executive Overview
The long glass fiber reinforced polypropylene market stands at a critical inflection point. As manufacturers across automotive, aerospace, electrical, construction, and consumer goods sectors confront tightening emissions standards, escalating raw material volatility, and an accelerating demand for lightweight structural materials, the ability to make data-driven decisions has never been more consequential. Our latest Long Glass Fiber Reinforced Polypropylene Market report delivers a comprehensive, forward-looking intelligence framework designed specifically to equip executives, procurement leaders, and strategy teams with the analytical rigor required to navigate 2026 and the decade ahead.
Drawing on a five-year historical baseline spanning 2020 through 2025 and a robust seven-year forecast horizon extending to 2032, this research translates macro-level market trajectories into actionable strategic guidance. The global market, valued at approximately 5,745.2 million USD in 2020, has demonstrated a consistent upward trajectory, reaching an estimated 7,674.32 million USD by 2025. Looking ahead, the analysis projects a compound annual growth rate of 6.8 percent through 2032, positioning the sector for sustained expansion as material performance advantages converge with regulatory tailwinds and manufacturing innovation. This article outlines the strategic architecture of our research, previews the analytical dimensions that will inform your 2026 planning cycles, and demonstrates why this intelligence is indispensable for organizations seeking to capture growth, mitigate risk, and secure competitive advantage.
Market Trajectory and Forecasting Architecture
Our forecasting methodology is built on a multi-layered analytical foundation that integrates historical revenue patterns, demand elasticity modeling, supply-side capacity tracking, and scenario-based macroeconomic adjustments. The historical dataset captures the market's evolution through periods of raw material price fluctuation, shifting end-use demand, and regional manufacturing realignments. By anchoring projections to this empirically validated baseline, our forecast framework isolates growth drivers from transient market noise, enabling readers to distinguish between structural expansion and cyclical variation.
The 2026 to 2032 forecast period is segmented into phased growth trajectories that reflect the interplay of technological adoption curves, regulatory implementation timelines, and regional manufacturing capacity expansion. Rather than presenting a single linear projection, our analysis maps multiple demand pathways, allowing decision-makers to stress-test their strategies against divergent macroeconomic and policy environments. This approach is particularly valuable in a market where material substitution dynamics, automation-driven production efficiencies, and cross-industry application migration continuously reshape competitive positioning.
Segmentation Analysis: Navigating Application and Type Dynamics
Understanding where growth concentrates and how performance requirements diverge across end-use sectors is essential for resource allocation and product development prioritization. Our segmentation analysis dissects market demand across major application verticals, examining how structural performance thresholds, cost constraints, and regulatory mandates shape adoption patterns. Automotive structural components continue to represent a substantial share of demand, driven by the imperative to reduce vehicle weight while maintaining crashworthiness, fatigue resistance, and dimensional stability. Aerospace and electrical and electronics applications introduce distinct performance criteria, where thermal stability, electrical insulation properties, and long-term durability under stress become primary selection factors. Construction and consumer goods segments further illustrate the material's versatility, though each vertical presents unique procurement cycles, certification requirements, and price sensitivity profiles.
On the type dimension, the market splits between continuous fiber and chopped fiber configurations, each serving different engineering objectives. Continuous fiber architectures deliver superior tensile strength and stiffness, making them the preferred choice for load-bearing structural replacements where metal displacement is the strategic goal. Chopped fiber formulations offer distinct processing advantages, balancing mechanical reinforcement with manufacturing flexibility, shorter cycle times, and enhanced surface finish characteristics. Our research maps how these type-level preferences interact with application-specific performance requirements, production volume scales, and regional manufacturing capabilities, providing a granular view of where each configuration is likely to gain or lose share over the forecast horizon.
Regional Dynamics and Demand Localization
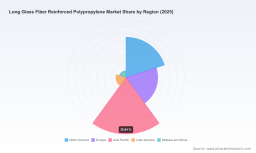
Geographic demand distribution reflects the interplay of industrial base maturity, regulatory environments, automotive production footprints, and infrastructure development cycles. North America and Europe maintain strong demand foundations, supported by established automotive supply chains, stringent emissions frameworks, and advanced manufacturing ecosystems. Asia Pacific represents a dynamic growth engine, characterized by expanding production capacity, diversifying end-use adoption, and increasing localization of compound manufacturing. Latin America and the Middle East and Africa markets continue to evolve, with demand trajectories influenced by infrastructure investment patterns, cost-competitive manufacturing shifts, and gradual adoption of advanced polymer composites in regional automotive and industrial applications.
Rather than relying on static regional snapshots, our analysis tracks how cross-border supply chain reconfigurations, tariff environments, and localized content requirements reshape regional demand pathways. This geographic intelligence is critical for organizations evaluating production footprint decisions, inventory positioning, and market entry or expansion strategies in 2026 and beyond.
Competitive Landscape and Strategic Positioning
The market's competitive structure is defined by a concentrated core of global polymer and compound manufacturers, complemented by specialized providers with deep application engineering expertise. With a combined market share held by the top three players reaching 59.0 percent and the top five firms accounting for 70.0 percent, the landscape rewards scale, technical differentiation, and long-term customer integration. Our competitive analysis examines how leading organizations leverage proprietary resin formulations, fiber impregnation technologies, and application-specific grading systems to secure positioning in high-value structural and technical segments.
SABIC has built a strong footprint through its STAMAX LGF PP resin platform, targeting automotive lightweighting and structural performance applications where consistent mechanical properties and process reliability are paramount. BASF SE advances its position through the Ultramid portfolio, delivering long glass fiber reinforced polypropylene solutions tailored for demanding technical applications that require precise control over fiber-matrix interaction and thermal performance. LyondellBasell Industries N.V. contributes to the competitive mix by supplying polypropylene compounds that integrate proprietary resin architectures with long glass fiber grades, serving automotive and structural use cases that demand balanced cost-performance profiles.
Japan Polypropylene Corporation distinguishes itself through proprietary melt impregnation processes, delivering FUNCSTER and WAYMAX compound platforms that emphasize fiber dispersion quality and mechanical consistency. RTP Company focuses on custom compound engineering, aligning its long glass fiber reinforced polypropylene offerings with specific automotive compliance requirements across major OEMs, including GM, Stellantis, Tesla, and Ford. Avient Corporation supports structural replacement strategies through its OnForce composite line, targeting high-stiffness applications where weight reduction and mechanical reliability intersect. Celanese Corporation extends the competitive field through Celstran grades, positioning long glass fiber reinforced polypropylene within broader engineered polymer portfolios for automotive and industrial applications. Mitsui Chemicals, Inc. reinforces its regional and global reach by producing long glass fiber reinforced polypropylene across facilities in Japan, the United States, and China, enabling supply chain flexibility and localized customer support.
Long Glass Fiber Reinforced Polypropylene Market
Our report moves beyond corporate profiles to examine how these players compete on technology differentiation, customer co-development, capacity utilization, and regional supply commitments. The analysis identifies where consolidation pressure may intensify, where niche specialization can defend margin, and how integrated material solutions are reshaping sourcing relationships across end-use industries.
Regulatory Tailwinds and Macroeconomic Dynamics
Regulatory frameworks are accelerating material substitution decisions across multiple industries, and long glass fiber reinforced polypropylene is directly benefiting from emissions-driven lightweighting mandates. In the European Union, the 2019/631 directive established average CO2 emission targets of 93.6 grams per kilometer by 2025, creating immediate incentives for weight reduction in structural automotive components. This trajectory extends further with the EU's requirement for a 55 percent CO2 reduction by 2030 compared to 2021 levels, reinforcing the strategic relevance of high-performance polymer composites in vehicle architecture planning. In the United States, EPA standards calling for an average fleet CO2 reduction to 162.5 grams per mile by 2030 are driving similar adoption patterns in North American automotive underbody and structural applications.
Worldwide Reinforced Polypropylene Material Market
Alongside regulatory momentum, raw material price dynamics play a decisive role in cost modeling and margin management. Recent industry data indicates that glass fiber prices in the United States reached approximately 1,458 USD per metric ton in December 2025, trending lower as domestic construction demand eased in the fourth quarter. Meanwhile, broader resin pricing pressures have emerged in other regions; in the United Kingdom, propylene price increases pushed compounded PP resin prices higher throughout the first quarter of 2025, with increases holding steady across the period. These dynamics underscore the importance of anticipatory procurement strategies, flexible sourcing frameworks, and scenario planning that accounts for commodity volatility, energy cost shifts, and regional supply imbalances.
Our report integrates these regulatory and input-cost signals into a unified market dynamics framework, helping organizations translate policy mandates and price movements into concrete procurement, pricing, and product development decisions.
What the Report Delivers: Operational Intelligence for Decision-Makers
This research is designed as an operational decision-support tool rather than a static market summary. It provides structured analytical modules that can be directly applied to strategic planning, investment prioritization, and competitive positioning. Key deliverables include:
- A full historical and forecast revenue timeline that maps market growth across multiple horizons, enabling baseline validation and scenario modeling.
- Segment-level demand analysis that connects application requirements and fiber type preferences to volume trajectories and performance-driven adoption patterns.
- Regional demand and supply assessments that illuminate manufacturing localization trends, capacity expansions, and cross-border trade dynamics.
- Competitive benchmarking that evaluates technology differentiation, product portfolio breadth, and market share concentration among leading global and regional players.
- Regulatory and macroeconomic impact mapping that ties emissions mandates, raw material pricing trends, and policy implementation timelines to material demand pathways.
- Strategic implication frameworks that help leadership teams assess sourcing risks, capacity planning needs, and market entry or expansion opportunities in 2026 and beyond.
Each section is structured to support both board-level strategic review and operational planning functions. The report is intended for use by executives evaluating portfolio direction, product managers developing next-generation compound grades, procurement teams modeling cost and supply resilience, and analysts building market entry or competitive response strategies.
Strategic Imperatives for 2026 Planning
As organizations move into 2026 planning cycles, several strategic priorities will determine whether they capture growth or risk being outpaced by more agile competitors. First, aligning product development roadmaps with regulatory-driven lightweighting mandates will be essential, particularly in automotive and aerospace applications where emissions targets continue to tighten. Second, building pricing and sourcing resilience against raw material volatility requires anticipatory procurement models that incorporate regional price trends, supplier diversification, and inventory optimization. Third, competitive differentiation will increasingly depend on application engineering capabilities, co-development relationships with OEMs, and the ability to deliver consistent fiber dispersion and mechanical performance at scale.
Fourth, geographic strategy must account for shifting manufacturing footprints and localized content expectations, especially in regions where capacity expansion and supply chain reconfiguration are reshaping demand access. Finally, organizations that integrate macroeconomic scenario planning into their material strategy will be better positioned to navigate policy shifts, energy cost fluctuations, and sudden demand reallocations across end-use verticals. Our report provides the analytical foundation needed to operationalize these imperatives with confidence.
How to Use This Intelligence
The value of this research lies not only in the data it presents, but in how it enables decision-makers to convert complex market signals into coherent strategy. For executives, the report offers a consolidated view of growth trajectories, competitive intensity, and regulatory momentum, supporting capital allocation and portfolio prioritization. For strategy and business development teams, it provides segmentation and regional intelligence that can inform partnership selection, market targeting, and go-to-market sequencing. For procurement and supply chain leaders, it delivers context on input-cost trends and supplier concentration, helping to structure resilient sourcing frameworks. For R&D and product teams, the analysis connects application requirements with fiber architecture choices, guiding grade development and performance optimization efforts.
By maintaining a consistent focus on actionable insight rather than descriptive overview, the report is designed to integrate directly into planning workflows, risk assessments, and competitive response models. Readers will leave with a clear understanding of where the market is moving, which forces are accelerating or constraining growth, and how to position their organizations for sustained relevance in a rapidly evolving materials landscape.
Conclusion: The Case for Deeper Intelligence
The long glass fiber reinforced polypropylene market is being reshaped by a convergence of regulatory pressure, lightweighting demand, raw material volatility, and technological differentiation among leading compound manufacturers. Organizations that rely on surface-level market narratives risk misallocating resources, underestimating competitive intensity, or overlooking regional and application-level opportunities that could define their next phase of growth. This report is built to close that gap.
By combining a rigorously constructed historical baseline, a forward-looking forecast framework, segmentation depth, competitive benchmarking, and regulatory-macro integration, the research equips decision-makers with the intelligence required to act decisively in 2026 and prepare for the trajectory toward 2032. The full analysis provides the detailed regional breakdowns, application-level demand mappings, type-specific growth pathways, and competitive assessments necessary to translate strategic direction into execution. For teams seeking to move beyond general market awareness and into precise, defensible decision-making, the complete report offers the depth and structure required to lead with confidence.
For detailed analysis of this topic, please visit the official page: Long Glass Fiber Reinforced Polypropylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


