



PW Consulting: Heart Defect Closure Devices Market to Hit $344.8M by 2032, Growing at 6.98% CAGR

Strategic Intelligence for 2026: Navigating the Heart Defect Closure Devices Market Landscape
In the rapidly evolving landscape of structural heart interventions, the market for heart defect closure devices represents a critical nexus of clinical innovation, regulatory dynamics, and commercial opportunity. As we move through 2026, healthcare providers, investors, and competitive strategists require a granular understanding of where value is being created, how regulatory frameworks are reshaping market access, and which technological trajectories will define the next wave of growth. This executive briefing serves as an introduction to PW Consulting's comprehensive market research report on the Heart Defect Closure Devices Market, designed to equip leadership teams with the actionable intelligence necessary for robust strategic planning.
The Macro Trajectory: Growth Foundations and Forecast Horizon
Understanding the scale and momentum of this market is the foundational step for any strategic assessment. The industry has demonstrated consistent resilience and expansion over the recent historical period. Analyzing performance from 2020 through the base year of 2025 reveals a market that has steadily climbed in revenue terms, reflecting the increasing adoption of minimally invasive percutaneous solutions over traditional surgical approaches. This historical expansion sets the stage for a forecast period extending from 2026 through 2032, where the market is projected to continue its upward trajectory.
Our analysis indicates a compound annual growth rate (CAGR) of approximately 6.98 percent across the forecast horizon. This growth rate suggests a mature yet expanding market, driven by factors such as the rising prevalence of congenital heart defects, an aging population requiring interventions for conditions like patent foramen ovale, and continuous advancements in device delivery systems and materials. By the end of the forecast period in 2032, the total revenue size is anticipated to reach significant milestones, underscoring the enduring commercial relevance of this therapeutic area. For stakeholders, this macro view provides the essential context for evaluating pipeline investments, capacity planning, and long-term market entry strategies. The revenue unit is tracked in USD Millions, offering a standardized metric for global comparison and financial modeling.
The Strategic Value of Granular Segmentation in 2026 Decision-Making
While the top-line figures establish the market's magnitude, the true strategic leverage lies in dissecting the market across its dimensional layers. Our research delves deep into the segmentation architecture, categorizing the market by device type, clinical application, and geographic footprint. This multi-dimensional approach allows organizations to move beyond generic growth narratives and identify specific pockets of opportunity or vulnerability.
For device manufacturers and investors, understanding the breakdown by device type—encompassing atrial septal defect (ASD) closure devices, patent ductus arteriosus (PDA) closure devices, and ventricular septal defect (VSD) closure devices—is crucial for portfolio prioritization. The dominance of certain segments often reflects clinical preferences, reimbursement landscapes, and the concentration of specific patient populations. Our report quantifies these internal dynamics, revealing which device categories are driving the bulk of revenue and which are emerging as high-growth niches due to technological breakthroughs or unmet clinical needs.
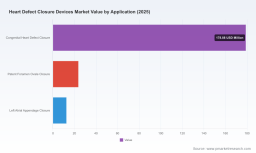
Similarly, the segmentation by clinical application provides a lens into the therapeutic drivers. The market encompasses congenital heart defect closure, patent foramen ovale closure, and left atrial appendage closure, among other applications. Each application area carries distinct regulatory pathways, procedural volumes, and competitive intensities. For instance, the dynamics in PFO closure have been heavily influenced by recent regulatory shifts and guideline updates, while left atrial appendage closure continues to evolve alongside anticoagulant alternatives. Our analysis pinpoints the revenue contribution of each application, helping strategists align product development and marketing resource allocation with the most potent clinical demand signals.
Geographically, the market exhibits distinct regional characteristics. We examine performance across key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Regional analysis is indispensable for global players assessing market penetration barriers, reimbursement variability, and the impact of local manufacturing or distribution partnerships. The data unpacks the relative weight of each region, highlighting where volume is concentrated and where growth rates may diverge from the global average due to healthcare infrastructure development or policy changes. This regional granularity enables precise tailoring of go-to-market strategies and risk mitigation plans for each territorial unit.
Regulatory Currents and Industry Dynamics Shaping Competitive Advantage
The regulatory environment acts as a powerful force multiplier in this market, influencing product lifecycles, competitive positioning, and speed to revenue. Recent years have witnessed significant activity within the FDA and other global regulatory bodies, particularly regarding Premarket Approval (PMA) pathways for structural heart devices. Our report integrates these regulatory milestones into the strategic narrative, demonstrating how approvals and clearances create windows of opportunity for innovators and disruptors.
A notable example of regulatory-driven market dynamics involves the recent PMA approvals for Occlutech Holding AG's ASD Occluder and Pistol Pusher system. Following the FDA's approval on December 29, 2023, and the subsequent commercialization efforts that accelerated in 2024, Occlutech has entered a phase of active US market implementation. The execution of the first commercial US cases in mid-2024 marks a critical inflection point, validating the device in the world's largest medical device market and establishing a foothold through exclusive partnerships, such as the collaboration with B. Braun Interventional Systems. This sequence of events illustrates how targeted regulatory success can rapidly translate into commercial traction, altering the competitive equilibrium.
The landscape is further defined by the ongoing presence and evolution of established players. Abbott Laboratories continues to leverage its Amplatzer line, with the Talisman PFO Occluder maintaining a prominent position following its 2021 approval. Additionally, recent clearances, such as the Abbott Amplatzer Piccolo Delivery System cleared in late 2025 for use with congenital heart defect closure devices, highlight continuous innovation in delivery mechanics that can enhance procedural efficacy and user adoption. Meanwhile, W. L. Gore & Associates maintains a relevant footprint with the GORE CARDIOFORM series for ASD and PFO closure, although the discontinuation of the GORE HELEX Septal Occluder underscores the iterative nature of product portfolios where legacy devices may be phased out in favor of next-generation solutions.
Analysis of current medical policy frameworks, such as those from Blue Cross Blue Shield of North Carolina in August 2025, confirms the specific devices currently marketed for PFO and ASD closure. This regulatory snapshot serves as a vital reference for understanding the eligible product set and the reimbursement environment that governs patient access. Strategists must monitor these policy documents closely, as they can dictate the commercial viability of devices within specific health systems and payer networks. Our report contextualizes these regulatory facts within broader industry trends, helping clients anticipate how policy changes might affect their product pipelines or competitor pipelines.
Competitive Architecture: Incumbents, Challengers, and Strategic Positioning
The competitive landscape of the heart defect closure devices market is characterized by a mix of global medtech giants and specialized players with deep clinical focus. Our comprehensive profiling of key companies provides a detailed view of the strengths, headquarters, and strategic focus areas of the major participants shaping the market.
Abbott Laboratories, headquartered in Chicago, Illinois, stands as a pivotal force with its extensive Amplatzer family of septal occluders. Their portfolio covers ASD, PFO, and VSD closure, representing a broad-based capability that addresses multiple defect types. Abbott's ability to integrate device innovation with delivery system advancements creates a holistic value proposition for interventional cardiologists and surgeons.
W. L. Gore & Associates, based in Flagstaff, Arizona, contributes with its GORE CARDIOFORM Septal Occluder and GORE CARDIOFORM ASD Occluder. These devices are specifically engineered for percutaneous closure of ostium secundum ASD and PFO, reflecting a targeted design philosophy focused on conformability and deliverability. The presence of Gore in this segment introduces a competitive alternative to traditional nitinol-based devices, appealing to clinicians seeking specific performance characteristics.
Occlutech Holding AG, headquartered in Schaffhausen, Switzerland, represents a dynamic challenger that has successfully navigated rigorous regulatory pathways. With FDA PMA approval for its ASD Occluder and Pistol Pusher, Occlutech has demonstrated the ability to bring novel transcatheter solutions to the US market. Their Figulla Flex series and specialized delivery tools indicate a focus on refining procedural control and device placement accuracy. The recent commercial implantation milestones in the US highlight their trajectory from regulatory clearance to real-world utilization.
Medtronic plc, with its global headquarters in Dublin, Ireland, brings the weight of a diversified structural heart portfolio. The CardioFlex ASD closure device and related occluders position Medtronic to capture volume across congenital heart defect closure indications. Medtronic's infrastructure and commercial reach provide significant advantages in distribution, physician education, and market coverage.
Boston Scientific Corporation, located in Marlborough, Massachusetts, offers structural heart occlusion systems and portfolio products addressing ASD and related defects. As a major player in the broader interventional cardiology space, Boston Scientific's involvement brings cross-portfolio synergies and a robust sales network capable of supporting device adoption.
From the Asia Pacific region, Lifetech Scientific Corporation in Shenzhen, China, and Lepu Medical Technology in Beijing, China, represent growing manufacturers with portfolios including the Lifestar line and various septal occluders for ASD, PFO, and VSD closure. These companies highlight the increasing innovation and manufacturing capacity emerging from China, which can influence global pricing dynamics and provide alternatives in cost-sensitive markets. Their presence also underscores the importance of monitoring non-US/EU competitors who are expanding their international footprints.
The market concentration data further illuminates the competitive structure. With a CR3 of approximately 24.6 percent and a CR5 of roughly 26.2 percent, the market does not exhibit extreme oligopolistic concentration. This relatively fragmented top-tier concentration suggests that while major players hold significant share, there is room for specialized entrants and regional players to compete effectively. It also implies that competitive advantage often derives from product differentiation, clinical evidence, regulatory agility, and strategic partnerships rather than pure scale dominance. Our report analyzes these concentration metrics to help firms assess the intensity of rivalry and the potential for market share erosion or consolidation.
Heart Defect Closure Devices Market
Inside the Report: Actionable Frameworks for Execution
This market research report is designed not merely as a repository of data points but as a strategic toolkit for execution. The report contents are structured to guide decision-makers through complex choices with clarity and confidence. Beyond the quantitative segmentation, the document provides qualitative assessments of market drivers, restraints, and opportunities. We analyze the factors accelerating adoption, such as the shift toward minimally invasive procedures, improvements in device safety profiles, and the expansion of eligible patient populations. Simultaneously, we identify headwinds, including reimbursement uncertainties, the learning curve associated with new delivery systems, and the competitive pressure from emerging technologies.
The report also incorporates a detailed examination of the value chain, mapping the roles of manufacturers, distributors, healthcare providers, and regulatory bodies. This holistic view enables clients to identify leverage points within the ecosystem. For example, understanding the nuances of FDA PMA requirements versus CE marking processes can inform product launch sequencing and resource allocation for regulatory affairs teams. Insights into recent industry developments, such as the specific timelines of Occlutech's US commercialization or Abbott's delivery system clearances, are synthesized to reveal patterns in how innovation translates to market share.
Worldwide Hernia Mesh Devices Market
Strategic frameworks within the report assist in evaluating potential M&A targets, assessing partnership opportunities, and benchmarking internal performance against market leaders. The inclusion of company profiles allows for direct comparison of product portfolios, geographic coverage, and strategic moves. By integrating the regulatory context with competitive analysis, the report helps organizations anticipate competitor responses to market shifts and prepare counter-strategies. Whether the objective is entering a new geographic market, launching a new device variant, or defending existing market share, the insights provided are tailored to support those specific use cases.
Conclusion: Securing Strategic Advantage in 2026 and Beyond
The heart defect closure devices market is at a juncture where clinical innovation, regulatory evolution, and competitive maneuvering converge to create significant strategic implications. For organizations operating in or adjacent to this space, the ability to make informed decisions quickly is a critical differentiator. The macro trends indicate sustained growth, but the distribution of that growth across segments, applications, and regions requires deep analysis to exploit effectively.
Regulatory milestones, such as the recent FDA approvals and clearances, are reshaping the roster of available devices and influencing payer policies. Companies that can navigate these pathways efficiently and bring differentiated products to market stand to gain substantial rewards. The competitive landscape, with its mix of global leaders and agile specialists, demands a nuanced understanding of where each player is positioned and how they are likely to move. Market concentration levels suggest that innovation and execution can outweigh sheer size in capturing value.
PW Consulting's comprehensive report offers the depth and precision required to thrive in this environment. It transforms raw data and industry observations into a coherent strategic narrative, empowering leadership teams to align their resources, mitigate risks, and capitalize on emerging opportunities. To access the full suite of segmentation data, detailed forecasts, competitor intelligence, and actionable recommendations, we invite you to explore the complete market research report. The complete intelligence package is essential for building a resilient strategy that delivers results in the dynamic years ahead.
For detailed analysis of this topic, please visit the official page: Heart Defect Closure Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


