



PW Consulting: Serial Device Server Market to Reach $317.3M by 2032 at 6.5% CAGR

Beyond Connectivity: Unlocking Strategic Value in the Serial Device Server Market (2026–2032)
The Critical Infrastructure Layer in a Legacy-Heavy World
Serial device servers sit at the intersection of legacy industrial hardware and modern IP networks—a position that makes them indispensable for enterprises managing brownfield automation, remote telemetry, and multi-vendor equipment integration. As industries accelerate their transition toward secure, centralized, and cloud-ready architectures, the devices that bridge RS-232, RS-422, and RS-485 endpoints to Ethernet and Wi-Fi backbones are experiencing sustained demand. Our newly released Serial Device Server Market research provides a comprehensive commercial and technical intelligence layer designed to inform capital allocation, product roadmap decisions, and competitive positioning through 2032.
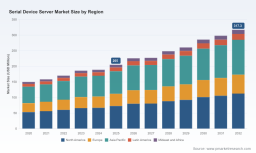
The market’s trajectory reflects a structural shift rather than a temporary cycle. Revenue reached an estimated 205.0 million USD in the base year of 2025, up from approximately 188.99 million USD in 2024 and 185.99 million USD in 2023, following a consistent upward path from 150.0 million USD in 2020. This growth curve underscores the durability of serial-to-Ethernet conversion in industrial control, data acquisition, remote management, and point-of-sale ecosystems, even as IT departments invest heavily in all-IP alternatives. The forecast period from 2026 to 2032 projects a compound annual growth rate of 6.5 percent, with total revenue anticipated to rise from roughly 225.84 million USD in 2026 to 317.3 million USD by 2032. These figures are not merely projections—they form the foundation for capacity planning, vendor negotiation, and risk-adjusted investment strategies.
For decision-makers navigating procurement cycles, product development, or market entry, this research delivers what high-level summaries cannot: a granular view of demand drivers, technology migration patterns, regulatory touchpoints, and the competitive behaviors shaping pricing, feature sets, and channel influence. The analysis is deliberately structured to support executive-level prioritization while preserving the depth required by engineering, supply chain, and regulatory teams.
Structural Demand Drivers: Why Serial Device Servers Remain Strategically Resilient
A central theme emerging from our analysis is the persistence of serial protocols in environments where reliability, determinism, and cost-effective interoperability outweigh the pull of full IP replacement. Industrial control systems, data acquisition networks, remote management deployments, and point-of-service infrastructure all rely on serial interfaces for legacy compatibility, field-hardened performance, and simplified wiring topologies. Rather than displacing these devices, modernization initiatives are increasing their strategic value by demanding secure gateways, centralized fleet management, and protocol-agnostic bridging.
Several dynamics are reinforcing this demand profile. First, the coexistence of operational technology and information technology stacks means that serial endpoints must be integrated into network architectures without disrupting uptime or requiring wholesale equipment replacement. Second, security expectations have evolved from basic connectivity to encrypted serial-to-IP tunnels, centralized authentication, and audit-ready management interfaces. Third, environmental and transportation-grade certifications are becoming gating factors in bidding processes for public infrastructure, manufacturing automation, and outdoor telemetry deployments. These factors collectively elevate the serial device server from a simple connectivity add-on to a programmable gateway component within broader edge networks.
The research also examines how network infrastructure economics influence deployment velocity. Ethernet interface cards and fiber-optic infrastructure remain primary cost drivers in serial device server network deployments, which means total cost of ownership is shaped not only by the gateway hardware itself, but by the surrounding physical layer, cabling, and integration labor. This reality has important implications for procurement strategy, vendor bundling, and the evaluation of modular platforms such as SFP-based hot-swappable designs that can delay or reduce physical-layer reinvestment.
Market Size, Growth Trajectory, and What the Numbers Really Signal
The macro-level trajectory provides a reliable anchor for strategic planning. After expanding from 158.23 million USD in 2021 and 170.18 million USD in 2022, the market crossed the 185 million USD threshold in 2023 and continued its ascent to 205.0 million USD in 2025. The short-term forecast indicates 225.84 million USD in 2026, followed by a slight moderation in year-over-year momentum before resuming steady growth to 227.25 million USD in 2027, 248.41 million USD in 2028, 260.47 million USD in 2029, 285.73 million USD in 2030, 298.04 million USD in 2031, and 317.3 million USD in 2032.
For strategy teams, the more important takeaway is the shape of this curve. The data suggests a market that is not only growing but maturing in its demand patterns: growth is increasingly tied to secure management, ruggedized industrial form factors, modular network compatibility, and certification readiness. Companies that treat serial device servers as commoditized pass-through hardware risk underpricing value-added features and missing higher-margin opportunities in industrial automation, remote fleet management, and hazardous-location deployments. Conversely, organizations that align product roadmaps with the specific integration requirements of brownfield environments can capture disproportionate share in segments where interoperability and compliance create meaningful barriers to substitution.
Our research deliberately avoids oversimplified regional or application-level breakdowns in this overview because the strategic value lies in how those segments interact with pricing, certification requirements, and channel dynamics. The full report details how demand clusters across geographies and application types, which subsegments are growing fastest in absolute and relative terms, and where saturation risk or substitution pressure is most likely to emerge.
Competitive Landscape: Differentiated Platforms in a Concentrated Environment
Market concentration provides an early signal of competitive intensity. The three largest players account for approximately 52.8 percent of revenue, while the five largest reach about 64.7 percent. This distribution indicates a market with established incumbents, meaningful product differentiation, and room for specialized challengers that compete on security, ruggedization, or form-factor innovation. Understanding how the leading vendors position their offerings is essential for both competitive benchmarking and partnership evaluation.
Pepperl+Fuchs, headquartered in Mannheim, Germany, emphasizes serial device server solutions aimed at industrial automation and transportation integration. Its ICDM-RX/TCP series delivers DIN-rail mounted RS-232/422/485 to Ethernet conversion with TCP/UDP socket services, and the inclusion of NEMA TS2 certification options expands its relevance for transportation-grade and industrial Ethernet environments. A product update in August 2025 extended this family with additional NEMA TS2 certification options, reinforcing the company’s focus on compliance-sensitive deployments.
Comtrol, operating as Pepperl+Fuchs Comtrol with headquarters in Twinsburg, Ohio, USA, focuses on secure serial-to-IP gateways. The DeviceMaster PRO/RTS/Serial Hub family supports COM/TTY/TCP configurations and has been strengthened with enhanced SSL/SSH encryption. In March 2025, the company updated the series with SSL/SSH management and serial data stream encryption for secure serial-to-IP connectivity, a move that reflects rising security expectations in industrial and enterprise edge contexts.
Digi International, based in Minneapolis, Minnesota, USA, continues to position its Digi Connect EZ TS and Connect SP series as secure serial device servers for legacy-to-IP conversion. The portfolio’s RealPort drivers and centralized management capabilities support organizations seeking to standardize remote access and device administration across distributed installations. In May 2026, Digi launched Digi Connect EZ TS 4-port and 8-port secure serial device servers with enhanced centralized management for modern IP network transitions, signaling continued investment in fleet management and migration-friendly architectures.
Moxa, headquartered in Taipei, Taiwan, targets industrial RS-232/422/485 to Ethernet conversion with the NPort 5100/5110 and IA5000 series. These platforms emphasize surge protection and hazardous-location certifications, making them relevant for demanding field environments. A February 2025 update improved the NPort IA5000-G2 DIN-rail and IA5000A industrial series with enhanced surge protection for hazardous environments, reinforcing Moxa’s focus on durability and compliance in industrial settings.
Advantech, also based in Taipei, Taiwan, offers the EKI-1521/1522/1524 series of industrial Ethernet/serial device servers with virtual COM support and LAN redundancy. This positioning speaks to customers who prioritize operational resilience, seamless device emulation, and network failover in automation and control environments.
Patton, headquartered in Gaithersburg, Maryland, USA, introduced a notable infrastructure-oriented product in April 2025 with the launch of the Connect-IT CIT-SFP SFP-based hot-swappable RS-232/422/485 serial device server for legacy-to-IP bridging. The SFP-based approach addresses network flexibility and physical-layer economics by enabling modular fiber or copper connectivity without full hardware replacement, an increasingly important consideration as deployment costs are scrutinized.
Silex Technology, based in Tokyo, Japan, provides the SD-300/SD-320 series of wired and wireless RS-232 serial device servers for Ethernet and Wi-Fi network connectivity. This wireless extension broadens the addressable use cases for serial endpoints where cabling constraints or temporary deployments make Wi-Fi connectivity advantageous.
Sealevel Systems, headquartered in Liberty, South Carolina, USA, focuses on the SeaLINK series of Ethernet serial servers supporting up to 16 RS-232/422/485 ports for industrial data acquisition and control systems. The multi-port architecture is particularly relevant for centralized monitoring and control applications that must aggregate many serial endpoints without proliferating gateway devices.
PLANET Technology, also headquartered in Taipei, Taiwan, offers the ICS-2100T/2200T/2400T series of industrial 1/2/4-port RS-232/422/485 to Fast Ethernet serial device servers with wide-temperature operation. This wide-temperature capability supports deployment in environments where thermal extremes would disqualify commercial-grade hardware.
The competitive picture is not just about product portfolios; it is about how vendors translate certification readiness, security, modularity, and environmental hardening into defensible pricing and customer lock-in. The research maps these positioning strategies and identifies the operational implications for buyers evaluating total cost of ownership, support requirements, and lifecycle compatibility.
Regulatory, Certification, and Deployment Dynamics That Shape Commercial Outcomes
Regulations and certifications are not side conditions; they are commercial gating factors that influence bid eligibility, deployment timelines, and regional expansion feasibility. In the United States, all active manufacturers of serial device server products must comply with FCC Part 15 rules for unintentional radiators to prevent harmful interference, a requirement that can affect design choices, testing cycles, and market entry sequencing. In the European Economic Area, serial device server equipment sold into the market requires CE marking under relevant EMC and safety directives, adding conformity assessment obligations that influence product planning and documentation.
Serial Device Server Market
Safety and industrial-use certifications further shape procurement and engineering decisions. Industrial serial device server models are commonly UL 61010-1 listed for safety in laboratory and industrial use, an assurance that matters in environments where equipment must meet recognized electrical safety standards. For transportation and public infrastructure applications, NEMA TS2 certification addresses spectrum and environmental compliance requirements, making it a strategic differentiator for vendors pursuing bids in transit and municipal deployments.
Together, these regulatory and certification layers contribute to a market in which product compliance is a source of competitive advantage rather than a back-office task. The report integrates these dynamics into the broader analysis of market behavior, showing how certification roadmaps, testing lead times, and regional conformity requirements interact with product launches, distributor selection, and customer segment prioritization.
What the Report Delivers: Operational Intelligence for 2026 Decisions
This research is designed as a decision-support instrument rather than a static market summary. It combines market sizing and growth projections with actionable qualitative analysis across segmentation, competitive behavior, and deployment dynamics. The core deliverable includes a structured assessment of external and embedded serial device server categories, an exploration of application-side demand patterns across industrial control systems, data acquisition, remote management, point-of-sale systems, and other use cases, and a detailed view of regional demand distribution without reducing the analysis to simplistic percentage tables.
Beyond segmentation, the report examines product evolution patterns, including secure serial-to-IP gateways, DIN-rail industrial form factors, multi-port aggregation platforms, SFP-based hot-swappable bridging, wide-temperature operation, surge protection for hazardous environments, and wireless serial connectivity. It also addresses the commercial significance of centralized management, virtual COM compatibility, LAN redundancy, RealPort-style driver ecosystems, and encryption frameworks such as SSL/SSH. These feature dimensions are analyzed in relation to pricing architecture, differentiation potential, and customer acceptance in regulation-sensitive or environment-sensitive deployments.
Competitive analysis extends beyond product descriptions to include launch timing, update cadence, and strategic intent. Recent developments illustrate how the market is evolving: Patton’s April 2025 launch of the CIT-SFP SFP-based hot-swappable serial device server for legacy-to-IP bridging; Digi International’s May 2026 launch of Digi Connect EZ TS 4-port and 8-port secure serial device servers with enhanced centralized management; Comtrol’s March 2025 update to the DeviceMaster PRO/RTS series with SSL/SSH management and serial data stream encryption; Pepperl+Fuchs’ August 2025 extension of the ICDM-RX/TCP family with NEMA TS2 certification options; and Moxa’s February 2025 update to the NPort IA5000-G2 and IA5000A series with enhanced surge protection for hazardous environments. These events are not isolated product news; they reflect broader strategic bets on security, modularity, ruggedization, and compliance-enabled market access.
How to Use This Research for 2026 Planning
For executives and analysts, the report offers a practical framework for several high-stakes decisions. Procurement leaders can use the segmentation and competitive analysis to structure vendor evaluations around security, management, ruggedization, and certification readiness rather than unit price alone. Product and engineering teams can reference the technology migration patterns to prioritize virtual COM, centralized management, encryption, and modular network compatibility in roadmaps. Business development teams can identify where certification requirements and environmental hardening create entry barriers that protect incumbents or where wireless and multi-port platforms open new addressability. Risk and compliance teams can integrate FCC Part 15, CE marking, UL 61010-1, and NEMA TS2 considerations into market-entry and sourcing plans with a clearer view of lead times and documentation requirements.
The analysis also supports scenario planning by connecting market growth, concentration levels, and infrastructure cost realities to potential shifts in pricing, bundling, and channel influence. Because Ethernet interface cards and fiber-optic infrastructure remain primary cost drivers in network deployments, total project economics often depend on how serial device server platforms align with existing or planned physical-layer investments. The report provides the context needed to evaluate whether modular, hot-swappable, or multi-port solutions offer better lifecycle economics in specific deployment profiles.
Conclusion: From Market Data to Decision Advantage
The Serial Device Server Market is growing within a 6.5 percent CAGR framework and is projected to move from 225.84 million USD in 2026 to 317.3 million USD by 2032, but the strategic opportunity lies in understanding why that growth is happening, where value is being captured, and how competitive and regulatory forces shape customer choices. This research translates those dynamics into an actionable intelligence base for procurement, product strategy, market entry, and competitive positioning.
SerDes Market
The overview above establishes the analytical direction and the breadth of coverage, while the full report provides the structured detail required to support discrete decisions across regions, applications, product types, and competitive scenarios. For teams preparing for 2026 planning cycles, the complete analysis offers the missing layer between high-level market narratives and operational execution—enabling more confident capital allocation, vendor selection, and roadmap prioritization in a market where connectivity, compliance, and industrial reliability all converge.
For detailed analysis of this topic, please visit the official page: Serial Device Server Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


